TL;DR
AXA PPP healthcare is the former name of AXA Health, one of the UK's largest health insurers. The PPP name dates back to the Private Patients Plan. If you have an older AXA PPP policy, your cover now sits with AXA Health.
Key takeaways
- AXA PPP healthcare is the former name for AXA Health, which rebranded in 2020 to reflect a broader focus on wellbeing.
- The acronym PPP stands for Private Patients Plan, a pioneering health insurance organisation founded in 1940.
- AXA Health's core cover includes in-patient treatment, comprehensive cancer care and access to a 24/7 digital GP service.
- Pre-existing and chronic conditions are usually excluded from standard private medical insurance policies, depending on underwriting.
- You can tailor an AXA Health policy with optional add-ons like out-patient cover, mental health support and therapies.
AXA PPP Healthcare: What It Is and How It Relates to AXA Health
AXA PPP healthcare is the former name of AXA Health, a major provider of private medical insurance in the UK. The acronym PPP stands for Private Patients Plan, which was the original name of the organisation founded in 1940.
If you are researching private medical cover, you may still see references to AXA PPP, AXA Health PPP, or simply PPP healthcare. This guide explains the history of the name, how AXA Health policies are structured today, and what you should consider when looking for cover.
What does PPP stand for in AXA PPP healthcare?
The letters PPP stand for Private Patients Plan. The organisation was established in 1940 to provide health insurance for individuals in the UK. Over the decades, it grew into one of the country's largest private medical insurers.
In the late 1990s, the Private Patients Plan was acquired by the global AXA Group, and the UK health insurance division was renamed AXA PPP healthcare. In 2020, the company rebranded again, dropping the PPP acronym to become simply AXA Health.
Despite the rebrand, many people still search for terms like "axappp", "axa ppp health care", "ppp axa", and "axappphealthcare". If you hold an older policy that says AXA PPP or Private Patients Plan on the documents, your cover remains valid and is now managed by AXA Health.
How AXA Health (formerly AXA PPP) private medical insurance works
Before looking at specific policy features, it is important to understand the fundamental principles of private medical insurance in the UK.
Standard private medical insurance is designed to cover acute conditions that arise after a policy begins. An acute condition is a disease, illness, or injury that is likely to respond quickly to treatment and lead to a full recovery, such as a hernia or cataracts.
Conversely, chronic conditions—illnesses that require ongoing management, have no known cure, or are likely to recur, such as asthma or diabetes—are generally not covered. Furthermore, pre-existing conditions are usually excluded, depending on the underwriting terms of the policy.
Core cover and AXA Doctor at Hand
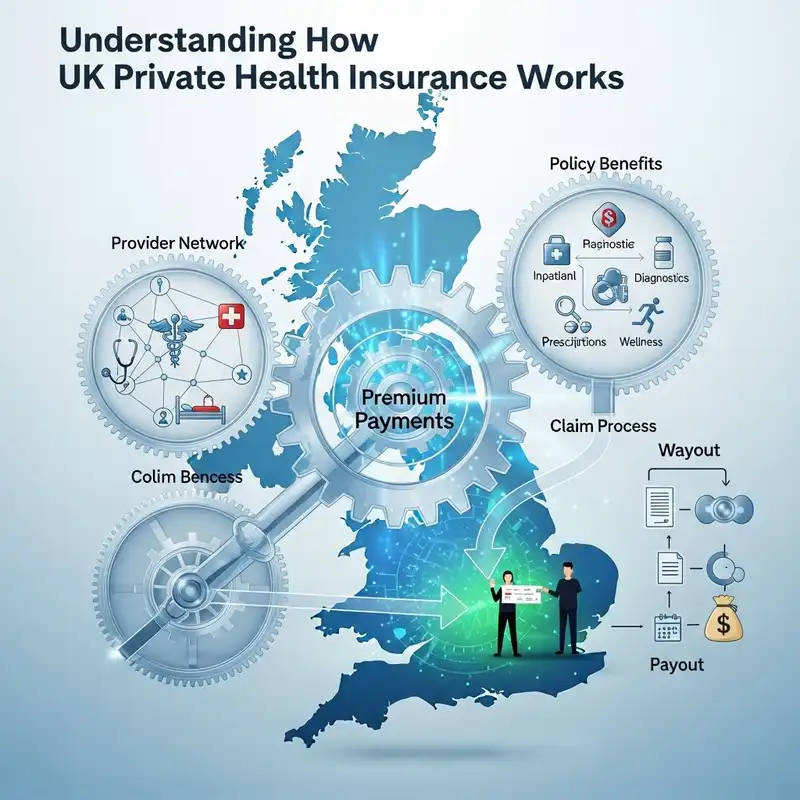
AXA Health's main individual policy is typically called Personal Health. Like many modern health insurance policies, it is built around a core foundation of cover, to which policyholders can add optional modules.
The core cover usually includes:
- In-patient and day-patient treatment: This covers the costs of hospital accommodation, nursing care, specialist fees, and anaesthetist fees when you are admitted to a hospital for a procedure.
- Comprehensive cancer cover: This typically covers the diagnosis and treatment of cancer, which may include surgery, chemotherapy, radiotherapy, and access to certain drugs not routinely available on the NHS, depending on the policy terms.
- AXA Doctor at Hand: A 24/7 digital GP service that allows members to book video or phone appointments with a doctor, often on the same day.
AXA Health maintains a Directory of Hospitals. Policyholders can typically choose between a standard list, which includes a wide range of private hospitals across the UK, or a guided option, which may restrict the choice of consultant but can lower the premium. There is also usually an option to upgrade the hospital list to include premium central London facilities, which increases the cost.
Optional out-patient and mental health add-ons
To build a more comprehensive plan, individuals can usually select optional add-ons. These increase the level of cover but will also increase the monthly premium.
- Out-patient cover: Core cover deals with treatment when you are admitted to a hospital bed. Out-patient cover pays for the specialist consultations and diagnostic tests (such as MRI, CT, or PET scans) needed to find out what is wrong. AXA Health typically offers different levels of out-patient cover, such as a standard option (which may limit specialist consultations to a set number per year) and a full option (with no yearly limit).
- Mental health cover: This module may provide cover for psychiatric treatment, including specialist consultations and talking therapies.
- Therapies: This add-on typically covers a set number of sessions for treatments like physiotherapy, osteopathy, and chiropractic care.
- Dental and optical cover: This usually functions as a cashback benefit, similar to how health cash plans operate, allowing policyholders to claim back a portion of the costs for routine dental check-ups, fillings, and eye tests, up to an annual limit.
| Policy Component | What It Typically Covers | Is It Standard on AXA's Plan? |
|---|---|---|
| Core Cover | Hospital stays for surgery, comprehensive cancer care, digital GP access. | Yes, this forms the foundation. |
| Out-patient Add-on | Specialist consultations, diagnostic tests, MRI/CT scans. | Optional. |
| Therapies Add-on | Physiotherapy, osteopathy, chiropractic sessions. | Optional. |
| Mental Health Add-on | Consultations and treatment for mental health conditions. | Optional. |
Pre-existing conditions and medical underwriting
When applying for private health insurance, insurers use a process called medical underwriting to determine what will and will not be covered. Pre-existing conditions are usually excluded. There are two main types of underwriting for individual policies:
- Moratorium Underwriting: This is a common approach where you do not have to complete a detailed medical questionnaire upfront. Instead, the policy automatically excludes any medical condition for which you have experienced symptoms, received treatment, or sought advice in the five years prior to the policy start date. If you then go for a continuous two-year period after joining without needing any treatment, advice, or medication for that condition, it may become eligible for cover.
- Full Medical Underwriting (FMU): With this method, you complete a comprehensive medical questionnaire when you apply. The insurer assesses your medical history and lists specific conditions that will be permanently excluded from your policy from the start. This approach provides clarity on exactly what is covered before you need to make a claim.
What to do in a medical emergency
It is crucial to understand that private medical insurance does not cover emergency care. Private hospitals in the UK generally do not have emergency departments equipped to handle critical trauma, severe accidents, or acute medical emergencies like heart attacks or strokes.
If you or a family member experience a life-threatening emergency, you should call 999 immediately or go directly to your nearest NHS Accident and Emergency (A&E) department. For urgent medical problems that are not life-threatening, you should contact NHS 111 for advice. Once the emergency has been stabilised by the NHS, you may be able to use your private medical insurance for subsequent elective surgeries or ongoing recovery, depending on the policy terms.
How much does AXA Health insurance cost?
There is no single price for private medical insurance. The cost of a policy depends entirely on the individual and the level of cover chosen. When calculating how much private health insurance costs, insurers consider several risk factors:
- Age: Premiums typically increase as you get older, reflecting the higher likelihood of needing medical treatment.
- Location: The cost of private healthcare varies across the UK. Central London is usually the most expensive region, so your postcode will influence your premium.
- Level of cover: A policy that includes comprehensive out-patient cover, mental health support, and therapies will cost more than a basic core-only plan.
- Excess: This is the amount you agree to pay towards a claim each policy year. Choosing a higher excess (for example, £500 instead of £100) usually lowers the monthly premium.
- Hospital list: Insurers maintain directories of eligible hospitals. A plan that includes access to premium central London hospitals will be more expensive than one restricted to a regional or guided network.
AXA Health for businesses and employers
AXA Health also provides private medical insurance for businesses, ranging from small enterprises to large corporations. Employer-provided health insurance is a common benefit in the UK, designed to help employees access medical care promptly.
Business policies often operate differently from individual plans. For example, larger corporate schemes may offer Medical History Disregarded (MHD) underwriting, which can cover eligible pre-existing conditions, depending on the policy terms. If you are an employee covered by an AXA Health workplace scheme, the premiums paid by your employer are typically treated as a benefit in kind for tax purposes.
Switching your PPP health insurance to a new provider
If you currently hold an AXA Health policy (or an older AXA PPP plan) and wish to explore other options, you can switch to a different insurer. Many people compare providers to see if they can find more suitable cover or a different premium structure.
Switching is often managed using a process known as Continued Personal Medical Exclusions (CPME). With CPME underwriting, a new insurer may agree to carry over the medical exclusions from your existing policy, rather than applying new moratorium rules. This allows you to change providers while generally maintaining cover for conditions that your previous insurer had already agreed to cover, subject to the new insurer's specific terms and acceptance criteria.
When switching, the new insurer will review your medical history and the terms of your existing AXA PPP or AXA Health policy. It is important to note that the new policy will be subject to the new insurer's own terms, conditions, and benefit limits, which may differ from your original plan. A specialist can help you compare these details to ensure the new policy meets your requirements.
How a specialist at WeCovr or one of its broker partners can help
Choosing the right private medical insurance requires careful consideration of your healthcare needs and budget. WeCovr is an FCA-regulated broking firm, and a specialist at WeCovr or one of its broker partners can help you navigate the market.
A specialist can compare policies from AXA Health alongside other UK insurers to help you understand the differences in core cover, optional add-ons, and underwriting methods. There is no extra cost or fee to you for using this service. Brokers are usually paid a commission by the insurer when a policy is arranged.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare options from AXA Health and other providers to find the right private medical insurance for your needs. Get a private medical insurance quote now.
What does PPP stand for in AXA PPP?
Is AXA PPP the same as AXA Health?
Does AXA Health cover pre-existing conditions?
Does private medical insurance cover A&E visits?
Sources
- AXA Health, Personal Health Overview, 2026
- AXA Health, Personal Health Insurance Product Information Document (IPID), 2026
Important Information and Risks
No advice: This article is for general information only. It is not financial, legal, insurance, or tax advice, and it is not a personal recommendation. WeCovr does not assess your individual circumstances or recommend a specific product through this article.
Policy exclusions and underwriting: Insurance policies, including life insurance, private medical insurance, critical illness cover, and income protection, are subject to insurer underwriting, eligibility, acceptance criteria, terms, conditions, limits, and exclusions. Pre-existing medical conditions may be excluded, restricted, or accepted on special terms unless an insurer confirms otherwise in writing.
Tax treatment: References to tax treatment, HMRC rules, or business reliefs are based on current UK legislation and guidance, which can change. Tax treatment depends on your personal or business circumstances and may differ from examples in this article.
Before you buy: Always read the Insurance Product Information Document (IPID), policy summary, and full policy terms before buying, renewing, changing, or keeping cover. If you are unsure whether a policy is suitable for you, speak to an insurance adviser.
Start with your Protection Score, then decide whether private health cover is the right fit
Check where health access sits in your overall protection picture before deciding whether to compare private health cover.
Spot whether NHS access risk is the real issue
See if PMI is the gap to fix first
Get health insurance help only if it makes sense for you
Get your score
Start with your protection score
Check your current position first, then get health insurance help if you need it.
Check your current resilience
Score your income, health access and family protection position in a few minutes.
See where private cover helps
Understand whether faster diagnosis and treatment is a priority gap.
Continue to tailored PMI help
If health access is the issue, continue to tailored PMI help.
What you get
A quick view of your current protection position
A clearer idea of where the biggest gaps may be
A direct route to tailored help if you want it