TL;DR
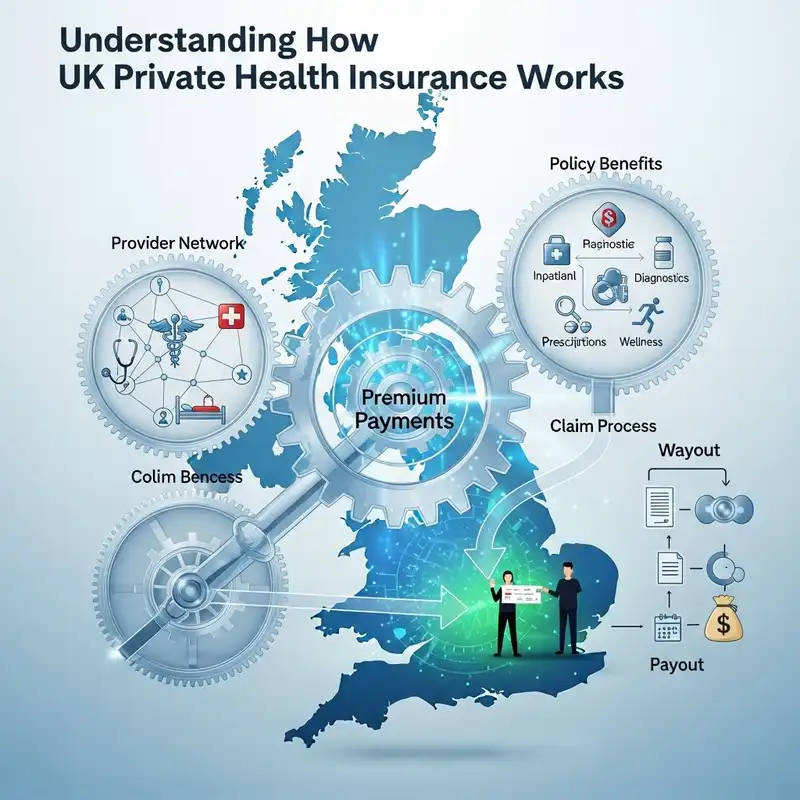
Bupa does not publish a fixed price list: each quote depends on your age, postcode, the hospital list, outpatient cover, excess and underwriting. This guide explains what drives a Bupa quote, how Bupa's options change the price, what the Bupa fee schedule means for you, and how to compare Bupa fairly with other insurers.
Key takeaways
- Bupa prices are personal: age, postcode and level of cover drive most of the cost.
- Hospital list, outpatient limit and excess are the main ways to reduce a Bupa premium.
- Bupa's fee schedule sets the maximum it pays consultants for each procedure.
- Using a fee-assured consultant helps avoid a shortfall you would have to pay.
- Compare Bupa against other insurers on the same cover, not just the headline price.
PMI comparison check
Bupa is not always the best fit for everyone.
The right provider depends on what you want covered, how much flexibility you need, and whether the premium still looks sensible once underwriting and hospital access are factored in.
Why this may help
Price pages are usually most useful when they help you compare fit first, then quotes second.
Takes around 30 seconds to get started.
General guidance only.
Bupa is one of the best-known health insurers in the UK. Like other insurers, it does not publish a single price for its personal health insurance. Each quote is calculated for you, so two people can pay very different amounts for what looks like the same policy.
What a Bupa quote is based on
- Your age: the biggest single factor, and one reason prices rise at renewal.
- Where you live: prices are usually higher in London and the South East.
- Level of cover: basic plans focus on inpatient and day-patient treatment; fuller plans add outpatient cover, therapies, mental health and wider cancer cover.
- Hospital list: a more restricted list is cheaper than one with central London hospitals.
- Outpatient limit: none, a yearly cap or full cover.
- Excess: the amount you pay towards a claim. A higher excess means a lower premium.
- Underwriting: moratorium or full medical underwriting.
- Claims history: some policies include a no-claims discount that falls after a claim.
How much might Bupa cost?
Because Bupa's prices are personal, the only accurate figure is a quote. As a general guide to the UK market, a healthy adult in their 30s might pay roughly £45 to £110 a month depending on the level of cover, and someone in their 60s roughly £130 to £310. Bupa may be above or below these figures for your age, postcode and choices. See how much private health insurance costs for prices by age.
Ways to lower a Bupa premium
- Choose a hospital list that suits where you live. Leave out central London hospitals if you would not use them.
- Set an outpatient limit that pays for initial consultations and scans, rather than full cover.
- Increase the excess to an amount you could pay comfortably.
- Consider the six-week option, where the NHS treats you if it can within six weeks, and the policy pays if it cannot.
- Only add the extras you will use, such as therapies, mental health or dental and optical options.
Each choice reduces what the policy pays for, so understand the trade-off before choosing.
What is the Bupa fee schedule?
Searches for "Bupa fee schedule" are common. Bupa sets a schedule of the maximum amounts it will pay specialists for consultations and procedures. Many consultants are fee-assured by Bupa, which means they agree to charge within those limits. If you see a consultant who charges more than Bupa's limit, you may have to pay the difference, called a shortfall.
To avoid a shortfall:
- Ask Bupa to confirm your consultant is fee-assured before treatment.
- Get pre-authorisation for the treatment and check what will be paid.
- Ask the consultant's secretary about fees in advance.
The same idea applies with other insurers, which also set limits for specialists' fees.
What Bupa health insurance does not usually cover
- Emergency treatment, which is provided by the NHS.
- Chronic conditions that need long-term management.
- Pre-existing conditions, at least at first, depending on underwriting.
- Routine pregnancy and childbirth.
- Cosmetic treatment.
Always check the policy documents for the exact exclusions.
How to compare Bupa with other insurers
Compare quotes on the same excess, outpatient limit and hospital list. Then look beyond the price at cancer cover, mental health cover, therapy limits and how each insurer handles pre-existing conditions. Bupa, Aviva, AXA Health, Vitality, WPA and The Exeter all offer personal cover with different strengths. See how to choose private health insurance.
Get a quote
WeCovr is an FCA-regulated broking firm. Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare Bupa with other UK insurers on the same level of cover. Brokers are usually paid a commission by the insurer when a policy is arranged.
Get a private health insurance quote
How much is Bupa per month?
There is no single monthly cost for Bupa health insurance, as illustrative premiums can range from a few tens of pounds for basic policies to well over a hundred pounds a month for more extensive cover. These figures are purely illustrative examples; your actual monthly premium is not guaranteed and will vary based on your age, location, and the level of cover you choose.
When budgeting for a monthly premium, it is important to understand the key risks and limitations. Paying a monthly fee does not mean all medical care is included. Policies usually exclude pre-existing medical conditions and do not cover emergency treatment; in any medical emergency, you must always call 999 or go to A&E.
Your monthly cost is also influenced by policy limits and excesses. Choosing a higher excess—the amount you pay towards a claim—may lower your monthly premium, but you must pay this out of pocket if you claim. Policies typically apply limits to benefits, such as a capped amount for outpatient consultations or a set number of therapy sessions, subject to underwriting and policy terms.
Furthermore, monthly premiums are reviewable and can rise at renewal due to your age, claims history, or general medical inflation, and your cover will end if you stop paying them. Because suitability depends on your circumstances, a specialist at WeCovr, an FCA-regulated broking firm, or one of its partners can help you compare options from a range of UK insurers. WeCovr and its broker partners are usually paid a commission by the insurer when a policy is arranged. Most brokers on WeCovr's panel do not charge a separate fee for health insurance, but please confirm this with your broker before you buy.
Frequently asked questions
How much is Bupa health insurance per month?
Why is my Bupa renewal more expensive?
What does fee-assured mean with Bupa?
Does Bupa cover pre-existing conditions?
Sources
- Bupa: personal health insurance product information and consultant fee guidance
- Association of British Insurers: private medical insurance claims and membership figures for 2024 (published January 2026)
Important Information and Risks
No advice: This article is for general information only. It is not financial, legal, insurance, or tax advice, and it is not a personal recommendation. WeCovr does not assess your individual circumstances or recommend a specific product through this article.
Policy exclusions and underwriting: Insurance policies, including life insurance, private medical insurance, critical illness cover, and income protection, are subject to insurer underwriting, eligibility, acceptance criteria, terms, conditions, limits, and exclusions. Pre-existing medical conditions may be excluded, restricted, or accepted on special terms unless an insurer confirms otherwise in writing.
Tax treatment: References to tax treatment, HMRC rules, or business reliefs are based on current UK legislation and guidance, which can change. Tax treatment depends on your personal or business circumstances and may differ from examples in this article.
Before you buy: Always read the Insurance Product Information Document (IPID), policy summary, and full policy terms before buying, renewing, changing, or keeping cover. If you are unsure whether a policy is suitable for you, speak to an insurance adviser.
Still deciding?
Most people find it easier to compare providers based on their situation rather than guessing from price alone.
A quick decision check can help you see whether Bupa is likely to fit, or whether another PMI route deserves a closer look first.
A practical next step
A quick review can help you decide whether there is a real gap worth acting on, rather than leaving you with more unanswered questions.
Useful if you want a clearer answer, not just more information.
General guidance only.
Get a quote
Get a private health insurance quote
Answer a few questions, then a specialist helps you compare cover and prices.
Tell us who needs cover
Just you, a partner, your family or your staff.
Compare your options
A specialist compares cover and prices from leading UK insurers.
Decide in your own time
There is no obligation to buy.
What you get
A specialist from WeCovr or one of its broker partners
Options compared across leading UK insurers
No obligation to buy