TL;DR
The landscape of healthcare has undergone a significant shift in recent years, largely due to the emergence of Post-Viral Syndromes (PVS) and, more specifically, Long COVID. These complex conditions, characterised by a persistent constellation of debilitating symptoms long after the initial viral infection, present unique challenges for individuals seeking diagnosis, treatment, and sustained recovery. While the NHS provides foundational care, the sheer volume of cases and the intricate nature of these syndromes often mean extended waiting lists and limited access to highly specialised, multidisciplinary care.
Key takeaways
- Harley Street Clinics: Many individual specialists and small clinics along Harley Street and surrounding areas offer bespoke consultations with neurologists, cardiologists, respiratory physicians, and immunologists focusing on post-viral sequelae.
- Large Private Hospitals: Institutions like The London Clinic, King Edward VII's Hospital, and the Cleveland Clinic London often have integrated diagnostics and specialists who can manage complex multi-system conditions.
- Dedicated Rehabilitation Centres: Some private centres focus purely on rehabilitation, offering tailored physiotherapy, occupational therapy, psychological support, and nutritional advice for chronic fatigue and post-viral recovery. These may be standalone or part of larger hospital groups.
- Integrated Wellness Centres: A smaller number of clinics take a more holistic approach, combining conventional medicine with complementary therapies, which may appeal to those seeking broader well-being support for Long COVID.
- If symptoms began before your policy started: This is the most common scenario. If you developed Long COVID symptoms in March 2020 and took out a policy in January 2021, those symptoms and any related conditions are pre-existing and will be excluded. This applies even if you didn't have a formal diagnosis at the time of application, but simply experienced the symptoms.
London Private Health Insurance Long Covid Post Viral
London Private Health Insurance for Post-Viral Syndromes & Long COVID Recovery Clinics
The landscape of healthcare has undergone a significant shift in recent years, largely due to the emergence of Post-Viral Syndromes (PVS) and, more specifically, Long COVID. These complex conditions, characterised by a persistent constellation of debilitating symptoms long after the initial viral infection, present unique challenges for individuals seeking diagnosis, treatment, and sustained recovery. While the NHS provides foundational care, the sheer volume of cases and the intricate nature of these syndromes often mean extended waiting lists and limited access to highly specialised, multidisciplinary care.
For many Londoners grappling with the long-term effects of viral illness, navigating this new reality can be incredibly isolating and frustrating. The desire for quicker access to expert consultations, advanced diagnostics, and comprehensive rehabilitation programmes often leads individuals to explore private healthcare options. This article aims to be your definitive guide to understanding how private health insurance in London can – and crucially, cannot – support individuals seeking care for Post-Viral Syndromes and Long COVID, including access to the capital's burgeoning recovery clinics.
We will delve into the intricacies of private medical insurance (PMI), unpack the critical exclusions concerning pre-existing and chronic conditions, and outline the types of services that might be covered. Our goal is to provide insightful, helpful, and comprehensive information to empower you to make informed decisions about your health and financial future.
Understanding Post-Viral Syndromes and Long COVID
Before we delve into the specifics of insurance, it's essential to grasp what we mean by Post-Viral Syndromes and Long COVID. While not new concepts in medicine, their prevalence has surged dramatically in the wake of the COVID-19 pandemic.
Post-Viral Syndromes (PVS) refer to a group of conditions that manifest after an acute viral infection, where symptoms persist for weeks, months, or even years beyond the typical recovery period. Common examples include Myalgic Encephalomyelitis/Chronic Fatigue Syndrome (ME/CFS), which can often be triggered by viral infections, and now, Long COVID. These syndromes are characterised by a diverse range of symptoms, impacting multiple body systems.
Long COVID, or Post-COVID-19 Condition, is defined by the National Institute for Health and Care Excellence (NICE) as signs and symptoms that develop during or after an infection consistent with COVID-19, continue for more than 12 weeks, and are not explained by an alternative diagnosis. It typically presents with clusters of symptoms that often overlap, fluctuate, and can affect any body system.
Common Symptoms of PVS and Long COVID:
- Fatigue: Profound, debilitating fatigue that is not relieved by rest and often worsens after physical or mental exertion (post-exertional malaise).
- Cognitive Dysfunction ("Brain Fog"): Difficulties with memory, concentration, information processing, and executive function.
- Respiratory Symptoms: Shortness of breath, cough, chest tightness.
- Cardiovascular Symptoms: Palpitations, chest pain, irregular heartbeat.
- Neurological Symptoms: Headaches, dizziness, nerve pain, numbness, pins and needles, loss of taste or smell.
- Musculoskeletal Pain: Joint pain, muscle aches, unexplained pain.
- Gastrointestinal Issues: Abdominal pain, nausea, diarrhoea, constipation.
- Sleep Disturbances: Insomnia, unrefreshing sleep.
- Mental Health Issues: Anxiety, depression, PTSD.
- Autonomic Dysfunction (Dysautonomia): Including Postural Orthostatic Tachycardia Syndrome (POTS), affecting heart rate, blood pressure, digestion, and temperature control.
The unpredictable and multi-system nature of these conditions makes diagnosis and management complex. Individuals often face a long and winding road to recovery, requiring a highly personalised and multidisciplinary approach.
The Challenge of NHS Provision
The NHS has made significant strides in establishing Long COVID clinics across the UK, including many in London. These clinics aim to provide integrated care, bringing together various specialists. However, the scale of the problem is immense.
- As of January 2024, an estimated 1.9 million people in the UK were experiencing self-reported Long COVID, with 54% reporting symptoms for at least a year, and 29% for at least two years (Office for National Statistics).
- Waiting lists for NHS Long COVID clinics can be substantial, often extending to many months, during which time symptoms can worsen and quality of life can significantly deteriorate.
- While comprehensive, NHS services may not always offer the prompt access, where available, to specific specialist consultations or advanced diagnostic techniques that some private clinics can provide. Furthermore, the focus might be on symptom management rather than intensive rehabilitation.
This disparity in access and speed of care is a primary driver for individuals exploring private health insurance options in London.
The Allure of Private Healthcare in London for PVS/Long COVID
London is a global hub for medical excellence, boasting an impressive array of private hospitals, clinics, and world-renowned specialists. For those suffering from complex conditions like PVS and Long COVID, private healthcare offers several compelling advantages:
Table 1: NHS vs. Private Healthcare for PVS/Long COVID Recovery
| Feature | NHS Provision | Private Healthcare Provision |
|---|---|---|
| Access/Waiting | Often long waiting lists for specialist appointments and clinics. | Quicker access to specialist consultations and diagnostic tests. |
| Specialists | Multidisciplinary clinics, but limited choice of specific consultants. | Wider choice of specific consultants, often world-leaders in their field. |
| Diagnostics | Standard diagnostic pathways, potentially phased over time. | Faster access, where available, to advanced diagnostic imaging (e.g., cardiac MRI, specific neurological scans) and lab tests. |
| Treatment Options | Evidence-based, often phased. May have limited access to specific therapies. | Broader range of therapies, potentially including innovative or integrated approaches (e.g., tailored rehabilitation, advanced pain management). |
| Continuity of Care | Can vary depending on clinic structure and staff rotation. | Greater continuity with specific consultants and care teams. |
| Environment | Hospital settings, often busy. | Private hospital rooms, more tranquil environment. |
| Cost | Free at the point of use. | Significant out-of-pocket costs without insurance; covered by insurance if eligible. |
The ability to bypass lengthy waiting times for initial consultations, access a wider pool of highly experienced specialists, and undergo comprehensive diagnostic testing quickly can be invaluable when dealing with a debilitating and poorly understood condition. London's private sector has responded to the Long COVID challenge by establishing dedicated recovery clinics, often with a multidisciplinary focus.
Examples of London's Private Long COVID Recovery Clinics (Illustrative)
While we cannot endorse specific clinics, it's worth noting the types of facilities that have emerged in London's private sector to address Post-Viral Syndromes and Long COVID:
- Harley Street Clinics: Many individual specialists and small clinics along Harley Street and surrounding areas offer bespoke consultations with neurologists, cardiologists, respiratory physicians, and immunologists focusing on post-viral sequelae.
- Large Private Hospitals: Institutions like The London Clinic, King Edward VII's Hospital, and the Cleveland Clinic London often have integrated diagnostics and specialists who can manage complex multi-system conditions.
- Dedicated Rehabilitation Centres: Some private centres focus purely on rehabilitation, offering tailored physiotherapy, occupational therapy, psychological support, and nutritional advice for chronic fatigue and post-viral recovery. These may be standalone or part of larger hospital groups.
- Integrated Wellness Centres: A smaller number of clinics take a more holistic approach, combining conventional medicine with complementary therapies, which may appeal to those seeking broader well-being support for Long COVID.
Access to these clinics through private health insurance is often the goal for many individuals. However, the path to coverage is not always straightforward, particularly due to the nature of Post-Viral Syndromes.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Understanding Private Health Insurance in the UK
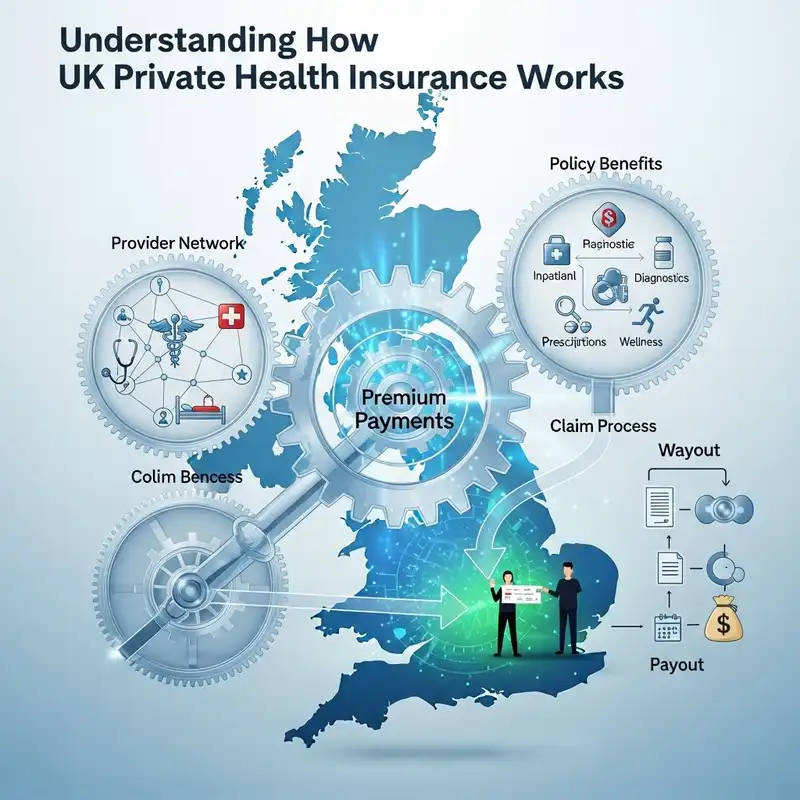
Private Medical Insurance (PMI) in the UK works by covering the cost of private medical treatment for acute conditions that develop after your policy starts. It's designed to complement, not replace, NHS services.
Key Principles of PMI:
- Acute vs. Chronic Conditions: This is the most fundamental distinction.
- Acute Conditions: A disease, illness, or injury that is likely to respond quickly to treatment or that is likely to change or develop over a relatively short period. Examples might include a broken bone, appendicitis, or a new, sudden onset illness. These are generally covered.
- Chronic Conditions: A disease, illness, or injury that has one or more of the following characteristics: it needs ongoing or long-term management; it requires a prolonged period of observation; it needs to be rehabilitated; it continues indefinitely; it comes back or is likely to come back. Examples include diabetes, asthma, epilepsy, and importantly, conditions like ME/CFS and often, Long COVID. These are generally not covered by standard PMI policies.
- Pre-existing Conditions: Any medical condition for which you have received symptoms, medication, advice, or treatment in a specified period (usually 2-5 years) before the start of your policy. Pre-existing conditions are almost universally excluded from coverage.
- Inpatient vs. Outpatient Care:
- Inpatient Care: Treatment that requires an overnight stay in a hospital bed. This is the core of most private health insurance policies and is almost always covered.
- Day-patient Care: Treatment that requires a hospital bed for a day but not an overnight stay (e.g., minor surgery, chemotherapy infusion). Usually covered.
- Outpatient Care: Consultations with specialists, diagnostic tests (blood tests, X-rays, MRI scans), and therapies (physiotherapy, psychotherapy) that do not require a hospital bed. Outpatient cover is often an optional add-on or has specific limits. For PVS/Long COVID, significant outpatient cover for diagnostics and specialist consultations is often crucial.
Table 2: Typical Private Health Insurance Coverage Structure
| Category | Description | Relevance to PVS/Long COVID (if eligible) |
|---|---|---|
| Inpatient Cover | Core coverage for overnight hospital stays, surgery, anaesthetics. | May cover acute inpatient rehabilitation or procedures linked to severe PVS/Long COVID complications. |
| Day-patient Cover | Treatment requiring a bed for the day but no overnight stay. | Could cover specific diagnostic procedures or day-case therapies. |
| Outpatient Cover | Consultations, diagnostics (scans, tests), therapy sessions. Often optional or limited. | Crucial for initial diagnosis, specialist consultations (neurology, cardiology, respiratory), and rehabilitation therapies (physio, psychological support). |
| Cancer Cover | Comprehensive cover for cancer diagnosis and treatment. | Unrelated to PVS/Long COVID unless a separate cancer diagnosis exists. |
| Mental Health | May cover psychiatric consultations, therapy (often with limits). | Highly relevant, as anxiety, depression, and PTSD are common PVS/Long COVID comorbidities. |
| Therapies | Physiotherapy, osteopathy, chiropractic, podiatry. Limits apply. | Essential for rehabilitation from fatigue, muscle weakness, pain. |
| Excess | Amount you pay towards a claim before the insurer pays. Higher excess = lower premium. | Applies per claim or per year, impacting out-of-pocket costs. |
| No Claims Discount | Reduces premium if no claims made, similar to car insurance. | Encourages careful use of the policy. |
Underwriting Methods: How Insurers Assess Your Medical History
The way an insurer assesses your medical history determines what conditions might be excluded. This is critical for PVS and Long COVID.
Table 3: Pre-existing Conditions & Underwriting Methods Explained
| Underwriting Method | Description | Impact on PVS/Long COVID |
|---|---|---|
| Full Medical Underwriting (FMU) | You provide a detailed medical history upfront. Insurer reviews and provides specific exclusions before the policy starts. | Most transparent. If you had PVS/Long COVID symptoms before applying, it will be specifically excluded. If no symptoms, and you develop it after inception, there's a chance it might be covered (if considered acute, not chronic). |
| Moratorium Underwriting | No medical questions asked initially. Insurer doesn't cover any condition you've had symptoms, medication, advice, or treatment for in the last 5 years. This exclusion typically lasts for 2 years from policy inception, provided you have no symptoms or treatment for that condition during those 2 years. | Common but complex. If you had PVS/Long COVID symptoms in the 5 years prior, it's excluded for the first 2 years. If symptoms recur within those 2 years, the exclusion resets. This is often problematic for fluctuating conditions like PVS/Long COVID. |
| Continued Medical Exclusions (CME) | You transfer from another insurer, and your new insurer carries over the exclusions from your old policy, provided it was also fully medically underwritten. | Only relevant if you already have PMI with specific exclusions. Not common for new applicants. |
For individuals seeking cover for PVS or Long COVID, the pre-existing condition exclusion is the biggest hurdle. If you experienced symptoms of Long COVID before applying for private health insurance, it will almost certainly be classified as a pre-existing condition and will therefore be excluded from your policy, regardless of the underwriting method. This is a fundamental principle of private health insurance: it covers new, acute conditions, not existing ones.
Private Health Insurance & Post-Viral Syndromes/Long COVID: The Crucial Nuance
Given the general exclusion of pre-existing and chronic conditions, it's vital to understand the scenarios where private health insurance might or might not offer support for PVS or Long COVID.
When Private Health Insurance Will NOT Cover PVS/Long COVID:
- If symptoms began before your policy started: This is the most common scenario. If you developed Long COVID symptoms in March 2020 and took out a policy in January 2021, those symptoms and any related conditions are pre-existing and will be excluded. This applies even if you didn't have a formal diagnosis at the time of application, but simply experienced the symptoms.
- For chronic, long-term management: Even if the initial acute phase of a condition may be covered, private health insurance policies are not designed to cover chronic conditions. Long COVID, by its very definition of lasting more than 12 weeks, often transitions into a chronic state. This means that while initial diagnostic work-up for a new onset of symptoms might be covered, ongoing, long-term management, rehabilitation, or therapies for a condition that has become chronic will typically not be covered. This is a critical distinction.
- Experimental treatments: Policies generally exclude treatments that are not established and evidence-based.
- "Wellness" or "Preventative" treatments: Unless there is a clear, acute medical need, general wellness programmes are excluded.
When Private Health Insurance Might Offer Limited Coverage for PVS/Long COVID (If Eligible):
This is a very specific and limited scenario, largely dependent on timing and policy wording.
- New Onset of Symptoms Post-Policy Inception: If you took out a fully medically underwritten policy before ever contracting COVID-19 (or any other viral infection that might lead to a PVS) and then developed a viral infection leading to PVS/Long COVID after your policy started, and the symptoms represent a new, acute episode of illness, the insurer might cover the initial diagnostic investigations and acute treatment.
- Example: You bought a policy in January 2022 with no prior history of chronic fatigue or post-viral issues. You contract COVID-19 in April 2022 and develop severe new, acute symptoms persisting beyond the normal recovery time. An insurer might cover the initial specialist consultations (e.g., with a respiratory consultant, cardiologist, neurologist) and diagnostic tests (e.g., chest X-ray, ECG, MRI) to determine the cause of these new acute symptoms.
- Acute Flare-ups within a Covered Condition: If, theoretically, you had a policy that did cover a condition, and you then had an acute flare-up requiring specific investigation, that might be considered. However, this is less likely to apply to the typical trajectory of Long COVID, which is often a continuous, fluctuating chronic state.
Key Point: The distinction between an "acute" and "chronic" condition is often determined by the insurer based on medical advice and their policy definitions. For Long COVID, once symptoms persist beyond the initial acute phase and require ongoing management, it typically falls under the "chronic" exclusion. Therefore, private health insurance is generally not a solution for the long-term management of established Long COVID. It's more applicable to the initial diagnostic pathway for new onset of symptoms post-policy if no pre-existing conditions apply.
Table 4: What Private Health Insurance May Cover vs. Will Not Cover for PVS/Long COVID (Assuming Eligibility for Acute Phase)
| What May Be Covered (If New Onset & Acute) | What Will NOT Be Covered (Common Exclusions) |
|---|---|
| Initial specialist consultations (e.g., with a pulmonologist, neurologist, cardiologist) to investigate new, acute symptoms. | Symptoms present before policy inception (pre-existing condition). |
| Diagnostic tests (blood tests, X-rays, MRI scans, ECGs, lung function tests) to diagnose the acute condition. | Long-term, ongoing management of chronic PVS/Long COVID. |
| Acute inpatient care if a severe, acute complication arises and requires hospitalisation. | Experimental or unproven treatments. |
| Short-term, focused therapies (e.g., initial course of physiotherapy) to address acute limitations arising from a new, covered condition. | General wellness programmes or preventative measures. |
| Mental health support (limited sessions) for acute anxiety/depression directly linked to the new, covered illness. | Non-medically necessary treatments. |
| Referrals to specialists for the covered acute condition. | Self-referred treatments without prior GP/consultant referral. |
This underscores the importance of being realistic about the scope of private health insurance. It offers incredible benefits for acute, new conditions, but has strict limitations regarding chronic and pre-existing conditions.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Choosing the Right Private Health Insurance Policy for Londoners
If you're considering private health insurance, whether for potential future acute conditions or other medical needs, here are the crucial factors to consider, particularly in the London context:
Table 5: Key Considerations When Choosing a Policy
| Consideration | Details | Relevance to London & PVS/Long COVID |
|---|---|---|
| Underwriting Method | Full Medical Underwriting (FMU) vs. Moratorium. | Crucial. FMU provides clarity on exclusions upfront. Moratorium can be problematic for fluctuating conditions. |
| Outpatient Limit | Financial limit for outpatient consultations, diagnostics, therapies. | Very important. Long COVID investigations often start with numerous outpatient tests and consultations. Ensure this limit is high enough. |
| Hospital Network | List of private hospitals/clinics you can access. | London specific. Some policies have tiered networks (e.g., "London hospitals" tier is more expensive but offers wider choice). Ensure your preferred hospitals/clinics are included. |
| Excess Level | Amount you pay per claim or per year. | Affects your out-of-pocket expenses. Balance premium savings with potential claim costs. |
| Mental Health Cover | Scope of psychiatric consultations and therapy. | Highly relevant, as mental health impacts are significant in PVS/Long COVID. |
| Therapies Cover | Limits on physiotherapy, osteopathy, etc. | Important for physical rehabilitation and symptom management. |
| Referral Requirements | Most policies require a GP referral. | Standard practice. Ensure your GP is supportive of private referrals. |
| Premium Cost | Varies based on age, location (London is more expensive), chosen cover, and excess. | Compare carefully. Remember lower-cost isn't always best. |
| Policy Wording | Definitions of "acute," "chronic," "pre-existing," and specific exclusions. | Absolutely essential. Read the small print meticulously. |
The London Factor: Higher Costs, More Choice
London's private healthcare market is vibrant but comes at a higher cost. Premiums for health insurance in London are typically higher than in other parts of the UK due to the higher cost of living, operating private hospitals, and the concentration of highly sought-after specialists.
However, this higher cost is often offset by the unparalleled choice of clinics and experts available. When selecting a policy, pay close attention to the "hospital list" or "network" provided by the insurer. Some policies offer a standard nationwide list, while others have a specific "London weighting" that allows access to the most prestigious (and expensive) Central London hospitals. If you specifically want to access clinics on Harley Street or within major private hospital groups in Central London, ensure your policy covers this higher-tier network.
The Application Process and Medical History Disclosure
Applying for private health insurance requires full and honest disclosure of your medical history. This is where the pre-existing condition hurdle becomes most apparent for PVS/Long COVID.
- Initial Enquiry: You'll typically provide basic information (age, postcode, desired level of cover).
- Medical Questionnaire: For fully medically underwritten policies, you'll complete a detailed questionnaire about your past and present health, including any symptoms, diagnoses, medications, or treatments you've received.
- Crucial for PVS/Long COVID: If you have ever experienced symptoms that could be attributed to a post-viral syndrome, or had a diagnosis of Long COVID, ME/CFS, or similar, you must declare it. Failure to disclose can lead to claims being declined and your policy being invalidated.
- Underwriting Decision: The insurer reviews your medical history. They may request further information from your GP (with your consent). Based on this, they will issue terms, which may include:
- Acceptance with no exclusions.
- Acceptance with specific exclusions (e.g., "all conditions related to Long COVID are excluded").
- Loading (an increased premium due to higher risk).
- Decline.
- Policy Inception: Once accepted, your policy begins, and you start paying premiums.
For moratorium policies, the process is simpler initially as no medical questions are asked. However, the exclusions only become clear when you try to make a claim. The insurer will then investigate your medical history to see if the condition you are claiming for falls within the 5-year moratorium period or is deemed chronic. This can be very stressful when you are unwell and trying to access care.
How WeCovr Specialists or Broker Partners Can Help You Navigate This Complex Landscape
Understanding the nuances of private health insurance, especially concerning complex conditions like Post-Viral Syndromes and Long COVID, can be overwhelming. This is precisely where expert guidance becomes invaluable.
WeCovr specialists or broker partners are a modern UK health insurance broker dedicated to helping individuals and families find the right private health insurance coverage tailored to their specific needs. WeCovr, sometimes working with broker partners, works with major insurers in the UK, including Bupa, AXA Health, Vitality, Aviva, WPA, and others.
Our service is completely free to you. We are remunerated by the insurers, so our advice is regulated and focused solely on your interests. A WeCovr specialist or trusted broker partner understands that finding suitable cover requires more than just comparing prices; it demands a deep understanding of policy wordings, underwriting processes, and how these apply to your unique medical history.
How We Help:
- Regulated Advice: We assess your individual circumstances, including your medical history and specific concerns (like PVS/Long COVID), to explain which policies might be suitable and, more importantly, which limitations you might face.
- Comprehensive Comparisons: We provide detailed comparisons of policies from all well-known insurers, highlighting key differences in coverage, outpatient limits, hospital networks, and terms related to chronic/pre-existing conditions.
- Navigating Underwriting: We guide you through the underwriting process, helping you understand the implications of different methods (Full Medical Underwriting vs. Moratorium) and ensuring you provide all necessary information accurately. For conditions like PVS/Long COVID, this is particularly important to manage expectations regarding what can and cannot be covered.
- London-Specific Expertise: We understand the London private healthcare market, including the different hospital networks and their implications for accessing specific clinics.
- Ongoing Support: Our relationship doesn't end once you take out a policy. We're here to answer your questions, assist with policy renewals, and help you understand your coverage throughout the lifetime of your policy.
Navigating the complexities of private health insurance for Post-Viral Syndromes and Long COVID requires a clear understanding of the terms and conditions, especially the exclusions for pre-existing and chronic conditions. While private health insurance is not a panacea for long-term chronic illness, it can offer invaluable access to acute diagnostics and specialist consultations for new conditions if you meet the eligibility criteria.
We believe in empowering you with accurate information so you can make confident choices about your health.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Beyond Insurance: Other Considerations for PVS/Long COVID Recovery
While private health insurance can offer a pathway to quicker diagnosis for new acute conditions, it's important to have a holistic recovery strategy, especially given the limitations concerning chronic care.
- NHS Long COVID Clinics: Even if you explore private options, engage with your NHS GP and discuss referral to an NHS Long COVID clinic. They provide integrated, multidisciplinary care, and although waiting lists can be long, they are specifically designed for this condition.
- Self-Pay Options: For some specific consultations or tests, self-paying might be an option. London has a competitive private healthcare market, and a single consultation or diagnostic test might be manageable without insurance, especially if you have a clear idea of the specialist you need to see.
- Charities and Support Groups: Organisations like Long COVID Support and the ME Association provide invaluable resources, peer support, and information on managing symptoms and navigating healthcare systems.
- Lifestyle Management: Diet, graded exercise (if tolerated), sleep hygiene, stress management, and pacing activities are fundamental to managing PVS and Long COVID symptoms, regardless of medical intervention.
- Workplace Support: If your condition impacts your ability to work, explore support from your employer, including occupational health services, reasonable adjustments, and understanding sick pay policies.
Conclusion
The journey through Post-Viral Syndromes and Long COVID can be incredibly challenging, marked by uncertainty, fluctuating symptoms, and often, a prolonged struggle to access comprehensive care. For Londoners, the appeal of private healthcare – with its promise of quicker access to world-class specialists and advanced diagnostics – is strong.
However, it is crucial to approach private health insurance with a clear and realistic understanding of its scope and, more importantly, its limitations. Private Medical Insurance in the UK is primarily designed to cover new, acute conditions, not those that are pre-existing or chronic. This fundamental principle means that for most individuals experiencing established Post-Viral Syndromes or Long COVID, private health insurance will not cover the long-term management of these conditions if symptoms manifested before the policy began, or if the condition is deemed chronic.
While there might be very specific scenarios where initial acute diagnostic investigations for a new onset of symptoms could be covered (provided you had no related symptoms before the policy started and the condition isn't defined as chronic by the insurer), it is not a solution for ongoing chronic care.
Navigating these complexities requires expertise. A WeCovr specialist or trusted broker partner pride ourselves on providing regulated, clear, and comprehensive advice, helping you understand your options without charge. We compare policies from all major UK insurers, guiding you through the intricacies of underwriting and policy wordings, so you can make informed decisions about your health insurance needs.
Ultimately, managing Post-Viral Syndromes and Long COVID often requires a multifaceted approach, combining medical care (NHS or private where appropriate), lifestyle adjustments, and strong support networks. Private health insurance, when understood correctly, can be a valuable component for specific acute needs, but it's essential to recognise its boundaries and plan your recovery strategy accordingly.
Sources
- NHS England: Waiting times and referral-to-treatment statistics.
- Office for National Statistics (ONS): Health, mortality, and workforce data.
- NICE: Clinical guidance and technology appraisals.
- Care Quality Commission (CQC): Provider quality and inspection reports.
- UK Health Security Agency (UKHSA): Public health surveillance reports.
- Association of British Insurers (ABI): Health and protection market publications.
Important Information and Risks
No advice: This article is for general information only. It is not financial, legal, insurance, or tax advice, and it is not a personal recommendation. WeCovr does not assess your individual circumstances or recommend a specific product through this article.
Policy exclusions and underwriting: Insurance policies, including life insurance, private medical insurance, critical illness cover, and income protection, are subject to insurer underwriting, eligibility, acceptance criteria, terms, conditions, limits, and exclusions. Pre-existing medical conditions may be excluded, restricted, or accepted on special terms unless an insurer confirms otherwise in writing.
Tax treatment: References to tax treatment, HMRC rules, or business reliefs are based on current UK legislation and guidance, which can change. Tax treatment depends on your personal or business circumstances and may differ from examples in this article.
Before you buy: Always read the Insurance Product Information Document (IPID), policy summary, and full policy terms before buying, renewing, changing, or keeping cover. If you are unsure whether a policy is suitable for you, speak to an insurance adviser.
Compare private health insurance quotes from leading UK insurers
Answer a few quick questions and a specialist from WeCovr or one of its broker partners will help you compare cover from insurers such as Bupa, AXA, Aviva and Vitality. No obligation.
Takes about 2-3 minutes
Compare cover from leading UK insurers
No obligation to buy
Get a quote
Get a private health insurance quote
Answer a few questions, then a specialist helps you compare cover and prices.
Tell us who needs cover
Just you, a partner, your family or your staff.
Compare your options
A specialist compares cover and prices from leading UK insurers.
Decide in your own time
There is no obligation to buy.
What you get
A specialist from WeCovr or one of its broker partners
Options compared across leading UK insurers
No obligation to buy