TL;DR
The UK private health insurance market is experiencing its most significant transformation in decades, driven by unprecedented NHS waiting times and a generational shift in healthcare expectations.
Key takeaways
- Illustrative estimate: Individual adult: 87.59
- Illustrative estimate: Couple: 160.49
- Illustrative estimate: Family of four: 183.25
- The UK health cover market has reached a record-breaking 8.51 billion in 2024, representing a remarkable 12.1% year-on-year growth and a 920 million uplift.
- Currently, 4.75 million individuals hold private medical insurance policies, with total coverage extending to 8.15 million people when dependents are included.
The Private Health Insurance Revolution: How Record NHS Pressures Are Transforming Healthcare in the UK in 2026
The UK private health insurance market is experiencing its most significant transformation in decades, driven by unprecedented NHS waiting times and a generational shift in healthcare expectations. With 7.41 million people currently on NHS waiting lists and only 58% of patients receiving treatment within the target 18 weeks, private medical insurance has evolved from a luxury for the affluent to a pragmatic necessity for millions of working families.
Market Surge: £8.51 Billion and Growing
The UK health cover market has reached a record-breaking £8.51 billion in 2024, representing a remarkable 12.1% year-on-year growth and a £920 million uplift. This surge reflects the most robust market performance since the 2008 financial crisis, with private medical insurance alone valued at £6.89 billion. (illustrative estimate)
The statistics paint a compelling picture of changing healthcare dynamics. Currently, 4.75 million individuals hold private medical insurance policies, with total coverage extending to 8.15 million people when dependents are included. This represents 12.0% of the UK population—the highest penetration rate since 2008.
The Big Four Dominance
The private medical insurance landscape is dominated by four major players: Bupa, AXA Health, Aviva, and VitalityHealth, which collectively capture 95% of the market share. This concentration has increased significantly from 88.3% in 2017, indicating market consolidation and the competitive advantages of scale in healthcare provision.
Bupa remains the market leader with its comprehensive hospital network and the well-regarded Blua Health app. AXA Health offers the most modular approach with flexible hospital choices, while Aviva focuses on competitive pricing with its "Healthier Solutions" plan. Vitality distinguishes itself through its integrated wellness programmes and health-tracking technology.
Cost Analysis: What Britons Are Paying in 2026
Private health insurance costs in 2026 reflect both increased demand and medical inflation pressures. According to the more comprehensive analysis available, covering over 12,000 quotes from well-known insurers, the average monthly costs are:
- Illustrative estimate: Individual adult: £87.59
- Illustrative estimate: Couple: £160.49
- Illustrative estimate: Family of four: £183.25
However, these figures mask significant variations based on multiple factors. Age remains the primary cost driver, with 70-year-olds paying roughly five times more than 20-year-olds for equivalent coverage. Geographic location also plays a crucial role, with premiums significantly higher in major cities where private treatment costs are elevated.
Premium Inflation Pressures
The sector faces substantial inflationary pressures, with UK private medical insurance costs expected to increase by 12.8% in 2026—significantly above both global and European averages. Some employers reported premium increases of 10% to 25% on policy renewals in 2026, with exceptional cases exceeding 50%.
This inflation stems from multiple sources: increased claims frequency, rising medical costs, pharmaceutical price inflation, and staffing challenges within the private healthcare sector.
NHS Crisis Driving Private Sector Growth
The private health insurance boom cannot be understood without examining the concurrent NHS crisis. NHS England data reveals that 7.41 million cases were waiting for planned treatment as of May 2026. More critically, waiting times continue to deteriorate, with the median wait extending beyond acceptable levels for many patients.
Regional Variations and Impact
The pressure on NHS services varies significantly across regions. In Scotland, 641,500 individuals were estimated to be on at least one waiting list at March 2026, equivalent to 1 in 9 of Scotland's population. The number of patients waiting over one year has increased by 34.5% compared to March 2026.
These extended waits are not merely inconvenient—they represent a fundamental shift in healthcare accessibility that is driving middle-income families toward private alternatives.
The Employer Revolution: Workplace Benefits Transformation
Four out of five policyholders (3.8 million) are now covered through employer-sponsored schemes, leaving only 880,000 holding individual policies. This employer-driven growth reflects several converging trends:
Business Benefits of Private Medical Insurance
Employers are increasingly recognising private medical insurance as a strategic investment rather than a cost. Key business benefits include:
Enhanced Productivity: Private medical insurance provides employees with prompt access to healthcare, reducing downtime due to illness and stress-related absences.
Improved Recruitment and Retention: With 55% of respondents indicating they would be more likely to apply for jobs offering private medical insurance, it has become a crucial differentiator in competitive talent markets.
Reduced Absence Costs: Faster access to treatment means employees return to work more quickly, reducing both direct sick pay costs and indirect productivity losses.
Tax Advantages: Companies can claim corporation tax relief on premiums as business expenses, while the structured benefit-in-kind taxation provides predictable cost frameworks.
Employee Perspectives
For employees, workplace private medical insurance offers several advantages beyond individual policies. Group schemes typically provide lower premiums due to risk pooling, often include Employee Assistance Programmes not available in personal plans, and may offer additional wellness benefits.
However, employees should understand the tax implications. Private medical insurance provided by employers is classified as a "benefit in kind," resulting in additional income tax calculated on the premium value.
The Generational Shift: Young People Leading Adoption
Perhaps the most surprising trend in private healthcare adoption is the generational shift. Contrary to conventional wisdom, younger people aged 18-24 are the most likely demographic to have used private healthcare services, with 4 in 10 having already accessed private care. (illustrative estimate)
Digital Natives Embrace Healthcare Innovation
This generational shift reflects several factors unique to younger demographics:
Digital Comfort: Young people are more comfortable with digital health services, virtual GP consultations, and app-based healthcare management.
Pragmatic Approach: Rather than ideological attachment to the NHS, younger generations take a pragmatic view of accessing healthcare when needed.
Preventative Mindset: Early adoption of private healthcare often focuses on preventative care, diagnostics, and mental health services.
Family Coverage: Many young people benefit from parental policies that cover dependent children in full-time education.
Virtual GP Services Surge
The demand for virtual GP services has exploded, with some providers witnessing 36% year-on-year increases in consultations. Livi UK reports booking over 5,000 appointments per week—a tenfold increase over four years. This growth spans demographics, with usage patterns showing a 26-45 age range as the highest users and an almost 50-50 split between males and females.
Claims and Utilisation Patterns
The utilisation of private medical insurance reached record levels in 2024. Insurers paid out a record £3.9 billion in claims—equivalent to £10.7 million per day. The number of claims increased by 18% to 1.85 million, with workplace claims driving growth at 22% to 1.45 million. (illustrative estimate)
This high utilisation rate demonstrates that private medical insurance is not merely a "safety net" but an actively used healthcare solution. The claims-to-premium ratio has consistently remained between £80-£89 for every £100 of premium paid since the mid-1950s, indicating sustainable actuarial foundations. (illustrative estimate)
Technology Integration and Digital Health
The private healthcare sector is embracing digital transformation at an unprecedented pace. All major insurers now offer comprehensive digital services:
Virtual GP Access: Potentially same-day consultations through platforms like Bupa's Blua Health app, AXA's Doctor at Hand service, and Aviva's Digital GP platform.
Health Tracking Integration: Vitality's wellness programmes connect with wearable devices to provide personalised health insights and premium discounts.
AI-Enhanced Diagnostics: Private healthcare providers are adopting AI-powered diagnostic tools and treatment optimisation systems ahead of NHS deployment.
Telemedicine Expansion: Beyond consultations, services now include prescription deliveries, specialist referrals, and mental health support.
The UK digital health market is projected to reach £17 billion by 2026, with private insurers at the forefront of adoption and integration. (illustrative estimate)
Mental Health: The Growing Priority
Mental health coverage has evolved from an optional add-on to a core component of modern private medical insurance. The pandemic accelerated awareness of mental health needs, with private mental health insurance policies growing by 20% according to the Association of British Insurers.
Private insurers now offer comprehensive mental health support including:
- AI-powered therapy apps
- Virtual reality treatments
- 24/7 crisis support lines
- Employee assistance programmes
- Preventative mental wellbeing programs
This expansion addresses a critical gap in NHS provision, where mental health waiting times often exceed physical health delays.
Tax Implications and Financial Planning
Understanding the tax treatment of private medical insurance is crucial for both individuals and employers planning coverage strategies.
Personal Policies
Individual private medical insurance policies purchased with post-tax income are generally not subject to additional taxation, except for the 12% Insurance Premium Tax (IPT) incorporated into premiums.
Employer-Sponsored Schemes
Company-provided private medical insurance creates different tax obligations:
For Employers: Premiums are tax-deductible business expenses, providing corporation tax relief.
For Employees: Coverage constitutes a "benefit in kind" subject to income tax at the employee's marginal rate. HMRC typically adjusts tax codes to collect this tax through payroll.
Reporting Requirements: Employers must complete P11D forms annually, detailing benefit values for each employee.
Self-Employed Considerations
Self-employed individuals and company directors face specific considerations:
- Business Purchase: If a limited company purchases coverage, it's tax-deductible as a business expense
- Personal Purchase: Individual policies for business owners typically cannot be claimed as business expenses
- Employee Coverage: Self-employed people can claim tax relief on employee health insurance but not their own personal coverage
Market Outlook and Future Trends
The private health insurance market shows no signs of slowing. Several factors suggest continued robust growth:
Demographic Pressures
The UK's ageing population creates sustained pressure on both NHS capacity and private insurance demand. With demographic projections showing continued population growth in older age groups, the strain on public healthcare will intensify.
Government Policy Direction
The government's 10-Year Health Plan acknowledges the role of private sector capacity in treating NHS patients. This policy direction suggests greater integration between public and private healthcare delivery, potentially expanding the market for private insurance.
Technological Innovation
Continued investment in digital health technologies, AI diagnostics, and personalised medicine will likely maintain private healthcare's competitive advantages in speed and service quality.
Economic Factors
Despite inflationary pressures, the fundamental value proposition of private medical insurance—reduced waiting times, enhanced choice, and improved access—remains compelling for middle and higher-income households.
Challenges and Considerations
The rapid growth of private medical insurance also presents challenges:
Healthcare Workforce Implications
The expansion of private healthcare competes with the NHS for the same pool of medical professionals. This dynamic could exacerbate NHS staffing challenges while potentially offering better career opportunities for healthcare workers.
Equity and Access
The growth of private healthcare raises questions about healthcare equity. While private insurance relieves pressure on NHS services, it also creates a two-tier system where access to timely care increasingly depends on ability to pay.
Regulatory Oversight
The Financial Conduct Authority's Consumer Duty regulations require insurers to demonstrate fair value and good customer outcomes. This regulatory scrutiny will likely intensify as market growth continues.
Capacity Constraints
The private healthcare infrastructure faces its own capacity limitations. Rapid demand growth has led to longer appointment waits even within private services, with some virtual GP providers experiencing quality concerns.
Choosing Private Medical Insurance: A 2026 Guide
For individuals and families considering private medical insurance, several factors warrant careful evaluation:
Coverage Options
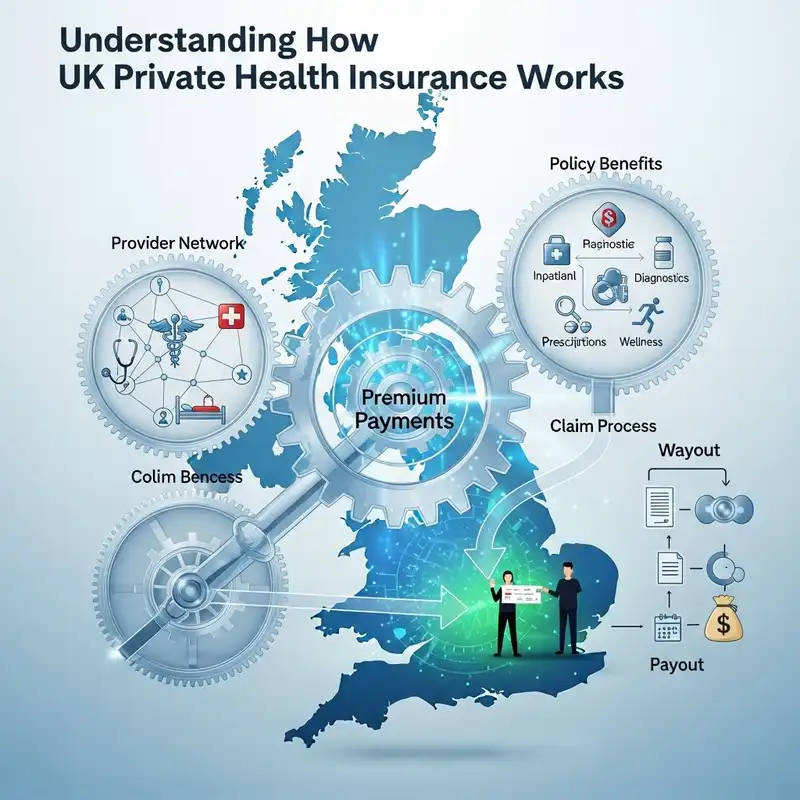
Modern private medical insurance offers modular coverage allowing customisation based on needs and budget:
Core Inpatient Coverage: Hospital treatment, surgery, and accommodation Outpatient Services: Consultant appointments, diagnostics, and specialist treatments Additional Benefits: Physiotherapy, mental health support, and complementary therapies Digital Services: Virtual GP access, health apps, and telemedicine consultations
Provider Selection
When choosing between major insurers, consider:
Network Size: Hospital and consultant availability in your geographic area Digital Services: Quality and accessibility of virtual healthcare offerings Customer Service: Claims processing efficiency and customer support quality Specialised Services: Coverage for specific conditions or treatments relevant to your needs
Cost Management
Several strategies can help manage private medical insurance costs:
Higher Excess: Accepting higher out-of-pocket payments can significantly reduce premiums Geographic Limitations: Restricting coverage to specific regions can lower costs Age-Optimised Purchasing: Starting coverage when younger locks in lower base premiums Employer Schemes: Group coverage through employers typically offers better value than individual policies
Industry Innovation and Partnerships
The private healthcare sector continues to innovate through strategic partnerships and technological integration:
NHS Collaboration
Private providers increasingly work with NHS trusts to provide additional capacity. NHS trusts spent £3.4 billion on contracted private care in 2023/24, up from £1.66 billion in 2019/20. This collaboration suggests a future model where private and public healthcare work complementarily rather than competitively.
Technology Partnerships
Private insurers are forming partnerships with technology companies to enhance service delivery:
- Wearable device integration for real-time health monitoring
- AI-powered triage systems for more efficient care routing
- Blockchain technology for secure health record management
- Genomic testing partnerships for personalised medicine approaches
International Models
UK private insurers are studying successful international models, particularly from countries with mixed public-private systems, to optimise service delivery and cost management.
Economic Impact and Productivity Benefits
The broader economic impact of private medical insurance extends beyond healthcare delivery:
Productivity Gains
Research suggests that private medical insurance contributes to economic productivity through:
- Reduced Sickness Absence: Faster treatment access minimises time off work
- Preventative Care: Early intervention prevents more serious health conditions
- Mental Health Support: Comprehensive mental health coverage supports workforce wellbeing
- Diagnostic Speed: Faster access, where available, to diagnostic services enables earlier treatment
A study by Frontier Economics estimated that helping 25% of people currently out of work due to ill-health back into employment could be worth £48 billion to the UK economy.
Healthcare System Efficiency
Private medical insurance contributes to overall healthcare system efficiency by:
- Reducing NHS Demand: Private treatment reduces pressure on public services
- Innovation Adoption: Private sector often adopts new treatments and technologies first
- Workforce Development: Competition for medical talent drives professional development
- Infrastructure Investment: Private healthcare investment supplements public health infrastructure
Regulatory Environment and Consumer Protection
The regulatory landscape for private medical insurance continues to evolve with enhanced consumer protection measures:
Financial Conduct Authority Oversight
The FCA's Consumer Duty requires insurers to:
- Demonstrate Fair Value: Prove that products provide reasonable value for money
- Ensure Good Outcomes: Monitor and improve customer experiences
- Enhance Transparency: Provide clear information about coverage and limitations
- Support Vulnerable Customers: Implement measures to help customers facing difficulties
Care Quality Commission Standards
Private healthcare providers must meet CQC standards for:
- Safety: Protecting patients from harm and risk
- Effectiveness: Providing evidence-based care and treatment
- Caring: Ensuring staff treat patients with compassion and respect
- Responsiveness: Organising services around patient needs
- Well-led: Leadership that promotes high-quality care
Data Protection Compliance
With increasing digitalisation, private healthcare providers must comply with:
- UK GDPR Requirements: Protecting patient data privacy and security
- Data Sharing Protocols: Managing information sharing between providers
- Cyber Security Standards: Protecting against data breaches and system failures
- Consent Management: Ensuring proper consent for data use and sharing
Future Market Predictions and Strategic Outlook
Looking toward the remainder of 2026 and beyond, several trends are likely to shape the private medical insurance market:
Market Consolidation
While the "big four" already control 95% of the market, further consolidation may occur as smaller providers struggle with regulatory compliance costs and competitive pressures. This could lead to fewer but more comprehensive service offerings.
Integrated Health Ecosystems
The future likely involves more integrated health ecosystems where private insurers, technology companies, and healthcare providers work together to deliver comprehensive care journeys rather than discrete services.
Personalised Healthcare
Advances in genomic medicine, AI diagnostics, and predictive analytics will enable increasingly personalised healthcare approaches, potentially allowing for more precisely priced and targeted insurance products.
Sustainability Focus
Environmental sustainability is becoming increasingly important, with private healthcare providers investing in:
- Green Healthcare Facilities: Environmentally sustainable hospital and clinic designs
- Digital-First Approaches: Reducing travel through virtual consultations
- Sustainable Supply Chains: Environmentally responsible medical supply procurement
- Carbon Neutral Operations: Achieving net-zero carbon footprints
Regional Variations and Local Considerations
The private medical insurance market exhibits significant regional variations that consumers should understand:
London and Southeast England
The highest concentration of private healthcare facilities and the most expensive premiums characterise this region. However, the breadth of choice and shortest waiting times often justify the premium costs for residents.
Northern England and Scotland
Growing markets with increasing private healthcare investment, often offering better value propositions as regional competition increases. NHS pressures in these areas are driving rapid adoption of private alternatives.
Wales and Northern Ireland
Smaller but rapidly growing markets, with significant increases in out-of-pocket spending. Northern Ireland saw private admissions triple between 2020 and 2024, while Wales experienced a 124% increase.
Rural Areas
Limited private healthcare infrastructure in rural areas can create challenges for accessing private services, making comprehensive outpatient coverage and virtual services particularly valuable.
Making the Decision: Is Private Medical Insurance Right for You?
The decision to purchase private medical insurance involves weighing multiple personal and financial factors:
Financial Considerations
- Budget Analysis: Can you afford the premiums without compromising other financial priorities?
- Risk Assessment: What is your personal and family medical history?
- Opportunity Cost: Would the premium money provide better value if invested elsewhere?
- Tax Implications: How will the insurance affect your overall tax situation?
Lifestyle Factors
- Work Requirements: Does your career require reliable health and minimal absence?
- Family Responsibilities: Are you responsible for dependents who need healthcare access?
- Health Anxiety: Would private insurance provide valuable peace of mind?
- Geographic Flexibility: Do you travel frequently or live in areas with limited NHS access?
Health Status
- Current Health: Are you currently healthy enough to obtain coverage at standard rates?
- Pre-existing Conditions: How will existing health issues affect coverage and costs?
- Future Health Needs: What health challenges might you face as you age?
- Preventative Care: Would you benefit from the enhanced screening and preventative services?
Conclusion: The New Healthcare Paradigm
The private medical insurance market in the UK has fundamentally transformed from a luxury service for the wealthy to a pragmatic healthcare solution for middle-income families facing NHS capacity constraints. With 12.0% of the population now covered and the market valued at £8.51 billion, private medical insurance has become an integral component of the UK healthcare ecosystem.
The convergence of several powerful forces—NHS waiting list pressures, demographic changes, technological innovation, and generational shifts in healthcare expectations—has created sustained demand for private healthcare alternatives. The 40% of young people aged 18-24 who have used private healthcare represent not just a statistical anomaly but a fundamental shift in how Britons approach healthcare access and planning.
For employers, private medical insurance has evolved into a strategic tool for talent attraction, retention, and productivity enhancement. The £3.9 billion in annual claims payouts demonstrates that this is not merely insurance but an actively utilised healthcare system supporting millions of working families.
The digital transformation of private healthcare, from virtual GP services to AI-enhanced diagnostics, positions the sector at the forefront of healthcare innovation. With virtual consultations growing by 36% and comprehensive digital health platforms becoming standard, private medical insurance increasingly offers not just alternative access but superior technological capabilities.
However, this growth occurs within a broader context of healthcare system strain and social equity considerations. The expansion of private healthcare provides valuable pressure relief for the NHS while raising important questions about healthcare equity and long-term sustainability.
Looking ahead, the private medical insurance market appears positioned for continued growth, driven by demographic pressures, technological advancement, and evolving consumer expectations. The challenge for policymakers, healthcare providers, and insurers will be ensuring that this growth contributes to overall healthcare system improvement rather than exacerbating existing inequalities.
For individuals and families considering private medical insurance in 2026, the value proposition has never been stronger. With average monthly costs of £87.59 for individuals and comprehensive coverage including digital health services, mental health support, and faster access, where available, to specialist care, private medical insurance offers tangible benefits that justify the investment for many households.
The transformation of UK healthcare is accelerating, and private medical insurance stands at the centre of this evolution. Whether viewed as a necessary response to NHS challenges or an investment in superior healthcare access, private medical insurance has established itself as a permanent and growing component of British healthcare—one that will continue shaping how families access, experience, and plan for their healthcare needs in an increasingly complex medical landscape.
The statistics tell a compelling story: record market growth, unprecedented adoption rates, and sustained utilisation across all demographics. For 2026 and beyond, private medical insurance represents not just a healthcare option but a strategic approach to ensuring healthcare security in an era of unprecedented demand and technological transformation.
-
nuffieldtrust.org.uk/qualitywatch/nhs-performance-dashboard
-
laingbuisson.com/press-releases/the-uk-health-cover-market-surges-by-825-million-in-a-year-to-reach-7-59-billion-as-individuals-and-businesses-flock-to-health-and-dental-cover-options/
-
lowdownnhs.info/topics/access/employers-drive-rise-in-health-insurance/
-
publichealthscotland.scot/publications/nhs-waiting-times-stage-of-treatment/stage-of-treatment-waiting-times-inpatients-day-cases-and-new-outpatients-quarter-ending-31-march-2026/
-
hawsons.co.uk/benefits-of-private-medical-insurance/
-
ihpn.org.uk/news/new-research-shows-going-private-is-becoming-the-new-normal/
-
vitality.co.uk/business/workplace-insights/how-does-company-health-insurance-work/
-
ihpn.org.uk/news/new-research-shows-nhs-challenges-driving-demand-for-private-healthcare-particularly-among-younger-people/
-
ihpn.org.uk/younger-people-are-more-likely-to-have-used-private-healthcare/
-
healthcareandprotection.com/how-insurers-are-meeting-capacity-concerns-amid-surging-demand-for-virtual-gp-services-analysis/
-
abi.org.uk/news/news-articles/2024/112/private-medical-insurance-data-2023/
-
pmc.ncbi.nlm.nih.gov/articles/PMC1118448/
-
seemegp.doctor/health-trends-of-2026-a-look-ahead/
-
mercer.com/en-gb/insights/employee-health-and-benefits/health-and-wellbeing/changing-landscape-of-virtual-gp-services/
-
twobirds.com/-/media/new-website-content/pdfs/capabilities/life-sciences-and-healthcare/iclg-digital-health-2026_chapter-24_united-kingdom-(1).pdf
-
persistencemarketresearch.com/market-research/uk-private-healthcare-market.asp
-
axahealth.co.uk/small-business/guidance-for-employers/pricing-and-tax/health-insurance-deductible-tax/
-
vitality.co.uk/health-insurance/guides/health-insurance-for-self-employed/
-
gov.uk/government/publications/10-year-health-plan-for-england-fit-for-the-future/fit-for-the-future-10-year-health-plan-for-england-executive-summary
-
wecovr.com/guides/private-health-insurance-uk-outlook/
-
nuffieldtrust.org.uk/news-item/how-has-the-role-of-the-private-sector-changed-in-uk-health-care
-
frontier-economics.com/uk/en/news-and-insights/news/news-article-i21603-unlocking-the-246bn-prize-through-health-innovation/
-
actuarialpost.co.uk/article/over-7m-take-out-private-medical-insurance-as-nhs-lists-grow-25007.htm
-
bbc.co.uk/news/articles/cedg8dz7996o
-
england.nhs.uk/2026/06/nhs-waiting-list-hits-two-year-low-as-staff-work-to-turn-the-tide/
-
statista.com/outlook/fmo/insurances/non-life-insurances/health-insurance/united-kingdom
-
medefer.com/private-health-insurance-in-the-uk-changing-role-in-society/
-
wecovr.com/guides/uk-2026-shock-new-data-reveals-over-1-in-3-42/
-
aon.com/unitedkingdom/media-room/articles/aon-uk-in-unprecedented-era-private-medical-cover
-
bma.org.uk/advice-and-support/nhs-delivery-and-workforce/pressures/nhs-backlog-data-analysis
-
wecovr.com/guides/uk-2026-shock-new-data-reveals-over-1-in-5-20/
-
laingbuissonevents.com/wp-content/uploads/2022/06/Health-Cover-Report-Webinar-Holding-Slides_Shared.pdf
-
fullfact.org/health/nhs-waiting-lists-pre-election-briefing/
-
phin.org.uk/news/phin-private-market-update-june-2026-united-kingdom
-
nhs.uk/nhs-services/hospitals/guide-to-nhs-waiting-times-in-england/
-
mordorintelligence.com/industry-reports/united-kingdom-health-and-medical-insurance-market
-
statista.com/statistics/304458/leading-private-health-insurance-companies-in-the-uk-by-number-of-users/
-
obr.uk/box/trends-in-public-and-private-health-spending/
-
statista.com/statistics/317868/private-healthcare-expenditure-in-the-united-kingdom-by-sector/
-
assets.kingsfund.org.uk/f/256914/x/5e4aed4284/independent_health_care_and_nhs_2023.pdf
-
wecovr.com/guides/comparison-of-private-medical-insurance-policies/
-
defaqto.com/star-ratings/medical-insurance
-
ons.gov.uk/peoplepopulationandcommunity/healthandsocialcare/healthcaresystem/bulletins/ukhealthaccounts/2022and2023
-
which.co.uk/money/insurance/health-insurance/get-the-best-private-health-insurance-a2BPc9a7R62E
-
wecovr.com/guides/uk-2026-shock-new-data-reveals-over-1-in-3-75/
-
axahealth.co.uk/small-business/hub/what-is-private-health-insurance-for-employees/
-
gov.uk/tax-company-benefits/other-company-benefits-youll-pay-tax-on
-
community.hmrc.gov.uk/customerforums/sa/402721c3-b98a-ee11-a81c-000d3a86dfe6
-
weforum.org/stories/2023/11/what-is-the-future-of-health-insurance-for-young-people/
-
eversheds-sutherland.com/en/switzerland/insights/telemedicine-the-increasing-prevalence-of-digital-consultations
-
pwc.co.uk/press-room/press-releases/younger-people-twice-as-likely-to-access-private-healthcare--wit.html
-
signifyresearch.net/insights/rewired-2026-highlights-whats-next-for-nhs-digital-health/
-
digitalhealthrewired.com/programme-2026/
-
pmc.ncbi.nlm.nih.gov/articles/PMC10783830/
-
uk.finance.yahoo.com/news/uk-private-health-insurance-surge-nhs-care-060054423.html
-
esign.co.uk/resources/news-and-insights/top-7-healthcare-tech-trends-2026/
-
nuffieldtrust.org.uk/sites/default/files/2020-12/QWAS/digital-and-remote-care-in-covid-19.html
-
england.nhs.uk/digitaltechnology/
-
assets.publishing.service.gov.uk/media/6154681fd3bf7f55fc098c88/Appendix_3_A_review_of_the_evidence_relating_to_the_effectiveness_of_technology_and_online_service_use_in_improving_access_to_general_practice__2___3_.pdf
-
phin.org.uk/press-releases/are-younger-people-paying-more-attention-to-their-health
-
england.nhs.uk/statistics/statistical-work-areas/virtual-ward/
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Sources
- NHS England: Waiting times and referral-to-treatment statistics.
- Office for National Statistics (ONS): Health, mortality, and workforce data.
- NICE: Clinical guidance and technology appraisals.
- Care Quality Commission (CQC): Provider quality and inspection reports.
- UK Health Security Agency (UKHSA): Public health surveillance reports.
- Association of British Insurers (ABI): Health and protection market publications.
Important Information and Risks
No advice: This article is for general information only. It is not financial, legal, insurance, or tax advice, and it is not a personal recommendation. WeCovr does not assess your individual circumstances or recommend a specific product through this article.
Policy exclusions and underwriting: Insurance policies, including life insurance, private medical insurance, critical illness cover, and income protection, are subject to insurer underwriting, eligibility, acceptance criteria, terms, conditions, limits, and exclusions. Pre-existing medical conditions may be excluded, restricted, or accepted on special terms unless an insurer confirms otherwise in writing.
Tax treatment: References to tax treatment, HMRC rules, or business reliefs are based on current UK legislation and guidance, which can change. Tax treatment depends on your personal or business circumstances and may differ from examples in this article.
Before you buy: Always read the Insurance Product Information Document (IPID), policy summary, and full policy terms before buying, renewing, changing, or keeping cover. If you are unsure whether a policy is suitable for you, speak to an insurance adviser.
Start with your Protection Score, then decide whether private health cover is the right fit
Check where health access sits in your overall protection picture before deciding whether to compare private health cover.
Spot whether NHS access risk is the real issue
See if PMI is the gap to fix first
Get health insurance help only if it makes sense for you
Get your score
Start with your protection score
Check your current position first, then get health insurance help if you need it.
Check your current resilience
Score your income, health access and family protection position in a few minutes.
See where private cover helps
Understand whether faster diagnosis and treatment is a priority gap.
Continue to tailored PMI help
If health access is the issue, continue to tailored PMI help.
What you get
A quick view of your current protection position
A clearer idea of where the biggest gaps may be
A direct route to tailored help if you want it