TL;DR
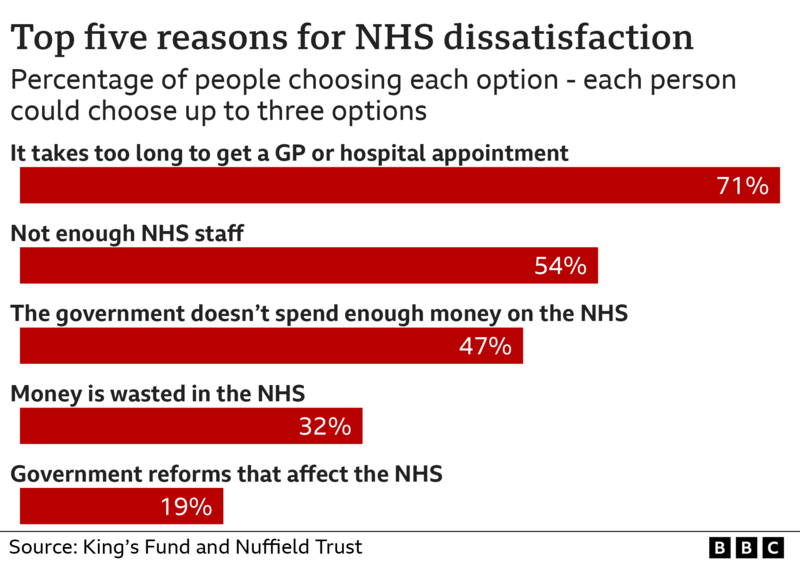
The National Health Service (NHS) remains the bedrock of healthcare in the United Kingdom, cherished by millions for its founding principle of being free at the point of use. However, persistent challenges, exacerbated by the COVID-19 pandemic, have led to unprecedented waiting lists for a wide array of treatments and diagnostics. For many, the prospect of prolonged waiting times for crucial medical attention is a source of significant anxiety, prompting a growing number of individuals to consider alternative pathways for care.
Key takeaways
- Speed: As highlighted, speed is the paramount benefit, getting you diagnosed and treated much faster.
- Choice: You have a choice of consultants (often able to research their specialisms and patient reviews) and private hospitals. This can be empowering, allowing you to feel more in control of your care.
- Comfort and Privacy: Private hospitals typically offer private rooms with en-suite facilities, higher staff-to-patient ratios, and a generally calmer environment, contributing to a more comfortable recovery.
- Flexible Scheduling: Private appointments and procedures often offer greater flexibility, fitting around your work or family commitments.
- Second Opinions: PMI can facilitate obtaining a second opinion if you wish, providing added peace of mind.
A Specialty-by-Specialty Comparison of UK NHS Waiting Times and Private Health Insurance Access
UK Private Health Insurance NHS Waiting Times vs. Private Access – A Specialty-by-Specialty Comparison
The National Health Service (NHS) remains the bedrock of healthcare in the United Kingdom, cherished by millions for its founding principle of being free at the point of use. However, persistent challenges, exacerbated by the COVID-19 pandemic, have led to unprecedented waiting lists for a wide array of treatments and diagnostics. For many, the prospect of prolonged waiting times for crucial medical attention is a source of significant anxiety, prompting a growing number of individuals to consider alternative pathways for care.
This is where private medical insurance (PMI) steps in. While it doesn't replace the NHS, PMI offers a complementary solution, providing access to private healthcare facilities and specialists, often with significantly reduced waiting times. This comprehensive guide aims to demystify the complex interplay between NHS waiting lists and private healthcare access, offering a detailed, specialty-by-specialty comparison to help you understand where private medical insurance can make a tangible difference.
It's crucial to establish a fundamental truth from the outset: standard UK private medical insurance is designed to cover acute conditions that arise after your policy begins. It explicitly does not cover chronic or pre-existing conditions. Understanding this distinction is vital when considering the value and scope of PMI. An acute condition is generally one that responds quickly to treatment, allowing you to return to your normal state of health. A chronic condition, conversely, is a long-term illness that requires ongoing management and may have no cure. This guide will focus on how PMI can facilitate faster access to diagnostics and treatment for the acute conditions it is designed to cover.
The UK Healthcare Landscape: NHS vs. Private
To truly appreciate the value proposition of private health insurance, it's essential to understand the unique characteristics and current pressures facing both the NHS and the private healthcare sector in the UK.
The NHS: Cornerstone of UK Healthcare
The National Health Service, established in 1948, operates on the principle that healthcare should be accessible to all, regardless of their ability to pay. It is funded primarily through general taxation and provides a comprehensive range of services, from GP consultations and emergency care to complex surgeries and long-term care. The NHS's dedication and the tireless efforts of its staff are undeniable.
However, the NHS faces significant, ongoing challenges. Demand for services consistently outstrips capacity, driven by factors such as an ageing population with complex health needs, advancements in medical technology, and the enduring impact of underfunding and staffing shortages. The consequence of these pressures is increasingly visible in the form of growing waiting lists for elective procedures, diagnostic tests, and specialist consultations.
According to NHS England data, the total number of people waiting for routine hospital treatment reached 7.54 million distinct pathways at the end of May 2024. While this represents a slight dip from previous peaks, it remains astronomically high. The NHS Constitution's target for patients to start treatment within 18 weeks of referral continues to be missed for a substantial proportion of patients. In May 2024, only 56.9% of patients on an RTT pathway had been waiting less than 18 weeks. A staggering 309,300 patients had been waiting for over a year (52 weeks), with 42,670 waiting over 18 months (78 weeks), and 9,100 waiting over 2 years (104 weeks). These figures underscore the scale of the challenge and the prolonged uncertainty faced by millions of individuals awaiting care.
The Role of Private Medical Insurance
Private medical insurance (PMI), also known as private health insurance, offers an alternative route to medical care, running parallel to the NHS. It allows individuals to reduce waiting times compared with NHS lists (subject to policy terms) for eligible conditions by paying a monthly or annual premium. When you have PMI, you typically get access to private hospitals, a wider choice of consultants, and often more flexible appointment times.
The core function of PMI is to cover the costs of diagnosis and treatment for acute conditions that develop after the policy is taken out. This is a critical distinction:
- Acute Condition: A disease, illness, or injury that is likely to respond quickly to treatment and return you to the state of health you were in before it began. Examples include a hernia requiring surgery, a sudden onset of joint pain needing investigation, or an appendectomy.
- Chronic Condition: A disease, illness, or injury that has one or more of the following characteristics: it needs ongoing care or management, is permanent, comes back repeatedly, or is incurable. Examples include diabetes, asthma, arthritis, high blood pressure, or multiple sclerosis.
Standard private medical insurance policies in the UK categorically do not cover chronic conditions or pre-existing conditions (those you had symptoms of, or were diagnosed with, before taking out the policy). Its primary purpose is to provide swift access to private medical care for new, short-term health issues that respond well to treatment.
The benefits of private access include:
- Reduced Waiting Times: Often the primary driver for purchasing PMI, offering significantly faster access to consultations, diagnostics (like MRI scans), and surgical procedures.
- Choice of Consultant and Hospital: You can often choose your specialist and the private hospital where you receive treatment, allowing you to select based on expertise or location.
- Private Rooms: During inpatient stays, you typically have a private room with en-suite facilities, offering greater comfort and privacy.
- Flexible Appointments: More control over when your appointments are scheduled.
- Access to Specific Treatments/Drugs: Some policies may offer access to a broader range of approved drugs or treatments not yet widely available on the NHS.
Understanding NHS Waiting Times
Navigating the NHS waiting list system can be complex. Understanding how it operates and where the current bottlenecks are is key to appreciating the role of private healthcare.
How NHS Waiting Lists Work
When your GP refers you to a specialist for a condition that isn't an emergency, you enter the "Referral to Treatment" (RTT) pathway. The NHS Constitution sets a target that 92% of patients on an RTT pathway should start treatment within 18 weeks of referral. This target covers the entire journey from referral to the start of treatment, including diagnostics, consultations, and any necessary procedures.
However, a referral from your GP doesn't immediately put you on a treatment list. First, you await an outpatient appointment with a specialist. This initial consultation often involves further diagnostic tests. Only after diagnosis and a treatment plan is established do you join a waiting list for a procedure if one is required. Each stage of this process can have its own waiting time.
Current State of NHS Waiting Lists
The NHS backlog reached its peak in April 2024 with 7.54 million elective care pathways, involving approximately 6.29 million unique patients. While the number of 18-month and 2-year waits has significantly decreased from their post-pandemic highs, the overall volume remains immense.
Here's a snapshot of the general waiting time situation (as of May 2024, NHS England):
| Metric | Value | Significance |
|---|---|---|
| Total pathways waiting for treatment | 7.54 million | Record high, representing the significant backlog in elective care. |
| Patients waiting less than 18 weeks | 56.9% | Far short of the 92% target, indicating widespread delays for over half of patients. |
| Patients waiting over 1 year (52 weeks) | 309,300 | While declining, still a substantial number facing prolonged waits for essential care. |
| Patients waiting over 18 months | 42,670 | Significant improvement from peak but still indicative of severe delays for some complex cases. |
| Patients waiting over 2 years | 9,100 | Greatly reduced from peak of 26,000+ in 2022, but still unacceptable for patients. |
| Median Waiting Time (all pathways) | 15.6 weeks | Average time from referral to treatment; however, this is an average, and many wait much longer. |
| Patients waiting for diagnostics | 2.89 million | Waiting for critical tests like MRI, CT scans, endoscopies, often a prerequisite for joining a treatment waiting list. |
Source: NHS England, Referral to Treatment Waiting Times, May 2024
The impact of the COVID-19 pandemic on these figures cannot be overstated. Elective surgeries were paused or scaled back, resources were diverted to critical care, and staff burnout became a major issue. While the NHS is working diligently to recover, the sheer volume of deferred care means that waiting lists are likely to remain elevated for the foreseeable future.
Geographical variations also exist, with some NHS trusts performing better than others depending on local demand, staffing levels, and infrastructure. This means that a waiting time for a specific procedure could differ significantly between regions.
The Private Health Insurance Pathway
The pathway to treatment through private medical insurance is designed to be much swifter than the NHS RTT process, cutting down on many of the waiting periods.
Referral to Treatment with PMI
- GP Referral: Even with PMI, you'll almost always need a referral from a GP. This can be your NHS GP or a private GP. The GP writes a referral letter to a private specialist.
- Initial Consultation: Once referred, you can typically secure an appointment with a private consultant within days or a few weeks, significantly faster than the NHS outpatient wait.
- Diagnostics: If diagnostic tests (e.g., MRI, CT scan, X-ray, blood tests) are needed, these can often be scheduled within a few days. The results are usually processed rapidly, and a follow-up consultation booked quickly.
- Diagnosis and Treatment Plan: Following diagnostics, the consultant provides a diagnosis and outlines the proposed treatment plan.
- Treatment/Surgery: If surgery or a procedure is required, it can often be scheduled at your convenience, sometimes within a couple of weeks, depending on the procedure and hospital availability.
This streamlined process dramatically reduces the time from initial symptoms to definitive treatment, alleviating stress and potentially preventing a condition from worsening.
Benefits of Private Access
- Speed: As highlighted, speed is the paramount benefit, getting you diagnosed and treated much faster.
- Choice: You have a choice of consultants (often able to research their specialisms and patient reviews) and private hospitals. This can be empowering, allowing you to feel more in control of your care.
- Comfort and Privacy: Private hospitals typically offer private rooms with en-suite facilities, higher staff-to-patient ratios, and a generally calmer environment, contributing to a more comfortable recovery.
- Flexible Scheduling: Private appointments and procedures often offer greater flexibility, fitting around your work or family commitments.
- Second Opinions: PMI can facilitate obtaining a second opinion if you wish, providing added peace of mind.
Limitations and Exclusions
While the benefits are compelling, it is crucial to understand the limitations and exclusions of standard private medical insurance policies. As previously stated, and it bears repeating for absolute clarity:
- Pre-existing Conditions: Standard PMI policies do not cover conditions that you had signs or symptoms of, or were diagnosed with, before taking out the policy. This is a universal exclusion across the vast majority of UK PMI plans. There are some specialist policies or underwriting options (like 'Medical History Disregarded') usually for corporate schemes, that might offer some cover for pre-existing conditions, but these are rare for individual policies and come with significantly higher premiums. For the purpose of standard individual PMI, assume they are excluded.
- Chronic Conditions: Diseases or illnesses that are long-term, ongoing, or recurring, such as diabetes, asthma, arthritis (once diagnosed as chronic), high blood pressure, multiple sclerosis, or many mental health conditions, are not covered. PMI is designed for acute, short-term illnesses that can be treated and resolved.
- Emergency Services: Life-threatening emergencies (e.g., heart attack, stroke, major trauma) should always be handled by the NHS A&E department. PMI does not cover emergency treatment.
- Normal Pregnancy and Childbirth: While some policies may cover complications arising during pregnancy, routine maternity care is generally not covered.
- Cosmetic Surgery: Procedures purely for aesthetic reasons are typically excluded.
- Drug and Alcohol Abuse: Treatment for addiction is usually not covered.
- Organ Transplants: Generally excluded.
- HIV/AIDS and related conditions.
- Self-inflicted Injuries.
It is vital to read the policy terms and conditions carefully to understand exactly what is covered and what is not. When you compare policies with a WeCovr specialist or one of our broker partners, we ensure you understand these critical distinctions.
Specialty-by-Specialty Comparison: NHS Waiting Times vs. Private Access
This section provides a detailed look at how NHS waiting times compare to private access for some of the most commonly sought-after medical specialties. The figures provided are illustrative and based on recent trends, noting that NHS waiting times can fluctuate significantly by region and specific trust. Private access times are typically consistent across private providers.
Orthopaedics
Orthopaedics deals with conditions affecting the musculoskeletal system, including bones, joints, ligaments, tendons, and muscles. Common procedures include joint replacements, spinal surgery, and treatment for sports injuries.
- Common Conditions: Osteoarthritis (hip/knee pain), slipped discs, rotator cuff tears, carpal tunnel syndrome, fractures (after initial emergency care).
- NHS Waiting Times: Orthopaedic surgery, particularly hip and knee replacements, has some of the longest waiting lists on the NHS. Delays for initial consultations can stretch to several months, followed by further waits for diagnostics (MRI scans can have 6-12 week waits) and then the surgery itself.
- Recent NHS data indicates median waits for trauma and orthopaedics can be 25-30 weeks for treatment, with many waiting over a year for joint replacements.
- Private Access:
- Consultation: 1-2 weeks
- Diagnostics (MRI/X-ray): A few days to 1 week
- Surgery (e.g., knee arthroscopy, hip replacement): 2-6 weeks after diagnosis and decision for surgery.
- Impact of PMI: Significant for pain relief and mobility improvement. Early intervention can prevent conditions from worsening.
Ophthalmology
This specialty focuses on eye health, covering conditions from common vision problems to complex eye diseases and surgeries.
- Common Conditions: Cataracts, glaucoma, retinal detachment, age-related macular degeneration (ARMD), squint.
- NHS Waiting Times: Cataract surgery is one of the most frequently performed procedures globally, and it often has substantial waiting lists on the NHS. Delays for initial assessments and follow-up appointments for conditions like glaucoma are also common.
- NHS median waits for ophthalmology can be 20-25 weeks, with some cataract patients waiting 6-12 months or more.
- Private Access:
- Consultation: 1-2 weeks
- Diagnostics: A few days to 1 week
- Cataract Surgery: 2-4 weeks after diagnosis.
- Impact of PMI: Crucial for preserving vision and improving quality of life, especially for conditions like cataracts where vision progressively deteriorates.
Dermatology
Dermatology deals with conditions of the skin, hair, and nails.
- Common Conditions: Skin cancer (melanoma, basal cell carcinoma), severe acne, eczema, psoriasis, rashes, moles requiring assessment.
- NHS Waiting Times: Referrals for non-urgent dermatology can be notoriously long, stretching to many months for an initial consultation, even for concerning moles (though suspected urgent cancers are fast-tracked, initial suspicion can take time). Biopsies and minor procedures also face waits.
- NHS median waits for dermatology can be 18-20 weeks for initial consultation, with some waiting 6 months or more.
- Private Access:
- Consultation: 1-2 weeks
- Biopsy/Minor Procedure: 1-3 weeks after consultation.
- Impact of PMI: Very beneficial for rapid assessment of suspicious moles, early diagnosis of skin cancers, and prompt management of chronic skin conditions (though treatment for the chronic condition itself isn't covered, quick diagnosis for an acute flare-up might be).
Cardiology
Cardiology focuses on the diagnosis and treatment of heart conditions.
- Common Conditions: Angina, arrhythmias (e.g., atrial fibrillation), heart failure investigation, valve disorders, post-heart attack follow-up (for acute complications).
- NHS Waiting Times: While emergencies are treated immediately, elective cardiac investigations and procedures can have significant waits. Diagnostics like echocardiograms and stress tests often have queues.
- NHS median waits for cardiology can be 18-22 weeks for initial outpatient appointment, with waits for procedures like angioplasty potentially longer.
- Private Access:
- Consultation: 1-2 weeks
- Diagnostics (ECG, Echo, Stress Test, MRI): A few days to 1 week
- Procedures (e.g., angioplasty, pacemaker fitting): 2-6 weeks after diagnosis.
- Impact of PMI: Timely diagnosis and intervention for heart conditions can be life-saving and prevent deterioration.
Gastroenterology
Gastroenterology deals with disorders of the digestive system.
- Common Conditions: Irritable Bowel Syndrome (IBS) investigation, Crohn's disease/ulcerative colitis diagnosis, acid reflux, gallstones, polyps, investigation of unexplained abdominal pain, endoscopy, colonoscopy.
- NHS Waiting Times: Endoscopy and colonoscopy are critical diagnostic tools but often have long waiting lists. Initial consultations for persistent digestive issues can also involve substantial delays.
- NHS median waits for gastroenterology can be 18-22 weeks, with diagnostic procedures often requiring an additional 6-12 week wait.
- Private Access:
- Consultation: 1-2 weeks
- Endoscopy/Colonoscopy: 1-3 weeks after consultation.
- Impact of PMI: Expedited diagnosis can be crucial for conditions like inflammatory bowel disease or early detection of bowel cancers.
Urology
Urology focuses on the urinary tract and male reproductive organs.
- Common Conditions: Kidney stones, benign prostatic hyperplasia (BPH), bladder problems, urinary tract infections (recurrent/complex), investigation of blood in urine.
- NHS Waiting Times: Waiting times for urology consultations and minor procedures can be lengthy. Diagnostics like cystoscopy or prostate biopsies often have queues.
- NHS median waits for urology can be 16-20 weeks for initial consultation, with procedures like lithotripsy or prostate biopsies adding further waits.
- Private Access:
- Consultation: 1-2 weeks
- Diagnostics/Minor Procedures: 1-3 weeks after consultation.
- Impact of PMI: Faster diagnosis and treatment for often painful or disruptive conditions, and crucial for early detection of cancers like prostate or bladder cancer.
ENT (Ear, Nose, Throat)
Otolaryngology, commonly known as ENT, covers conditions of the ear, nose, throat, and related structures of the head and neck.
- Common Conditions: Chronic sinusitis, tonsillitis, hearing loss, dizziness (vertigo), lumps in the neck, voice problems.
- NHS Waiting Times: Referrals for non-urgent ENT conditions, especially for hearing issues or chronic infections, can involve long waits for specialist appointments and subsequent procedures like tonsillectomies or minor ear surgeries.
- NHS median waits for ENT can be 18-22 weeks, with minor surgeries potentially adding months.
- Private Access:
- Consultation: 1-2 weeks
- Diagnostics (e.g., audiology tests, nasal endoscopy): A few days to 1 week
- Minor Procedures (e.g., tonsillectomy, grommets): 2-4 weeks after decision for surgery.
- Impact of PMI: Can significantly improve quality of life for those suffering from chronic ENT issues, and accelerate diagnosis for more serious conditions.
Neurology
Neurology deals with disorders of the nervous system, including the brain, spinal cord, and nerves.
- Common Conditions: Headaches/migraines (investigation of new onset/severe), epilepsy diagnosis, peripheral neuropathy, suspected Multiple Sclerosis (MS) diagnosis, tremors.
- NHS Waiting Times: Neurology is often a bottleneck in the NHS due to the complexity of conditions and the need for highly specialised diagnostics and consultants. Initial consultations and access to imaging like MRI of the brain/spine can involve very long waits.
- NHS median waits for neurology can be 25-30 weeks for initial consultation, with critical diagnostics sometimes adding further months.
- Private Access:
- Consultation: 1-3 weeks
- Diagnostics (MRI, nerve conduction studies, EEG): A few days to 2 weeks
- Impact of PMI: Crucial for early diagnosis of neurological conditions where prompt treatment can impact disease progression or symptom management.
Mental Health
While standard PMI does not cover chronic mental health conditions, many policies now offer some level of acute mental health support, typically for short-term talking therapies or psychiatric assessment for acute conditions like sudden onset anxiety or depression, or crisis intervention.
- Common Conditions (Acute, covered by PMI): Short-term anxiety, depression, stress-related conditions that respond to brief therapy.
- NHS Waiting Times: NHS waiting lists for talking therapies (e.g., CBT, counselling) can be extremely long, often several months, and access to a psychiatrist can be even longer unless it's an emergency.
- NHS waits for IAPT (Improving Access to Psychological Therapies) services can range from a few weeks to several months for first appointment, and longer for follow-up sessions.
- Private Access:
- Therapy (e.g., CBT, counselling): Often direct access within 1-2 weeks (limits apply on number of sessions).
- Psychiatric Assessment: 2-4 weeks.
- Impact of PMI: Can provide timely access to support for acute mental health challenges, preventing conditions from escalating. Note: This coverage varies significantly by policy, often with a capped number of sessions or requiring a GP referral.
General Surgery (e.g., Hernia, Gallbladder)
Covers a range of common elective surgeries.
- Common Conditions: Hernias (inguinal, umbilical), gallstones (cholecystectomy), haemorrhoids, varicose veins.
- NHS Waiting Times: These common procedures, while elective, contribute significantly to the overall NHS backlog. Waits for initial assessment and then the surgery itself can be substantial.
- NHS median waits for general surgery can be 18-20 weeks, with actual surgery dates often several months after that.
- Private Access:
- Consultation: 1-2 weeks
- Surgery: 2-4 weeks after decision for surgery.
- Impact of PMI: Allows patients to address common, often painful conditions quickly, getting them back to normal life sooner.
Here is a consolidated table illustrating the typical waiting time differences between the NHS and private healthcare for selected specialties. These are approximate ranges and can vary.
| Specialty | Typical NHS Waiting Time (Referral to Treatment/Surgery) | Typical Private Access Time (Referral to Treatment/Surgery) | Key Benefit of Private Access |
|---|---|---|---|
| Orthopaedics | 25-52+ weeks (e.g., Joint Replacement) | 3-8 weeks | Rapid pain relief, improved mobility, and quality of life. Avoids prolonged suffering. |
| Ophthalmology | 20-52+ weeks (e.g., Cataract Surgery) | 3-6 weeks | Preserve or restore vision quickly, preventing further deterioration and improving daily function. |
| Dermatology | 18-26+ weeks (Initial Consult) | 1-3 weeks | Fast assessment of concerning moles/rashes, early diagnosis of skin cancers, prompt management of severe skin conditions. |
| Cardiology | 18-30+ weeks (Diagnostics to Procedure) | 2-8 weeks | Timely diagnosis of heart conditions, potentially life-saving interventions, better management of cardiac health. |
| Gastroenterology | 18-36+ weeks (Endoscopy/Colonoscopy) | 2-5 weeks | Quick investigation of digestive issues, early detection of serious conditions like bowel cancer or IBD. |
| Urology | 16-26+ weeks (Initial Consult to Procedure) | 2-5 weeks | Fast resolution of painful conditions (e.g., kidney stones), quick assessment for urinary symptoms, early cancer detection. |
| ENT | 18-30+ weeks (Initial Consult to Surgery) | 2-5 weeks | Relief from chronic ear/nose/throat problems, improved hearing, expedited assessment of head and neck lumps. |
| Neurology | 25-52+ weeks (Initial Consult to Diagnostics) | 3-8 weeks | Faster access, where available, to specialist assessment and advanced imaging, crucial for managing progressive neurological conditions. |
| Mental Health | 12-24+ weeks (Talking Therapy) | 1-4 weeks (limited sessions/acute) | Timely access to professional support for acute mental health issues, preventing escalation and supporting wellbeing. |
| General Surgery | 18-36+ weeks (e.g., Hernia Repair) | 2-6 weeks | Swift treatment for common conditions that cause significant discomfort and disruption to daily life. |
Cost of Private Health Insurance
The cost of private medical insurance varies significantly based on several factors. Understanding these can help you manage your premium and choose a policy that fits your budget.
Factors Influencing Premiums:
- Age: This is the most significant factor. Premiums generally increase with age as the likelihood of needing medical care rises.
- Location: Healthcare costs can vary across different regions of the UK. Policies in areas with higher private hospital charges or greater demand may be more expensive.
- Level of Cover:
- Inpatient Only: This is the most basic and lower-cost cover, paying for treatment as a hospital inpatient (e.g., surgery, hospital stays).
- Outpatient Cover: This adds coverage for consultations, diagnostic tests (MRI, CT scans), and physiotherapy outside of a hospital stay. Comprehensive policies include both inpatient and extensive outpatient cover.
- Therapies: Coverage for physiotherapy, osteopathy, chiropractic treatments can be added.
- Mental Health: Some policies include limited mental health support.
- Excess: This is the amount you agree to pay towards the cost of any claim. A higher excess will result in a lower monthly premium.
- Underwriting Method:
- Full Medical Underwriting: You declare your full medical history upfront. This provides clarity on what is and isn't covered from day one.
- Moratorium Underwriting: You don't declare your full medical history initially. Instead, the insurer excludes conditions you've had in a set period (e.g., the last 5 years). After a claim-free period (e.g., 2 years) for that specific condition, it might become covered if you haven't needed treatment or advice for it during that time.
- No Claims Discount: Similar to car insurance, many providers offer a no-claims discount that rewards you for not making claims, reducing your premium over time.
- Add-ons: Opting for additional benefits like dental and optical cover, or travel insurance, will increase the premium.
Tips for Reducing Costs:
- Choose a higher excess: If you can afford to pay more upfront for treatment, your premium will be lower.
- Select an 'inpatient only' or 'limited outpatient' policy: If your primary concern is avoiding surgical waiting lists, a more basic policy might suffice.
- Opt for the '6-week option': Some policies offer a discount if you agree to use the NHS for treatment if the NHS waiting list is less than 6 weeks for your condition. If the wait is longer, your private cover kicks in.
- Shop around: Premiums can vary significantly between insurers for similar levels of cover. This is where a WeCovr specialist or one of our broker partners becomes invaluable. We compare plans from all major UK insurers to find the right coverage at a competitive price, ensuring you get good value for your specific needs.
Is Private Health Insurance Right for You?
The decision to invest in private health insurance is a personal one, weighing the financial outlay against the potential benefits of faster access and increased choice.
PMI is most beneficial for individuals who:
- Prioritise speed of access: If waiting weeks or months for diagnosis and treatment is unacceptable due to pain, impact on work, or general anxiety.
- Value choice and comfort: Prefer selecting their consultant, having private rooms, and more flexible appointment times.
- Seek peace of mind: Knowing that if an acute health issue arises, they can bypass lengthy NHS queues.
- Are generally healthy: PMI works best for those who develop new, acute conditions rather than managing ongoing chronic illnesses.
Considerations before purchasing:
- Budget: Can you comfortably afford the monthly or annual premiums, factoring in potential increases with age?
- Understand Exclusions: Re-emphasising the critical point: PMI does not cover chronic conditions or pre-existing conditions. If you have an ongoing health issue or a condition you were treated for in the past, standard PMI will not cover it. Your current and past medical history are paramount in determining what your policy will and won't cover.
- Complementary, Not Replacement: PMI complements the NHS; it doesn't replace it. You'll still rely on the NHS for emergency care, GP services, and any chronic conditions.
- Risk Tolerance: Are you comfortable with the possibility of long NHS waits, or do you prefer the certainty of faster private access?
For many, the increasing pressure on the NHS, particularly the expanding waiting lists for elective procedures and diagnostics, makes private medical insurance an increasingly appealing option. It provides a valuable safety net, offering a pathway to prompt treatment for acute health issues that arise, ensuring you can regain your health and return to your daily life without undue delay.
Navigating the Market: How WeCovr Specialists or broker partners Can Help
The UK private health insurance market is diverse, with numerous providers offering a wide range of policies, benefits, and price points. Navigating this landscape independently can be time-consuming and confusing. This is where the expertise of a regulated insurance WeCovr specialist or one of our broker partners proves invaluable.
A WeCovr specialist or one of our broker partners can help with understanding the intricacies of the UK private health insurance market. WeCovr, sometimes working with broker partners, works with major UK insurers, providing you with a comprehensive, unbiased comparison of policies tailored to your specific needs and budget. Our role is to simplify the process, offering regulated guidance and guiding you through the complexities of different levels of cover, excesses, and underwriting options.
How WeCovr assists you:
- Unbiased Advice: We don't favour any single insurer. Our priority is to find a strong fit for your needs for you, based on your health needs, lifestyle, and financial situation.
- Comprehensive Comparison: We gather quotes and policy details from a broad spectrum of providers, allowing you to see all your options in one place.
- Expert Guidance: Our team understands the nuances of policy wordings, exclusions (especially around pre-existing and chronic conditions), and benefit limits. We can explain these clearly, ensuring you make an informed decision.
- Time and Cost Savings: We do the legwork for you, saving you hours of research. Our expertise can also help you identify cost-effective options without compromising on essential coverage.
- Ongoing Support: WeCovr can also provide support beyond the initial purchase, assisting with renewals or policy adjustments as your circumstances change.
We believe that everyone deserves clarity and peace of mind when it comes to their health. By partnering with us, you gain access to a wealth of knowledge and a streamlined process, enabling you to confidently choose the private medical insurance that best fits your requirements.
Conclusion
The UK's healthcare landscape is evolving, with the NHS facing unprecedented demands that result in significant waiting times for many non-emergency treatments. Private medical insurance offers a robust and effective complementary solution, providing individuals with the means to access rapid diagnosis and treatment for acute conditions.
While the NHS continues to deliver critical care, particularly for emergencies and chronic disease management, PMI steps in to bridge the gap for those who seek faster access, greater choice, and enhanced comfort when new, acute health issues arise. From orthopaedic surgeries to ophthalmology, and from diagnostic scans to specialist consultations, the time savings offered by private access can be substantial, leading to quicker recovery, reduced anxiety, and a faster return to daily life.
It is paramount to reiterate that private medical insurance is designed for acute conditions that develop after the policy starts. It does not provide cover for chronic conditions or pre-existing conditions, which remain the responsibility of the NHS. Understanding this fundamental distinction is key to making an informed decision about private cover.
Ultimately, the choice to opt for private medical insurance is a personal one. However, by understanding the current challenges within the NHS and the tangible benefits offered by PMI, particularly the significant reduction in waiting times across numerous specialties, you can make an empowered decision about how best to safeguard your health and wellbeing in the years to come. For tailored advice and to compare your options effectively, a WeCovr specialist or one of our broker partners is here to guide you every step of the way.
Sources
- NHS England: Waiting times and referral-to-treatment statistics.
- Office for National Statistics (ONS): Health, mortality, and workforce data.
- NICE: Clinical guidance and technology appraisals.
- Care Quality Commission (CQC): Provider quality and inspection reports.
- UK Health Security Agency (UKHSA): Public health surveillance reports.
- Association of British Insurers (ABI): Health and protection market publications.
Important Information and Risks
No advice: This article is for general information only. It is not financial, legal, insurance, or tax advice, and it is not a personal recommendation. WeCovr does not assess your individual circumstances or recommend a specific product through this article.
Policy exclusions and underwriting: Insurance policies, including life insurance, private medical insurance, critical illness cover, and income protection, are subject to insurer underwriting, eligibility, acceptance criteria, terms, conditions, limits, and exclusions. Pre-existing medical conditions may be excluded, restricted, or accepted on special terms unless an insurer confirms otherwise in writing.
Tax treatment: References to tax treatment, HMRC rules, or business reliefs are based on current UK legislation and guidance, which can change. Tax treatment depends on your personal or business circumstances and may differ from examples in this article.
Before you buy: Always read the Insurance Product Information Document (IPID), policy summary, and full policy terms before buying, renewing, changing, or keeping cover. If you are unsure whether a policy is suitable for you, speak to an insurance adviser.
Start with your Protection Score, then decide whether private health cover is the right fit
Check where health access sits in your overall protection picture before deciding whether to compare private health cover.
Spot whether NHS access risk is the real issue
See if PMI is the gap to fix first
Get health insurance help only if it makes sense for you
Get your score
Start with your protection score
Check your current position first, then get health insurance help if you need it.
Check your current resilience
Score your income, health access and family protection position in a few minutes.
See where private cover helps
Understand whether faster diagnosis and treatment is a priority gap.
Continue to tailored PMI help
If health access is the issue, continue to tailored PMI help.
What you get
A quick view of your current protection position
A clearer idea of where the biggest gaps may be
A direct route to tailored help if you want it