TL;DR
Understanding the fundamental differences between the NHS and private healthcare is crucial for appreciating the value proposition of PMI.
Key takeaways
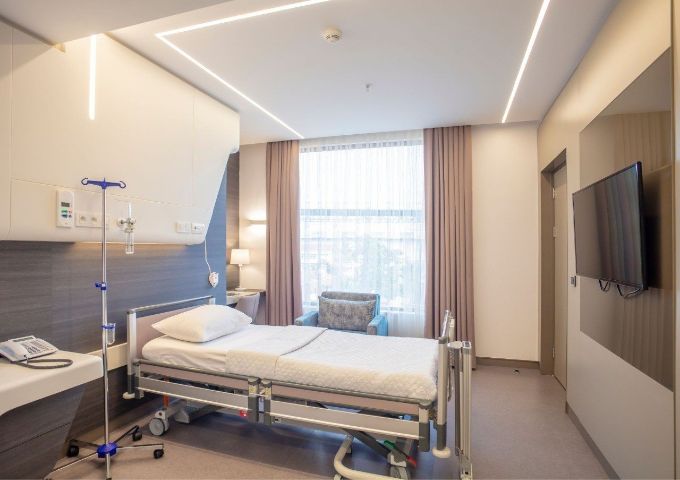
- Hospital accommodation (private room).
- Consultant fees (for diagnosis and treatment).
- Surgical fees.
- Anaesthetist fees.
- Nursing care.
UK Private Health Insurance Strategic Longevity Investment
UK Private Health Insurance as a Strategic Investment: Regional Insurer Pathways for Professional & Athletic Longevity
In an increasingly dynamic and demanding professional landscape, where peak physical and mental performance can be the differentiating factor between success and stagnation, health is no longer merely a personal concern – it's a strategic asset. For professionals and athletes alike, the ability to maintain optimal health, recover swiftly from setbacks, and access timely, high-quality medical care is paramount. This is where UK Private Medical Insurance (PMI) transcends its traditional role as a safety net and emerges as a tangible investment in long-term professional and athletic longevity.
This comprehensive guide will delve into why PMI should be viewed as a strategic investment, exploring its multifaceted benefits, navigating the nuances of the UK healthcare landscape, and particularly focusing on the often-overlooked advantages of regional insurers. We'll demystify the policy components, shed light on critical exclusions, and provide an authoritative roadmap for securing your health, and by extension, your future.
The Evolving Landscape of UK Healthcare and the Strategic Case for PMI
The National Health Service (NHS) remains a cornerstone of British society, providing universal healthcare free at the point of use. Its founding principles are laudable, and its dedicated staff perform miracles daily. However, the NHS is facing unprecedented pressure, from an ageing population and rising demand to workforce shortages and an ever-increasing backlog of treatments.
Recent statistics paint a clear picture:
- As of May 2024, the total number of people waiting for routine hospital treatment in England stood at approximately 7.54 million, with some individuals waiting significantly longer than the target 18 weeks. (NHS England, 2024).
- Emergency department waiting times continue to be a concern, with targets for seeing patients within four hours often missed, leading to prolonged stays in A&E departments.
- The impact of the pandemic has exacerbated pre-existing challenges, pushing waiting lists to record highs and delaying crucial diagnostic and elective procedures.
These pressures mean that while emergency care remains robust, access to elective surgeries, specialist consultations, and diagnostic tests can involve considerable delays. For a professional whose income depends on their cognitive sharpness and physical presence, or an athlete whose career hinges on rapid recovery from injury, these delays are not just an inconvenience – they are a direct threat to their livelihood and long-term potential.
PMI offers an alternative pathway, providing faster access to diagnostics, specialist consultations, and private hospital treatment. It allows individuals to reduce waiting times compared with NHS lists (subject to policy terms) for elective procedures, choose their consultants, and often benefit from more comfortable private facilities. This speed and choice are the bedrock of its strategic value.
NHS vs. Private Healthcare: A Comparative Overview
Understanding the fundamental differences between the NHS and private healthcare is crucial for appreciating the value proposition of PMI.
| Feature | NHS Healthcare | Private Healthcare (with PMI) |
|---|---|---|
| Cost | Free at the point of use (funded by general taxation) | Paid for through premiums or direct payments |
| Access Speed | Can involve significant waiting lists for non-urgent procedures | Generally much faster access to diagnostics and treatment |
| Choice of Consultant | Limited/Allocated | Often the ability to choose your consultant |
| Hospital Facilities | Varying, can be multi-bed wards | Private rooms, enhanced amenities often standard |
| Appointment Flexibility | Less flexible | More flexible scheduling |
| Geographic Coverage | Universal | Extensive network of private hospitals and clinics |
| Scope of Cover | Comprehensive, including chronic and emergency care | Focus on acute conditions (key distinction discussed below) |
Understanding Private Medical Insurance: Acute vs. Chronic Conditions – A Critical Distinction
This is perhaps the most fundamental and often misunderstood aspect of UK Private Medical Insurance. It is absolutely crucial to grasp this distinction:
Standard UK Private Medical Insurance is designed to cover acute conditions that arise after the policy begins.
It does not cover chronic or pre-existing conditions. Let's break this down with absolute clarity.
Acute Conditions
An acute condition is a disease, illness, or injury that is sudden in onset, severe in its symptoms, and generally has a short course, with a expectation of full recovery or a return to a stable state. Crucially, for PMI purposes, it must be a new condition that develops after you have taken out your policy.
Examples of Acute Conditions PMI May Cover (subject to policy terms and exclusions):
- A newly diagnosed hernia requiring surgery.
- A sudden back injury (e.g., slipped disc) requiring physiotherapy or surgery.
- Appendicitis.
- A new cancer diagnosis (for treatment, though long-term management might transition to NHS).
- A fracture from an accident.
- A sudden, severe infection requiring hospitalisation.
Chronic Conditions
A chronic condition, in the context of UK PMI, is a disease, illness, or injury which:
- Has no known cure.
- Requires long-term or indefinite management.
- Recurs or is likely to recur.
- Persists for an extended period.
- Requires rehabilitation or special training.
Standard UK PMI Does Not Cover Chronic Conditions. The NHS will manage chronic conditions. Your private policy might cover initial diagnosis and treatment for an acute exacerbation of a chronic condition, but not the ongoing management of the underlying chronic condition itself.
Examples of Chronic Conditions PMI Will Not Cover:
- Diabetes (Type 1 or Type 2).
- Asthma (ongoing management).
- Rheumatoid arthritis (ongoing management).
- Epilepsy.
- High blood pressure (ongoing management).
- Cystic fibrosis.
- Parkinson's disease.
- Multiple sclerosis.
- Long-term mental health conditions requiring ongoing therapy or medication (though some policies offer limited short-term mental health support for acute episodes).
Pre-existing Conditions
A pre-existing condition is any disease, illness, or injury for which you have received symptoms, diagnosis, advice, or treatment, or had symptoms, even if undiagnosed, within a specified period (typically 2 to 5 years) before the start date of your private medical insurance policy.
Standard UK PMI Does Not Cover Pre-existing Conditions. This is a non-negotiable rule. If you had an issue with your knee two years ago that required treatment, and then it flares up again after your policy starts, it will likely be excluded.
Common Scenarios and Clarifications:
- A new symptom related to an old issue: If you had back pain five years ago that resolved completely, and then develop a completely different type of back pain after your policy starts, this might be covered. However, if it's the same or a very similar issue, it will likely be excluded as pre-existing.
- Undiagnosed symptoms: Even if you hadn't been formally diagnosed but experienced symptoms of a condition before taking out the policy, it could still be considered pre-existing.
- Moratorium vs. Full Medical Underwriting: These are different ways insurers assess pre-existing conditions, which we will explore later. However, the core principle remains: pre-existing conditions are typically excluded.
This clear distinction is paramount when considering PMI. It's a tool for managing new, unforeseen acute health challenges that could otherwise derail your professional or athletic trajectory, ensuring faster access, where available, to care when it matters most.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
PMI as an Investment in Professional Longevity
For professionals across all sectors – from demanding corporate roles to self-employed consultants and creative practitioners – sustained peak performance is inextricably linked to health. Downtime due to illness or injury doesn't just mean lost income; it can mean missed opportunities, client dissatisfaction, and a gradual erosion of competitive edge.
Minimising Downtime and Accelerating Recovery
The most direct benefit of PMI for professionals is its ability to drastically reduce downtime. Imagine a scenario where a busy consultant develops a painful, debilitating condition requiring orthopaedic surgery. On the NHS, they might face several months of waiting for an initial consultation, diagnostics, and then the surgery itself. During this time, their productivity plummets, their focus is impaired, and their career progression stalls.
With PMI, that same consultant could be seen by a specialist within days, undergo diagnostic scans within a week, and potentially have surgery scheduled within a few weeks. Post-surgery, access to private physiotherapy and rehabilitation services can further accelerate recovery, getting them back to full capacity much faster. This isn't merely convenience; it's a strategic move to protect earning potential and career momentum.
Case Study Example: A graphic designer developing carpal tunnel syndrome, or a solicitor experiencing a new, acute back issue, can leverage PMI to receive swift diagnosis and treatment, often through outpatient physiotherapy or minor surgical intervention. This quick resolution prevents the condition from becoming chronic or severely impacting their ability to work, thereby preserving their professional longevity.
Enhanced Mental Wellbeing and Focus
The stress of navigating health issues, particularly when facing long waiting times or uncertainty, can take a significant toll on mental wellbeing. Knowing that you have prompt access, where available, to high-quality care through your PMI can alleviate this anxiety. The peace of mind allows professionals to maintain focus on their work, innovate, and perform without the underlying worry of health disruptions. Some policies also include limited access to mental health support for acute conditions, which can be invaluable for managing stress and burnout prevalent in demanding careers.
Protecting Your Earning Potential
Your health is your human capital. Any prolonged period of ill-health directly impacts your ability to earn. For the self-employed, this means direct income loss. For employees, it can mean using up sick leave, impacting performance reviews, or even jeopardising promotional opportunities. PMI acts as a protective shield for this vital asset.
| Professional Role | Potential Health Challenge (Acute) | Impact without PMI | Benefit with PMI |
|---|---|---|---|
| Consultant/Manager | New onset severe migraines | Lost workdays, impaired decision-making | Rapid diagnosis, appropriate treatment, reduced downtime |
| Self-Employed Tradesperson | Hernia requiring surgery | Months out of work, loss of clients/income | Swift surgery, faster return to manual labour |
| IT Professional | Repetitive strain injury (acute flare-up) | Chronic pain, inability to type/code | Early intervention, physiotherapy, ergonomic advice |
| Teacher/Lecturer | Vocal cord issue (acute) | Inability to teach, disruption to students | Specialist consultation, swift treatment to restore voice |
PMI as an Investment in Athletic Longevity
For athletes, whether professional, semi-professional, or dedicated amateurs, the body is their instrument. Injury is an inherent risk, and prompt, effective treatment is critical not just for performance, but for preventing long-term damage and ensuring continued participation in their chosen sport.
Swift Injury Diagnosis and Treatment
In the world of sport, time is of the essence. A delay of weeks or months in diagnosing a ligament tear or a cartilage issue can turn a recoverable injury into a career-threatening one. PMI provides faster access, where available, to:
- Specialist Consultations: Sports physicians, orthopaedic surgeons, and musculoskeletal specialists often within days.
- Advanced Diagnostics: MRI scans, CT scans, and X-rays can be arranged quickly, providing precise diagnoses crucial for tailored treatment plans.
- Immediate Treatment: From advanced physiotherapy and osteopathy to complex surgeries, PMI facilitates prompt intervention.
This speed minimises atrophy, prevents secondary complications, and significantly shortens the rehabilitation timeline, getting athletes back to training and competition faster and safer.
Access to Leading Sports Medicine Experts and Rehabilitation
Many PMI policies offer access to a network of private hospitals and clinics that specialise in sports medicine, often employing consultants and physiotherapists at the forefront of their fields. This means athletes can benefit from cutting-edge treatments, innovative rehabilitation techniques, and personalised recovery programmes that might not be as readily available or as timely through the NHS.
Rehabilitation is Key: PMI often covers extensive physiotherapy, hydrotherapy, and other rehabilitative therapies crucial for full recovery and injury prevention. This comprehensive approach is vital for athletes to regain strength, flexibility, and confidence, reducing the risk of re-injury.
Mitigating Long-Term Damage and Chronic Issues
Delayed treatment for acute injuries can lead to chronic pain, reduced mobility, and even early retirement from sport. By ensuring rapid and effective intervention, PMI helps prevent acute injuries from developing into debilitating chronic conditions. This preservation of physical health extends an athlete's career and enhances their quality of life long after their competitive days are over.
Case Study Example: A semi-professional footballer suffers a torn meniscus during a match. Without PMI, they might face a long wait for an MRI and subsequent surgery, potentially missing an entire season and risking further damage. With PMI, they receive a rapid scan, a swift surgical repair, and an intensive physiotherapy programme, allowing them to return to the pitch significantly sooner, thus safeguarding their athletic longevity.
| Athletic Discipline | Potential Acute Injury | Risk without PMI | Benefit with PMI |
|---|---|---|---|
| Runner | Acute Achilles tendonitis | Chronic pain, inability to run, reduced mobility | Rapid diagnosis, physiotherapy, potential minor procedure |
| Gymnast/Dancer | Sudden shoulder dislocation | Prolonged pain, reduced range of motion, potential re-injury | Swift reduction, MRI, targeted rehabilitation |
| Cyclist | Collarbone fracture (complex) | Delayed surgery, prolonged recovery, impact on fitness | Rapid surgical fixation, accelerated recovery with physio |
| Team Sports (e.g., Rugby, Football) | ACL tear | Season-ending injury, long-term instability if delayed | Swift surgery, comprehensive post-op rehab, earlier return to play |
Navigating the Regional Insurer Landscape: Advantages and Considerations
While major national insurers dominate the UK PMI market, a number of highly reputable regional insurers offer compelling alternatives, often with specific advantages for those seeking localised care or niche specialisations.
What are Regional Insurers?
Regional insurers typically operate within a defined geographical area, or they might focus on specific demographics or sectors within the UK. While some have expanded their networks, their core strength often lies in deeply established relationships with local hospitals, clinics, and specialists.
Examples (Note: Insurer offerings and focus can change):
- WPA: While having a national presence, WPA has a strong emphasis on local customer service and community engagement.
- General & Medical: Offers a range of plans, often catering to various professional groups.
- CS Healthcare: Specialises in cover for public sector and civil service employees.
- Other smaller, local schemes may exist, often linked to specific hospital groups or regional mutuals.
Advantages of Regional Insurers
-
Localised Networks and Relationships: Regional insurers often have stronger, more intimate relationships with private hospitals, clinics, and consultants in specific areas. This can lead to:
- Better understanding of local healthcare infrastructure: They know which consultants are excellent for specific conditions in your area.
- Potentially more seamless administrative processes: Due to established pathways.
- Access to niche local specialists: Some regions may have specific centres of excellence for sports injuries or other conditions, and a regional insurer might have direct links.
-
Tailored Policy Options: Some regional insurers are more agile and may offer more flexible or niche policies designed to meet the specific needs of a local population or professional group. For instance, a regional insurer in an area with a strong sporting culture might have enhanced sports injury provisions.
-
Personalised Service: Smaller operations can sometimes offer a more personalised, human-centric approach to customer service, where you're not just a policy number. This can be invaluable when navigating complex health issues.
-
Competitive Pricing (in some cases): By focusing on a specific region, they might have lower overheads or negotiate different rates with local providers, potentially leading to more competitive premiums for certain types of cover within their service area.
Considerations When Choosing a Regional Insurer
- Network Coverage: While strong locally, ensure their network covers your usual travel areas or if you frequently travel for work. What happens if you need treatment while away from home?
- Specialist Access: Confirm they have agreements with the specific types of specialists or hospitals you might need, especially for highly specialised procedures.
- Financial Stability: Always check the financial stability of any insurer, regardless of size. The Financial Conduct Authority (FCA) regulates all UK insurers, and the Financial Services Compensation Scheme (FSCS) offers protection in case an authorised firm fails.
- Policy Terms and Exclusions: Regional insurers are still subject to the same rules regarding acute vs. chronic and pre-existing conditions. Always scrutinise the policy terms, particularly the small print.
- Comparison is Key: Don't assume a regional insurer is automatically better or cheaper. Their advantages are specific. This is where a WeCovr specialist or one of our broker partners becomes invaluable. A WeCovr specialist or trusted broker partner can compare regional offerings against national providers to find the most suitable policy for your unique needs.
We work with a comprehensive panel of UK insurers, both national and regional, to ensure you get the broadest possible choice. Our expertise allows us to highlight the unique strengths of each, matching you with the right fit.
Key Components of a Comprehensive Private Health Insurance Policy
While policies vary, most private medical insurance plans in the UK share common core components. Understanding these is essential for making an informed decision.
1. In-Patient Cover
This is the bedrock of most PMI policies. It covers treatment you receive when formally admitted to a hospital and occupying a bed. This includes:
- Hospital accommodation (private room).
- Consultant fees (for diagnosis and treatment).
- Surgical fees.
- Anaesthetist fees.
- Nursing care.
- Drugs and dressings used during your stay.
2. Day-Patient Cover
Covers treatment and care received in a hospital on a day-case basis, where you are admitted and discharged on the same day where available. This is increasingly common for minor procedures and diagnostics.
3. Out-Patient Cover
This covers consultations and diagnostic tests that do not require an overnight stay or day-patient admission. This is often an optional add-on or has limits. Key elements include:
- Consultant fees for initial and follow-up appointments.
- Diagnostic tests (e.g., MRI scans, X-rays, blood tests, CT scans, ultrasounds).
- Pathology (lab tests).
Important Note: Out-patient limits vary significantly between policies. For professionals and athletes, robust out-patient cover is often critical for speedy diagnosis and follow-up.
4. Therapies (Physiotherapy, Osteopathy, Chiropody, etc.)
Many policies include cover for a range of complementary therapies, usually on an out-patient basis. This is particularly vital for athletes recovering from injuries or professionals managing musculoskeletal issues. There are usually limits on the number of sessions or the total cost per year.
5. Mental Health Cover
While comprehensive long-term mental health cover is rare (due to its often chronic nature), many policies now include limited cover for acute mental health conditions, such as short-term therapy or psychiatric consultations for defined acute episodes.
6. Cancer Cover
More comprehensive PMI policies include excellent cancer cover, from diagnosis and treatment (including chemotherapy, radiotherapy, and biological therapies) to post-treatment follow-up. This is often a significant benefit, providing access to newer drugs and technologies that may not be immediately available on the NHS.
7. Core Exclusions (Beyond Chronic/Pre-existing)
Even for acute conditions, certain things are generally not covered by standard PMI:
- Chronic Conditions: As extensively discussed.
- Pre-existing Conditions: As extensively discussed.
- Emergency Services: Accidents and emergencies are always handled by the NHS. PMI is for planned treatment.
- Normal Pregnancy and Childbirth: Though some policies may cover complications.
- Cosmetic Surgery: Unless medically necessary following an accident or illness covered by the policy.
- Dental and Optical Treatment: Unless it's a specific add-on for accidents or specific surgical procedures.
- Organ Transplants: Typically not covered.
- Drug Addiction/Alcohol Abuse: Treatment for these is generally excluded.
- HIV/AIDS: Treatment for these conditions is generally excluded.
- Self-inflicted injuries.
- Overseas treatment: Unless it's a specific travel health insurance add-on.
It's paramount to read the policy documentation carefully to understand the exact scope of cover and all exclusions.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Cost Considerations: What Influences PMI Premiums?
The cost of private medical insurance can vary significantly. Several factors influence the premium you pay:
1. Age
This is the most significant factor. Premiums generally increase with age, as the likelihood of needing medical treatment rises.
2. Location
Where you live in the UK can affect premiums. Areas with higher costs of living or a greater density of expensive private hospitals (e.g., London) will typically have higher premiums.
3. Level of Cover and Inclusions
More comprehensive policies with higher out-patient limits, extensive therapy cover, or advanced cancer drugs will naturally cost more. Selecting add-ons like mental health support or travel cover also increases the premium.
4. Excess
An excess is the amount you agree to pay towards a claim before the insurer pays the rest. Choosing a higher excess could reduce your premium, but you'll pay more out-of-pocket if you make a claim.
5. Hospital Network
Insurers often offer different hospital lists. A more restrictive list (e.g., excluding central London hospitals) can lead to lower premiums. A broader list, including premium facilities, will cost more.
6. Underwriting Method
The way your medical history is assessed affects your premium and what's covered.
| Underwriting Method | Description | Impact on Premiums/Cover |
|---|---|---|
| Moratorium | Most common. Insurer assumes no pre-existing conditions. Conditions from the past 5 years are automatically excluded initially. If you go 2 years symptom-free after policy start, that condition may become covered. | Simpler to apply, may be cheaper initially. Risk of future exclusion if symptoms recur. |
| Full Medical Underwriting (FMU) | You declare your full medical history upfront. Insurer reviews it and provides firm exclusions or accepts certain conditions. | More involved application. Clearer upfront what is/isn't covered. May be slightly more expensive for certain profiles. |
| Continued Personal Medical Exclusions (CPME) | Used when switching insurers. Your existing exclusions are carried over to the new policy. | Ensures continuity of cover without new exclusions for past conditions. |
| Medical History Disregarded (MHD) | Usually for corporate schemes. No medical history declared; all conditions (except chronic) may be covered from day one. | More comprehensive cover, but much more expensive. Rarely available to individuals. |
7. Lifestyle Factors
While less impactful than age or location, some insurers may consider smoking status, BMI, or participation in extreme sports when calculating premiums, though this is less common for standard individual policies.
The Application Process and Underwriting: What to Expect
Applying for PMI involves a few key steps:
- Information Gathering: You'll need to provide personal details, your address, and information about any pre-existing conditions (depending on the underwriting method chosen).
- Choosing Underwriting: Decide between Moratorium and Full Medical Underwriting. A WeCovr specialist or one of our broker partners can guide you on which might be best for your circumstances.
- Quotation: The insurer will provide a quote based on your age, location, chosen cover, and underwriting method.
- Acceptance/Exclusions:
- Moratorium: You'll typically be accepted immediately, but remember the automatic exclusions for conditions in the last 5 years.
- Full Medical Underwriting: The insurer may ask for more details from your GP or specialists. They will then confirm any specific exclusions for conditions declared or discovered.
- Policy Start: Once accepted and the first premium paid, your policy goes live. Remember, coverage is for new, acute conditions arising from this date.
Transparency is Vital: Always be completely honest and thorough when providing medical information. Non-disclosure can invalidate your policy later, leaving you without cover when you need it most.
Making a Claim: A Step-by-Step Guide
Making a claim on your PMI policy is generally a straightforward process:
- Visit Your GP: If you experience symptoms, your first step should always be to see your NHS GP. They will assess your condition and, if necessary, refer you for a specialist consultation.
- Inform Your Insurer: Before your private specialist appointment, contact your PMI insurer. You'll need to provide details of your GP's referral and symptoms.
- Pre-Authorisation: The insurer will typically "pre-authorise" your consultation and any initial diagnostic tests (e.g., blood tests, X-rays, MRI scans). This confirms that they deem the condition acute and potentially covered. They will often provide you with an authorisation code.
- Specialist Consultation and Diagnostics: Attend your private appointment. The specialist will assess you and recommend a course of action, which might include further diagnostics or treatment.
- Further Pre-Authorisation (for Treatment): If your specialist recommends a procedure, surgery, or extensive treatment (e.g., chemotherapy, physiotherapy), you will need to seek further pre-authorisation from your insurer. They will review the proposed treatment plan to confirm it aligns with your policy terms and is for an acute, covered condition.
- Treatment: Once pre-authorised, you can proceed with the recommended treatment. The hospital or clinic will usually bill the insurer directly.
- Excess Payment: If your policy has an excess, you will pay this directly to the hospital or consultant.
Key Tips for Smooth Claims:
- Always pre-authorise: Never assume treatment will be covered. Always get approval from your insurer before proceeding with consultations, tests, or treatments.
- Keep records: Maintain copies of all correspondence, invoices, and medical reports.
- Understand your limits: Be aware of any monetary limits on out-patient consultations, therapies, or specific treatments.
Comparing Policies: The Role of an Expert Broker
Given the complexity of the UK private health insurance market, with numerous insurers, policy types, and underwriting options, navigating it alone can be daunting. This is where the expertise of a WeCovr specialist or one of our broker partners
Why Use a Broker?
- Market Access: WeCovr has access to a wide range of policies from all major UK insurers, including many national and regional providers. This means you don't have to spend hours researching and getting quotes from multiple companies.
- Regulated Advice: As a regulated broker, our loyalty is to you, the client, not to a specific insurer. We provide regulated advice, helping you understand the pros and cons of different policies based on your specific needs and budget.
- Expert Knowledge: We understand the nuances of each policy, the underwriting processes, and crucially, the critical distinction between acute, chronic, and pre-existing conditions. We can explain complex jargon in plain English.
- Tailored Recommendations: For professionals and athletes, generic policies often don't cut it. We take the time to understand your unique professional demands, athletic pursuits, and health history to recommend policies with the right level of cover for things like physiotherapy, sports injury specialists, or specific diagnostic limits.
- Navigating Regional Pathways: If you're considering a regional insurer, we can provide insights into their networks, local relationships, and compare their offerings directly against national providers to determine the right fit for your locality.
- Saving You Time and Money: By doing the research and comparison for you, we save you significant time. Our expertise can also help you avoid common pitfalls and potentially save you money by finding the most cost-effective policy that still meets your requirements.
- Ongoing Support: Our relationship doesn't end when you purchase a policy. We can offer ongoing support with renewals, claims queries, and policy adjustments.
WeCovr believes that an informed decision is the best decision. We empower you with the knowledge and choice to make a strategic investment in your health and longevity.
Beyond the Basics: Enhancements and Ancillary Benefits
Modern PMI policies are increasingly comprehensive, offering a range of additional benefits designed to promote overall wellbeing. While these are often optional add-ons, they can significantly enhance the value of your policy.
1. Optical and Dental Cover
Separate from medical conditions, some policies offer optional add-ons for routine optical (eye tests, glasses/lenses) and dental care (check-ups, fillings, hygienist visits). This is typically a fixed annual allowance.
2. Travel Health Insurance
While PMI covers treatment in the UK, some providers offer integrated or optional travel health insurance for medical emergencies or planned treatment abroad. This can be convenient for professionals who travel frequently.
3. Health & Wellbeing Services
Many insurers now include access to a range of non-medical benefits:
- Virtual GP Services: 24/7 access to a GP via phone or video consultation. Incredibly convenient for busy professionals.
- Mental Health Helplines: Confidential support lines for mental wellbeing.
- Health Assessments/Screenings: Some policies offer discounted or free annual health checks.
- Discounted Gym Memberships/Wearables: Partnerships with fitness brands to encourage healthier lifestyles.
- Nutritional Advice: Access to dietitians or nutritionists.
4. Lifestyle and Preventative Health Programmes
A growing trend sees insurers moving towards preventative care. This can include:
- Weight Management Programmes.
- Smoking Cessation Support.
- Stress Management Resources.
These benefits align perfectly with the concept of PMI as a strategic investment in longevity, as they actively support maintaining health rather than just reacting to illness.
The Future of UK Private Health Insurance
The landscape of UK healthcare is constantly evolving. Several trends are likely to shape the future of PMI:
- Digital Transformation: Increased reliance on virtual consultations, AI-powered diagnostics, and digital health records will streamline processes and potentially make care more accessible.
- Focus on Preventative Health: Insurers will continue to invest in and incentivise preventative care, recognising that keeping policyholders healthy is mutually beneficial.
- Personalisation: Driven by data analytics, policies will likely become even more tailored to individual risk profiles, lifestyle, and specific health needs.
- Integration with Wearable Technology: Data from smartwatches and fitness trackers could play a role in personalised health management and even influence premiums for health-conscious individuals.
- Response to NHS Pressures: As NHS waiting lists remain a challenge, the demand for private care is likely to persist, driving innovation and expansion in the PMI market.
PMI is not static; it's adapting to meet the modern demands of individuals who prioritise their health as a fundamental pillar of their professional and personal success.
Conclusion: PMI – A Strategic Imperative for Longevity
In an era where personal resilience and sustained performance are key differentiators, neglecting your health is no longer a viable option. UK Private Medical Insurance, particularly when chosen with careful consideration of its benefits and limitations (especially regarding acute vs. chronic and pre-existing conditions), transforms from a mere insurance product into a strategic investment.
For professionals, it means safeguarding earning potential, minimising career disruption, and maintaining mental acuity. For athletes, it signifies swift recovery from injury, access to leading sports medicine, and the preservation of physical capabilities, extending their active years. Regional insurers, with their localised expertise and personalised approach, offer a valuable pathway for many, complementing the robust offerings of national providers.
Choosing a strong fit for your needs requires expertise, market insight, and an understanding of your unique circumstances. This is precisely where WeCovr excels. We stand ready to guide you through the complexities, comparing comprehensive plans from all major UK insurers – national and regional – to find a tailored solution that empowers you to protect your most valuable asset: your health, ensuring your professional and athletic longevity for years to come.
Take control of your health future. Explore how private medical insurance can be your next strategic investment.
Sources
- NHS England: Waiting times and referral-to-treatment statistics.
- Office for National Statistics (ONS): Health, mortality, and workforce data.
- NICE: Clinical guidance and technology appraisals.
- Care Quality Commission (CQC): Provider quality and inspection reports.
- UK Health Security Agency (UKHSA): Public health surveillance reports.
- Association of British Insurers (ABI): Health and protection market publications.
Important Information and Risks
No advice: This article is for general information only. It is not financial, legal, insurance, or tax advice, and it is not a personal recommendation. WeCovr does not assess your individual circumstances or recommend a specific product through this article.
Policy exclusions and underwriting: Insurance policies, including life insurance, private medical insurance, critical illness cover, and income protection, are subject to insurer underwriting, eligibility, acceptance criteria, terms, conditions, limits, and exclusions. Pre-existing medical conditions may be excluded, restricted, or accepted on special terms unless an insurer confirms otherwise in writing.
Tax treatment: References to tax treatment, HMRC rules, or business reliefs are based on current UK legislation and guidance, which can change. Tax treatment depends on your personal or business circumstances and may differ from examples in this article.
Before you buy: Always read the Insurance Product Information Document (IPID), policy summary, and full policy terms before buying, renewing, changing, or keeping cover. If you are unsure whether a policy is suitable for you, speak to an insurance adviser.
Compare private health insurance quotes from leading UK insurers
Answer a few quick questions and a specialist from WeCovr or one of its broker partners will help you compare cover from insurers such as Bupa, AXA, Aviva and Vitality. No obligation.
Takes about 2-3 minutes
Compare cover from leading UK insurers
No obligation to buy
Get a quote
Get a private health insurance quote
Answer a few questions, then a specialist helps you compare cover and prices.
Tell us who needs cover
Just you, a partner, your family or your staff.
Compare your options
A specialist compares cover and prices from leading UK insurers.
Decide in your own time
There is no obligation to buy.
What you get
A specialist from WeCovr or one of its broker partners
Options compared across leading UK insurers
No obligation to buy