TL;DR
Living with an autoimmune disease or a complex chronic condition in the UK presents a unique set of challenges. From the day-to-day management of symptoms to navigating lengthy diagnostic pathways and accessing specialist care, the journey can be arduous. While the National Health Service (NHS) provides an invaluable backbone of care, its increasing strain often translates into significant waiting times for appointments, diagnostics, and treatments.
Key takeaways
- GP Referral: Most PMI policies require a referral from a GP (NHS or private). Some policies may offer a "Direct Access" option for certain specialities or therapies (e.g., physiotherapy) without an initial GP visit.
- Consultant Appointment: Once referred, you can typically book an appointment with a private consultant within a few days to a week. You often have a choice of consultants within your insurer's approved network.
- Diagnostic Tests: If the consultant deems further tests necessary (e.g., MRI, CT scan, endoscopy, blood tests), these can usually be scheduled within days. The results are processed quickly, and a follow-up appointment arranged.
- Treatment: If a treatment (e.g., surgery, specific acute therapy) is recommended for a covered condition, it can often be scheduled very quickly, sometimes within a week or two.
- Reduced Anxiety: The unknown is often the most stressful part of new symptoms. Rapid diagnosis provides clarity and peace of mind.
Living with an autoimmune disease or a complex chronic condition in the UK presents a unique set of challenges. From the day-to-day management of symptoms to navigating lengthy diagnostic pathways and accessing specialist care, the journey can be arduous. While the National Health Service (NHS) provides an invaluable backbone of care, its increasing strain often translates into significant waiting times for appointments, diagnostics, and treatments.
For many, this raises a crucial question: Can private health insurance offer a viable solution, especially when dealing with conditions that are by nature long-term and often unpredictable? The answer is nuanced, and it's essential to understand the intricacies of how private medical insurance (PMI) operates in the context of pre-existing and chronic conditions.
This comprehensive guide will demystify private health insurance for individuals grappling with autoimmune conditions like Crohn's disease, Ulcerative Colitis, Rheumatoid Arthritis, Multiple Sclerosis, Lupus, and other complex chronic illnesses. We'll explore how PMI can complement NHS care, providing faster access, where available, to diagnostics, second opinions, and acute treatment pathways, even when the underlying chronic condition itself is not covered. Our goal is to equip you with the knowledge to make informed decisions about your healthcare, ensuring you understand both the significant benefits and the inherent limitations.
Understanding Autoimmune & Complex Chronic Conditions
Autoimmune diseases are conditions where the body's immune system mistakenly attacks its own healthy tissues. This can affect virtually any part of the body, leading to a wide range of symptoms and varying degrees of severity. Examples include:
- Rheumatoid Arthritis: An inflammatory condition primarily affecting joints.
- Crohn's Disease & Ulcerative Colitis (Inflammatory Bowel Disease - IBD): Affecting the digestive tract.
- Multiple Sclerosis (MS): Affecting the brain and spinal cord.
- Lupus (Systemic Lupus Erythematosus - SLE): A systemic disease affecting multiple organs.
- Psoriasis: A skin condition, often with associated psoriatic arthritis.
- Type 1 Diabetes: Where the immune system attacks insulin-producing cells.
Complex chronic conditions, while not always autoimmune, share similar characteristics of long duration, slow progression, and requiring ongoing management. These might include certain types of chronic pain syndromes, fibromyalgia, or long-term neurological conditions.
The impact of these conditions is profound, not just on physical health but also on mental well-being, social life, and employment. According to The Health Foundation, around 15 million people in England have one or more long-term conditions, accounting for 50% of all GP appointments and 70% of inpatient bed days. Many of these are complex and chronic. Autoimmune conditions alone are estimated to affect up to 4 million people in the UK, with incidence rates on the rise.
Key characteristics that make these conditions challenging to manage include:
- Fluctuating Symptoms: Periods of remission interspersed with unpredictable flare-ups.
- Multi-system Involvement: Affecting various organs and bodily functions.
- Diagnostic Delay: Often taking years to diagnose due to non-specific symptoms.
- Co-morbidities: High likelihood of developing other health issues, including mental health conditions.
- Lifelong Management: Requiring continuous monitoring, medication, and lifestyle adjustments.
The NHS vs. Private Healthcare for Chronic Conditions: A Complementary Role
The NHS is a universal healthcare system, providing comprehensive care to all UK residents, free at the point of use. For chronic and autoimmune conditions, the NHS excels in providing long-term management, ongoing prescriptions, specialist clinics, and emergency care. Patients are typically under the care of a multidisciplinary team (MDT) comprising consultants, specialist nurses, physiotherapists, and dietitians.
However, the NHS faces immense pressure. Rising demand, staffing shortages, and post-pandemic backlogs have led to unprecedented waiting times. As of January 2024, the total waiting list for planned care in England stands at 7.6 million people, with over 3 million waiting more than 18 weeks. For specialist appointments and diagnostic tests crucial for complex conditions, these delays can be particularly frustrating and debilitating.
This is where private health insurance can play a significant, complementary role. It is not designed to replace the NHS for chronic conditions but rather to provide faster access, where available, to specific elements of care that might otherwise involve long waits. Think of it as a bypass system for certain parts of the healthcare journey.
| Feature | NHS Care (for Chronic Conditions) | Private Medical Insurance (PMI) |
|---|---|---|
| Primary Role | Long-term management, routine appointments, emergency care | Faster access, where available, to diagnostics, consultations, acute treatment for new or acute issues. |
| Cost | Free at the point of use (taxpayer funded) | Requires monthly/annual premiums; potential excess/co-pay. |
| Access Speed | Variable, often significant waiting lists for specialist appointments/diagnostics | Typically faster access (where available) (days to weeks) for covered services. |
| Consultants | Allocated based on availability, often large caseloads | Choice of consultant (within insurer network), often more dedicated time. |
| Hospital Stay | General wards, limited privacy | Private rooms, enhanced comfort, flexible visiting hours. |
| Treatment Scope | Comprehensive, including long-term drug therapies | Covers acute conditions; does not cover chronic conditions themselves (see below). |
| Geographic Coverage | UK-wide | Typically UK-wide, some policies may offer international cover for emergencies. |
| Continuity of Care | Often good within specialist clinics, but transitions can be clunky | Can offer integrated pathways for acute issues, but core chronic management often remains NHS. |
| Mental Health | Variable, often long waits for specialist therapies | Increasingly common inclusion for short-term, acute mental health support. |
| Rehabilitation | Limited, often group-based | Private physiotherapy, osteopathy, chiropractic often covered for acute injuries/flare-ups. |
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
The Core Truth: Pre-existing & Chronic Conditions Are Excluded
This is the most critical point to understand when considering private health insurance for autoimmune or complex chronic conditions. Private medical insurance policies in the UK are fundamentally designed to cover acute conditions that arise after the policy begins, and which are expected to respond quickly to treatment.
They are not designed to cover:
- Chronic Conditions: Any disease, illness, or injury that has no known cure, or that is likely to continue for a long period, or to recur. This includes all autoimmune diseases and most complex chronic conditions.
- Pre-existing Conditions: Any disease, illness, or injury for which you have received symptoms, medication, advice, or treatment in a specified period (typically the last 5 years) before taking out the policy.
Why the Exclusion?
Insurers operate on a risk-pooling model. If they were to cover pre-existing or chronic conditions, the cost would be astronomically high for everyone, making policies unaffordable and unsustainable. The very nature of a chronic condition means it requires ongoing, potentially lifelong, and expensive management. PMI focuses on providing faster access, where available, to treatment for new and acute health problems.
What Does This Mean in Practice?
If you have, for example, Crohn's disease:
- Your ongoing medication for Crohn's: Not covered. (NHS responsibility)
- Routine consultations with your gastroenterologist for Crohn's management: Not covered. (NHS responsibility)
- A planned surgery directly related to your ongoing Crohn's management (e.g., bowel resection for chronic inflammation): Not covered. (NHS responsibility)
- An emergency admission due to an acute, severe flare-up of Crohn's that requires immediate critical care: Not covered if it's considered part of the chronic condition's expected course. However, if the flare-up leads to an entirely new, acute complication (e.g., a new abscess requiring drainage that is distinct from your established Crohn's management), this might be considered for cover, depending on the specific policy terms and medical assessment. This is a grey area and highly dependent on medical opinion and insurer review.
This distinction is often the most challenging aspect for individuals with chronic conditions to grasp, as they hope PMI will alleviate the burden of their primary health challenge. It's vital to set realistic expectations from the outset.
So, How Can Private Health Insurance Still Help? A Strategic Approach
Despite the exclusions for chronic and pre-existing conditions, PMI can still be incredibly valuable for individuals with autoimmune and complex chronic conditions. The benefit lies in its ability to provide faster access, where available, to diagnostics and treatment for new symptoms or acute conditions that arise, which are not directly a recurrence or continuation of the pre-existing chronic condition.
Here's a breakdown of how PMI can assist:
1. Rapid Diagnostics for New Symptoms
One of the most significant advantages of PMI is speed. When you develop a new symptom or a health concern that isn't clearly attributable to your known chronic condition, rapid diagnosis is paramount.
- Scenario: You have Rheumatoid Arthritis, but suddenly develop persistent, severe headaches unlike anything you've experienced before.
- PMI Benefit: Instead of waiting weeks or months for an NHS GP referral to a neurologist and subsequent MRI scan, PMI can facilitate a private GP referral to a consultant neurologist within days, followed by a scan quickly. If a new, acute condition (e.g., a specific type of migraine or a benign cyst) is diagnosed and requires acute treatment, this may be covered. If it's eventually linked back to your pre-existing RA, it may become an exclusion. The value here is the speed of investigation and peace of mind, allowing for prompt action.
This rapid diagnostic pathway can be critical for: * Ruling out serious conditions. * Identifying new, unrelated illnesses. * Diagnosing acute complications of a chronic condition that are deemed separate and treatable.
2. Management of Acute Episodes & Complications (Non-Chronic)
While the chronic condition itself isn't covered, an acute issue that arises from or is complicated by the chronic condition, but is considered a distinct, treatable episode, might be.
-
Scenario: You have Type 1 Diabetes (a chronic condition). You suddenly experience severe, unexplained abdominal pain.
-
PMI Benefit: If investigations reveal a new, acute issue like appendicitis or a gallstone requiring urgent surgery, PMI would likely cover the consultation, diagnostics, surgery, and post-operative care. This is an acute, treatable condition, distinct from your ongoing diabetes management, even though your diabetes status might influence the surgical approach.
-
Scenario: You have Ulcerative Colitis. You develop a non-bowel-related, acute musculoskeletal injury, such as a fractured wrist from a fall.
-
PMI Benefit: PMI would cover the consultations, imaging, casting, and potentially physiotherapy for the fractured wrist, as this is an acute, non-chronic injury.
3. Mental Health Support
Living with a chronic or autoimmune condition significantly increases the risk of developing mental health issues such as depression, anxiety, or adjustment disorders. Many modern PMI policies now include robust mental health benefits.
- PMI Benefit: Faster access, where available, to private psychiatrists, psychologists, and therapists for short-term, acute mental health conditions. While long-term, ongoing psychotherapy for a chronic condition might not be covered, initial assessment, short courses of cognitive behavioural therapy (CBT), or other talking therapies for acute episodes of anxiety or depression are often included. This can be a lifeline for those struggling with the emotional toll of their physical health.
4. Physiotherapy & Rehabilitation
Acute injuries or flare-ups (that are not part of the chronic condition) often require physical rehabilitation.
- PMi Benefit: Coverage for sessions with private physiotherapists, osteopaths, or chiropractors. For instance, if you strain your back (an acute injury) while living with MS, private physio can help support your recovery than waiting for NHS appointments.
5. Access to Second Opinions
Sometimes, you might want a second opinion on a new diagnosis, or a complex treatment plan presented by the NHS.
- PMI Benefit: PMI can facilitate faster access, where available, to a different consultant for a second opinion, helping you feel more confident about your healthcare decisions. This is particularly valuable for complex conditions where diagnostic uncertainty or treatment pathways can be challenging.
6. Advanced Therapies and Technologies (When Applicable & Not Chronic)
While specific chronic drug therapies are not covered, some policies might provide access to newer diagnostic technologies or acute surgical techniques that might have longer waiting lists or less availability on the NHS. This is highly dependent on the specific acute problem being addressed and the policy terms.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Integrated Care Models in Private Healthcare
While "integrated care" is often associated with NHS reforms (e.g., Integrated Care Systems - ICSs), private healthcare providers are also increasingly focusing on holistic, coordinated care pathways, particularly for acute episodes.
For individuals with complex chronic conditions, this can mean:
- Coordinated Diagnostic Journeys: If you have a new symptom, a private provider might offer a streamlined pathway from initial GP referral to specialist consultation, diagnostic tests (e.g., MRI, blood tests), and follow-up, all within the same hospital group or network, reducing the need to navigate multiple services.
- Multidisciplinary Team Approach (for Acute Issues): For a covered acute condition (e.g., a new cancer diagnosis that isn't pre-existing), private hospitals often convene MDTs to discuss treatment plans, similar to the NHS, but with potentially faster turnaround times.
- Post-Treatment Support: Following an acute surgical procedure covered by PMI, policies often include post-operative physiotherapy, mental health support, or rehabilitation, ensuring a more comprehensive recovery pathway.
It's important to remember that this "integrated care" within PMI typically applies to acute, covered episodes, not the long-term management of your chronic condition, which remains primarily under NHS care. However, the efficiency and speed of the private system for those acute episodes can significantly reduce overall health anxiety and improve outcomes.
Faster Access (Where Available) Pathways: A Deeper Dive into the Benefit
The single most cited reason for purchasing private health insurance in the UK is the desire for faster access, where available, to healthcare. For someone with a chronic condition, this speed can be transformative.
How Faster Access (Where Available) Works:
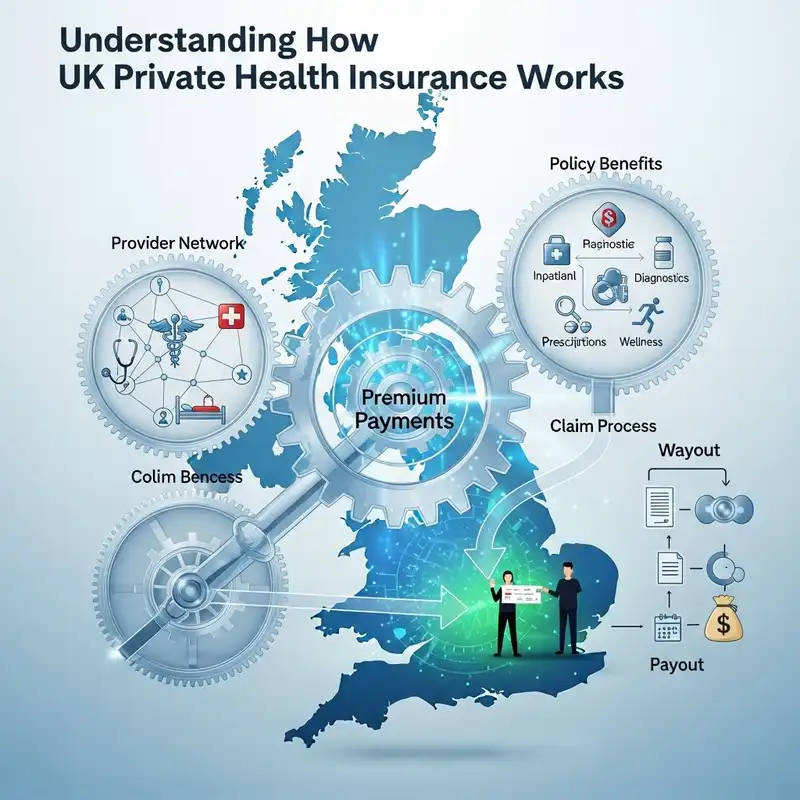
- GP Referral: Most PMI policies require a referral from a GP (NHS or private). Some policies may offer a "Direct Access" option for certain specialities or therapies (e.g., physiotherapy) without an initial GP visit.
- Consultant Appointment: Once referred, you can typically book an appointment with a private consultant within a few days to a week. You often have a choice of consultants within your insurer's approved network.
- Diagnostic Tests: If the consultant deems further tests necessary (e.g., MRI, CT scan, endoscopy, blood tests), these can usually be scheduled within days. The results are processed quickly, and a follow-up appointment arranged.
- Treatment: If a treatment (e.g., surgery, specific acute therapy) is recommended for a covered condition, it can often be scheduled very quickly, sometimes within a week or two.
Benefits of Speed for Chronic Condition Sufferers:
- Reduced Anxiety: The unknown is often the most stressful part of new symptoms. Rapid diagnosis provides clarity and peace of mind.
- Earlier Intervention: For acute issues, earlier diagnosis and treatment can lead to better outcomes and prevent complications.
- Complementary to NHS Care: If a new issue is diagnosed via PMI and it turns out to be chronic or related to your existing condition, you can then seamlessly transition this information back to your NHS team, potentially accelerating their care pathway for you. You effectively use PMI to jump the diagnostic queue, then leverage the NHS for ongoing management.
- Avoiding Worsening of Condition: Long waits can mean symptoms worsen, potentially impacting your ability to manage your existing chronic condition. Quick intervention can prevent a domino effect.
Choosing a strong fit for your needs & Understanding Underwriting
Selecting a private health insurance policy when you have a pre-existing or chronic condition requires careful consideration of underwriting methods. This determines how your pre-existing conditions are assessed and excluded.
There are two primary types of medical underwriting for individual health insurance policies in the UK:
1. Moratorium Underwriting (Morrie)
- How it Works: This is the most common type. When you apply, you don't need to provide a detailed medical history upfront. Instead, the insurer automatically excludes any condition for which you've had symptoms, received treatment, or sought advice during a specific period (usually the last 5 years) before the policy starts.
- "Rolling Moratorium": If you go 2 consecutive years without any symptoms, treatment, medication, or advice for a pre-existing condition after your policy starts, that condition may then become eligible for cover. However, this rarely applies to chronic or autoimmune conditions, as they typically require ongoing management, meaning the 2-year symptom-free period is almost never met.
- Implication for Chronic Conditions: For an autoimmune disease like Crohn's or Lupus, this means the condition itself, and any issues directly related to it, will almost certainly remain permanently excluded. However, new, unrelated acute conditions would be covered, provided they didn't have symptoms in the 5 years prior.
2. Full Medical Underwriting (FMU)
- How it Works: You declare your full medical history when you apply. The insurer then assesses your history and decides what they may cover or exclude. They may ask for a report from your GP.
- Implication for Chronic Conditions: With FMU, the insurer will explicitly list your autoimmune or chronic condition as an exclusion on your policy documents. This offers clarity from day one. You'll know precisely what is not covered. As with moratorium, new, unrelated acute conditions would be covered.
Key Table: Underwriting Types & Chronic Conditions
| Feature | Moratorium Underwriting | Full Medical Underwriting (FMU) |
|---|---|---|
| Initial Process | No detailed medical history required. | Full medical history declared upfront (may involve GP report). |
| Exclusions | Automatic exclusion of conditions with symptoms/treatment in last 5 years. | Specific exclusions listed on policy documents after assessment. |
| Clarity | Less clear initially; exclusions determined at claim stage. | Clear from the outset what is excluded. |
| Time to Get Cover | Faster to set up. | Slower to set up due to medical assessment. |
| Chronic Conditions | Will almost certainly remain excluded indefinitely (rarely meet 2-year symptom-free rule). | Will be explicitly excluded from policy inception. |
| Best For | Generally for those with minimal/no complex pre-existing conditions, or those who want quick setup. | Those with known pre-existing conditions who want upfront clarity on exclusions. |
Other Underwriting Considerations:
- Continued Personal Medical Exclusions (CPME): If you're switching insurers, and previously had FMU, CPME allows your new insurer to carry over your existing exclusions, potentially without a new moratorium period. This can be beneficial if your health has changed.
- Group Schemes: If you have health insurance through your employer, it's often on a "Medical History Disregarded" (MHD) basis. This is the most generous form of underwriting as it typically covers pre-existing conditions (but still usually excludes chronic conditions in terms of ongoing management, only covering acute flare-ups if deemed separate). However, MHD policies are usually only available through corporate schemes and not for individual policies.
WeCovr understands the nuances of these underwriting types and will discuss the best option for your specific circumstances, ensuring you grasp how your pre-existing conditions will be treated. WeCovr, sometimes working with broker partners, works with major insurers, comparing their approaches to ensure you get the most suitable cover.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Key Considerations When Buying PMI with a Chronic Condition
- Understand the Exclusions: Reiterate to yourself and confirm with your broker that your chronic condition and its direct complications will not be covered for ongoing management. Focus on the acute benefits.
- Choose the Right Underwriting: Discuss with us whether Moratorium or Full Medical Underwriting is better for your situation. FMU offers clarity.
- Check Mental Health Benefits: For many with chronic conditions, mental health support is crucial. Ensure the policy offers robust short-term mental health benefits.
- Consider Outpatient Limits: Most diagnostics (consultations, scans, blood tests) are outpatient. Ensure your policy has sufficient outpatient limits to cover potential investigations for new symptoms.
- Rehabilitation & Therapies: If you anticipate needing physiotherapy or other therapies for new injuries or acute issues, check these limits.
- Hospital Choice: Ensure the policy gives you access to a good network of hospitals and specialists close to you.
- Excess: This is the amount you pay towards a claim. A higher excess reduces your premium but means you pay more if you claim.
- No Claims Discount (NCD): Understand how making a claim might affect your NCD and subsequent premiums.
- Policy Terms & Conditions: Always read the fine print, especially sections on exclusions and definitions of chronic/pre-existing conditions. A WeCovr specialist or trusted broker partner can help clarify these.
The Cost of Private Health Insurance
The premium you pay for private health insurance is influenced by several factors:
- Age: Premiums generally increase with age, as the likelihood of needing medical care rises.
- Location: Healthcare costs can vary regionally, impacting premiums.
- Health History: While pre-existing chronic conditions are excluded, other aspects of your medical history (e.g., past acute conditions) can influence premiums if you opt for FMU.
- Level of Cover:
- Basic: Inpatient treatment only.
- Mid-range: Inpatient + some outpatient (consultations, diagnostics).
- Comprehensive: Inpatient + full outpatient, mental health, therapies, often international cover.
- Excess: A higher excess reduces the premium.
- Hospital List: Access to a wider range of hospitals (e.g., central London hospitals) increases costs.
- Add-ons: Optical, dental, travel cover etc., will increase the premium.
Typical Monthly Premiums (Illustrative - Highly Variable):
| Age Group | Basic Cover (£) | Mid-Range Cover (£) | Comprehensive Cover (£) |
|---|---|---|---|
| 20s | 30-50 | 45-70 | 60-100 |
| 30s | 40-65 | 60-90 | 80-130 |
| 40s | 50-80 | 75-120 | 100-180 |
| 50s | 70-120 | 100-180 | 150-250 |
| 60s | 100-180 | 150-250 | 200-350+ |
These figures are rough estimates and can vary significantly between insurers and specific policy features. It's crucial to get a personalised quote.
Making a Claim: What to Expect
The claims process is straightforward, provided you understand what is and isn't covered:
- GP Referral: For any new symptom or concern, consult your NHS GP first. They are your primary point of contact and will determine if a specialist referral is needed. Crucially, they must refer you to a private consultant if you intend to use your PMI.
- Contact Insurer: Once you have a private referral, contact your insurance provider (or WeCovr can assist) before proceeding. They will need details of your symptoms, the proposed specialist, and any recommended tests.
- Pre-Authorisation: The insurer will "pre-authorise" the claim if it falls within your policy's terms and is not a pre-existing or chronic exclusion. This means they confirm they may pay for the agreed treatment.
- Treatment: Attend your consultation, undergo diagnostics, or receive treatment as planned. The insurer typically pays the provider directly.
- Follow-up: For covered acute conditions, follow-up appointments and necessary rehabilitation will also be covered up to your policy limits.
What will not be covered during a claim:
- Any consultations, tests, or treatments directly related to your pre-existing autoimmune or chronic condition.
- Long-term drug therapies for chronic conditions.
- Routine monitoring or check-ups for chronic conditions.
- Experimental treatments not approved by the insurer.
The key is open communication with your insurer and clarity on the acute nature of the condition being treated.
The WeCovr Advantage: Your Expert Guide
Navigating the complexities of private health insurance, especially when you have a pre-existing or chronic condition, can feel overwhelming. With so many insurers, policy types, underwriting methods, and nuanced exclusions, it's easy to make a choice that doesn't fully meet your needs or expectations.
This is where a WeCovr specialist or trusted broker partner can help. As modern UK health insurance broker, WeCovr, sometimes working with broker partners, specialises in simplifying this process for you. Here's how we help:
- Expert Guidance: We possess in-depth knowledge of the UK private health insurance market. We understand the specific challenges faced by individuals with autoimmune and complex chronic conditions. We'll clearly explain what is and isn't covered, setting realistic expectations from the start.
- Whole-Market Access: We compare policies from all major UK health insurance providers. This means we can scour the market to find the plans that best align with your unique health profile and budget, highlighting the specific benefits relevant to someone managing a chronic condition (e.g., strong outpatient and mental health components).
- Personalised Recommendations: We don't believe in one-size-fits-all solutions. We take the time to understand your individual circumstances, current health status, and priorities to recommend the most suitable policy.
- No Separate Broker Fee: Our service has no separate broker fee for you. We are remunerated by the insurance providers, ensuring you get regulated advice without any hidden fees.
- Claims Support (Where Applicable): While we primarily help with finding and setting up your policy, we can offer guidance on the claims process and help liaise with your insurer if you encounter any difficulties, ensuring a smoother experience.
Our goal is to empower you to make an informed decision, ensuring you get the most out of your private health insurance, even with the complexities of autoimmune and chronic conditions. We help you understand how PMI acts as a powerful complement to your NHS care, providing invaluable faster access (where available) when you need it most.
Conclusion: Empowering Your Healthcare Journey
Living with an autoimmune or complex chronic condition is a lifelong journey. While the NHS remains the cornerstone of long-term management, the reality of increasing waiting times for diagnostics and specialist consultations can add significant stress and uncertainty.
Private health insurance, despite its limitations regarding chronic condition coverage, offers a powerful strategic tool. It provides faster access (where available) pathways to specialist consultations, advanced diagnostics, and acute treatment for new symptoms or unrelated acute conditions. It can be a vital accelerant in your healthcare journey, offering clarity, speed, and peace of mind when facing new health challenges.
By understanding the clear distinction between chronic and acute conditions, and by leveraging the benefits of rapid diagnostics and access to mental health support, you can strategically use PMI to complement your NHS care. This dual approach can lead to more timely interventions, reduced anxiety, and ultimately, a better quality of life.
Don't navigate this complex landscape alone. Let WeCovr guide you through the options, helping you find a private health insurance policy that truly empowers your healthcare journey, ensuring you're prepared for the unexpected, even while managing the expected.
Sources
- NHS England: Waiting times and referral-to-treatment statistics.
- Office for National Statistics (ONS): Health, mortality, and workforce data.
- NICE: Clinical guidance and technology appraisals.
- Care Quality Commission (CQC): Provider quality and inspection reports.
- UK Health Security Agency (UKHSA): Public health surveillance reports.
- Association of British Insurers (ABI): Health and protection market publications.
Important Information and Risks
No advice: This article is for general information only. It is not financial, legal, insurance, or tax advice, and it is not a personal recommendation. WeCovr does not assess your individual circumstances or recommend a specific product through this article.
Policy exclusions and underwriting: Insurance policies, including life insurance, private medical insurance, critical illness cover, and income protection, are subject to insurer underwriting, eligibility, acceptance criteria, terms, conditions, limits, and exclusions. Pre-existing medical conditions may be excluded, restricted, or accepted on special terms unless an insurer confirms otherwise in writing.
Tax treatment: References to tax treatment, HMRC rules, or business reliefs are based on current UK legislation and guidance, which can change. Tax treatment depends on your personal or business circumstances and may differ from examples in this article.
Before you buy: Always read the Insurance Product Information Document (IPID), policy summary, and full policy terms before buying, renewing, changing, or keeping cover. If you are unsure whether a policy is suitable for you, speak to an insurance adviser.
Compare private health insurance quotes from leading UK insurers
Answer a few quick questions and a specialist from WeCovr or one of its broker partners will help you compare cover from insurers such as Bupa, AXA, Aviva and Vitality. No obligation.
Takes about 2-3 minutes
Compare cover from leading UK insurers
No obligation to buy
Get a quote
Get a private health insurance quote
Answer a few questions, then a specialist helps you compare cover and prices.
Tell us who needs cover
Just you, a partner, your family or your staff.
Compare your options
A specialist compares cover and prices from leading UK insurers.
Decide in your own time
There is no obligation to buy.
What you get
A specialist from WeCovr or one of its broker partners
Options compared across leading UK insurers
No obligation to buy