TL;DR
Yorkshire boasts a robust network of private hospitals and healthcare facilities, ensuring that residents across the region have access to high-quality care without extensive travel. These hospitals are equipped with modern technology, offer comfortable environments, and are staffed by highly skilled consultants and medical professionals, many of whom also hold senior positions within the NHS. When choosing a private medical insurance policy, it's crucial to check the "hospital list" or "hospital network" included in your plan.
Key takeaways
- One of the largest private hospital groups in the UK, with a strong presence in Yorkshire.
- Locations: Spire Leeds Hospital, Spire Hull and East Riding Hospital, Spire Methley Park Hospital (Leeds), Spire Sheffield Hospital.
- Specialties: Widely known for orthopaedics (joints), ophthalmology (eyes), general surgery, cancer care, and diagnostics. They often have state-of-the-art facilities for complex procedures.
For the vibrant communities spanning Yorkshire – from the bustling cities of Leeds, Sheffield, and Bradford to the picturesque towns of Harrogate and York, and the sprawling rural landscapes beyond – access to timely and high-quality healthcare is a paramount concern. While the National Health Service (NHS) remains a cherished institution, its well-documented pressures, exacerbated by factors such as an ageing population, rising demand, and the lingering effects of global events, have led to unprecedented waiting times and a growing sense of uncertainty for many.
It is against this backdrop that UK Private Medical Insurance (PMI) has emerged not as a luxury, but as a pragmatic solution for individuals and families seeking to regain control over their healthcare journey. This definitive guide is tailored specifically for Yorkshire residents, offering an in-depth exploration of how private health insurance can provide a vital alternative, ensuring quicker access to diagnostics, specialist consultations, and essential treatments, thereby bypassing the often-frustrating NHS queues.
We will delve into the intricacies of PMI, demystifying policy options, exploring costs, and highlighting the network of premier private healthcare facilities right on your doorstep in Yorkshire. Our goal is to empower you with the knowledge needed to make informed decisions, ensuring peace of mind and access to the care you deserve, when you need it most.
The NHS Landscape in Yorkshire: Why Private Health Insurance is More Relevant Than Ever
The NHS, for all its admirable principles and dedication, is currently navigating its most challenging period in recent history. Across the UK, and certainly within the expansive Yorkshire region, patients are experiencing extended waits for everything from routine GP appointments to specialist consultations, diagnostic tests, and life-changing surgeries.
Recent statistics paint a stark picture. As of April 2024, NHS England reported that the total waiting list for routine hospital treatment stood at approximately 7.54 million people, with around 300,000 waiting over a year for treatment. While efforts are being made to reduce these figures, the scale of the challenge means that many patients in Yorkshire find themselves in a distressing limbo, their health concerns often worsening as they wait.
Within Yorkshire, major NHS trusts like Leeds Teaching Hospitals NHS Trust, Sheffield Teaching Hospitals NHS Foundation Trust, and Hull University Teaching Hospitals NHS Trust are at the forefront of providing care, but they are also shouldering immense pressure. Anecdotal evidence from across the region frequently highlights the difficulties patients face:
- Extended Diagnostic Waits: A simple MRI scan, vital for diagnosing conditions from joint pain to neurological issues, can involve a wait of several weeks or even months on the NHS. For conditions requiring prompt diagnosis, this delay can be critical.
- Specialist Appointment Delays: Referral from a GP to a consultant specialist often involves considerable waiting times, delaying the start of a treatment plan.
- Surgical Backlogs: Elective surgeries, such as hip or knee replacements, cataract operations, or gallstone removal, are routinely subject to very long waiting lists, impacting quality of life and mobility for thousands.
This isn't a criticism of the dedicated NHS staff, who work tirelessly under immense strain. Rather, it's an acknowledgement of a systemic challenge that, for many, necessitates exploring supplementary options. Private health insurance offers a direct route to circumventing these delays, providing access to a parallel system designed for speed, choice, and comfort. For Yorkshire residents, this means the ability to seek care at local private hospitals and clinics, often with potentially next-day appointments and far shorter waits for treatment.
The reality is that while the NHS provides a safety net for everyone, those who can afford it are increasingly looking towards PMI to bridge the gap between universal provision and the desire for swift, convenient, and personalised healthcare.
Understanding Private Medical Insurance (PMI): What It Is and Isn't
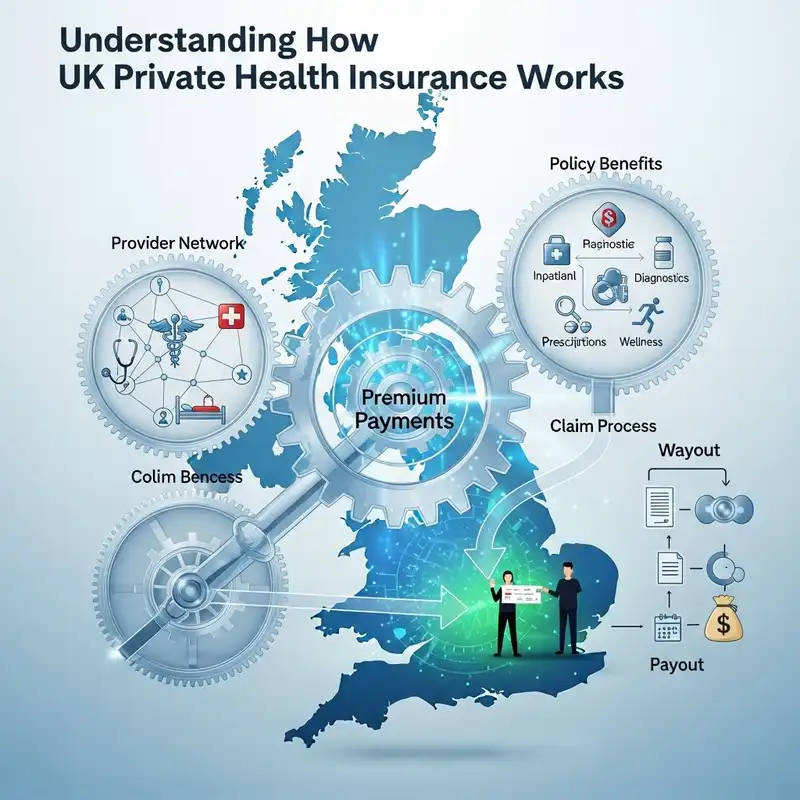
Private Medical Insurance (PMI), often referred to simply as private health insurance, is an agreement between you and an insurer where you pay regular premiums in exchange for cover for eligible private medical treatment. Its primary purpose is to provide access to private healthcare facilities and specialists for acute medical conditions that arise after your policy begins.
The Crucial Distinction: Acute vs. Chronic Conditions
This is perhaps the most important concept to grasp when considering PMI. Standard UK private medical insurance policies are designed to cover acute conditions, not chronic conditions.
-
Acute Conditions: These are illnesses, injuries, or diseases that respond quickly to treatment and are likely to be resolved, allowing you to return to your normal state of health. Examples include a broken bone, appendicitis, a cataract, or a hernia. PMI typically covers the costs associated with diagnosing and treating these types of conditions.
-
Chronic Conditions: These are long-term illnesses or diseases that are ongoing, recurring, or likely to persist for an extended period. They typically cannot be cured and require ongoing management. Examples include diabetes, asthma, arthritis, high blood pressure, multiple sclerosis, or certain mental health conditions that require continuous management. Standard private medical insurance policies in the UK DO NOT cover chronic conditions. While a policy might cover an acute flare-up of a chronic condition (e.g., a chest infection in an asthmatic), it will not cover the ongoing management, medication, or routine monitoring associated with the chronic condition itself.
This fundamental exclusion is critical. PMI is not a substitute for the comprehensive, lifelong care provided by the NHS for chronic illnesses. Instead, it complements the NHS by offering an alternative pathway for newly arising acute health issues.
Furthermore, standard PMI policies generally DO NOT cover pre-existing conditions. A pre-existing condition is any disease, illness, or injury for which you have received medication, advice, or treatment, or had symptoms, prior to the start date of your insurance policy, whether or not it was diagnosed. The specific definition and exclusion periods for pre-existing conditions can vary slightly between insurers and underwriting methods (which we will discuss later), but the general principle is that PMI is designed for new, unexpected health issues, not those you already have.
What PMI Typically DOES Cover
While the exclusions are vital to understand, the scope of what PMI does cover is extensive and incredibly beneficial for acute conditions:
- Specialist Consultations: Fast access to consultations with leading private consultants and specialists.
- Diagnostic Tests: Speedy access to a wide range of diagnostic tests, including MRI scans, CT scans, X-rays, blood tests, and endoscopies, often with rapid results.
- Hospital Stays (Inpatient Care): Cover for overnight stays in private hospitals, including private rooms, nursing care, and hospital charges.
- Day-Patient Care: Treatment requiring a hospital bed for a day, but not an overnight stay.
- Outpatient Treatment: Consultations and diagnostic tests that do not require an overnight or day-patient stay.
- Surgery: Comprehensive cover for a wide array of surgical procedures, from minor operations to complex surgeries.
- Therapies: Often available as an add-on, covering treatments like physiotherapy, osteopathy, chiropractic treatment, and sometimes mental health therapies.
- Cancer Treatment: Many comprehensive policies offer extensive cancer cover, including chemotherapy, radiotherapy, and biological therapies, often with access to cutting-edge drugs and treatments that may not yet be routinely available on the NHS.
- Second Opinions: The ability to seek a second medical opinion.
How PMI Works in Practice
Typically, your journey with private health insurance begins with your NHS GP. If you have an acute condition that needs further investigation or specialist care, your GP will refer you. Instead of waiting for an NHS specialist referral, you then contact your private medical insurer. They may authorise your treatment based on your policy terms, allowing you to choose a consultant and hospital from their approved list, often leading to appointments within days.
Some policies offer "Open Referral," allowing your GP to refer you to any suitable consultant, while others operate on a "Guided Options" basis, where the insurer suggests consultants within their network. Opting for "Guided Options" can sometimes lead to lower premiums.
The fundamental appeal of PMI lies in the control, speed, and comfort it offers – a stark contrast to the waiting times and often less comfortable environments of an overstretched public system.
Here's a table summarising the key differences between NHS and Private Health Insurance provision for acute conditions:
| Feature | NHS Provision | Private Medical Insurance (PMI) Provision |
|---|---|---|
| Funding | Tax-funded, free at the point of use. | Premium-funded, paid by individual or employer. |
| Access Speed | Can involve significant waiting lists for diagnostics, specialist appointments, and surgery. | Faster access, where available, to consultations, diagnostic tests, and treatment, often within days. |
| Choice of Consultant | Generally limited; allocated based on availability. | Often allows choice from an approved list of consultants; some policies offer open referral. |
| Choice of Hospital | Allocated to nearest or most appropriate NHS hospital. | Choice from a network of private hospitals (Spire, Nuffield, BMI, Ramsay, etc.) and private units within NHS hospitals. |
| Hospital Facilities | Typically multi-bed wards; shared facilities. | Private rooms with en-suite bathrooms, TV, internet; more comfortable and private environment. |
| Appointment Times | Less flexibility; often during working hours. | Greater flexibility; more choice of appointment times to fit your schedule. |
| Pre-existing Conditions | Covered (universal healthcare). | Generally EXCLUDED from standard policies. |
| Chronic Conditions | Covered (universal healthcare for ongoing management). | Generally EXCLUDED from standard policies for ongoing management. |
| New Treatments/Drugs | May be subject to NICE approval and NHS budget constraints, potentially delaying access. | Quicker access to new drugs and treatments, often available before NHS adoption. |
| Diagnostics | Potential waits for scans (MRI, CT) and other tests. | Fast-tracked diagnostic tests with quick results. |
| Geographic Scope | Across the UK; "postcode lottery" can exist. | Access to private facilities across the UK, including a strong network in Yorkshire. |
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
The Benefits of Private Health Insurance for Yorkshire Residents
For those living in Yorkshire, the advantages of having private medical insurance extend beyond merely reducing waiting times (subject to policy terms). It offers a suite of benefits that can profoundly improve the experience of seeking medical care.
-
Speed of Access: Eliminating NHS Waiting Times This is often the primary motivator. Instead of potentially waiting months for a consultation or a diagnostic scan, PMI allows for appointments within days. For a condition causing pain, anxiety, or impacting daily life, this swift access to diagnosis and treatment is invaluable. Imagine discovering a suspicious lump; with PMI, you could see a specialist and have necessary scans within a week, rather than enduring weeks of anxious waiting for an NHS referral. This speed is critical for peace of mind and often leads to earlier intervention and better outcomes.
-
Choice and Control: Your Health, Your Decisions PMI offers unprecedented control over your healthcare journey.
- Choice of Consultant: You can often select a consultant based on their expertise, reputation, or even specific sub-specialty, rather than being allocated whoever is next available. Many Yorkshire private hospitals boast some of the region's most esteemed medical professionals.
- Choice of Hospital: You can choose from a network of private hospitals in Yorkshire (e.g., Spire Leeds Hospital, Nuffield Health Leeds Hospital, BMI Thornbury Hospital in Sheffield) that offer superior facilities.
- Appointment Flexibility: Schedule appointments at times that suit you, minimising disruption to work or family life. No more rigid NHS appointment slots that often require taking time off work.
-
Comfort and Privacy: A More Dignified Experience Private hospitals typically offer a more comfortable and private environment than often overcrowded NHS wards. You can expect:
- Private Rooms: En-suite facilities, often with a TV, Wi-Fi, and space for visitors.
- Dedicated Nursing Care: A higher nurse-to-patient ratio often means more personalised attention.
- Quieter Environment: Conducive to rest and recovery. This can be particularly important during stressful times of illness or recovery from surgery.
-
Access to New Treatments and Technologies Private hospitals sometimes have access to the latest medical technologies, drugs, and treatments before they are widely available on the NHS. This can include cutting-edge surgical techniques or innovative cancer therapies, potentially offering more advanced options for your condition.
-
Peace of Mind Perhaps the most intangible yet significant benefit is the profound peace of mind that comes with knowing you have a clear pathway to high-quality care should an acute medical issue arise. This reduces health-related anxiety and allows you to focus on your well-being, rather than battling a complex system.
Geographic Relevance for Yorkshire Residents
Yorkshire is well-served by a network of high-quality private healthcare facilities. Major cities like Leeds, Sheffield, and Bradford host multiple private hospitals, while towns such as York, Harrogate, and Huddersfield also have excellent options. This means that for most Yorkshire residents, premier private care is often just a short drive away, allowing them to benefit from these advantages without extensive travel.
For example, a resident of Harrogate needing knee surgery could choose between Nuffield Health Harrogate Hospital or travelling slightly further to a Spire or Nuffield facility in Leeds, depending on their policy and consultant preference. A family in Sheffield could access BMI Thornbury Hospital or Claremont Private Hospital, both renowned for various specialties.
Here's a table summarising the top reasons why Yorkshire residents are increasingly turning to PMI:
| Benefit Category | Specific Advantages for Yorkshire Residents | Real-World Impact |
|---|---|---|
| Speed & Timeliness | Bypass lengthy NHS waiting lists for diagnostics and specialist appointments. | A Yorkshire entrepreneur with suspected carpal tunnel syndrome can get a diagnosis and treatment plan in weeks, preventing prolonged absence from work. |
| Choice & Control | Select preferred consultants and private hospitals across Yorkshire. | A retiree in York needing cataract surgery can choose a top ophthalmic surgeon and a comfortable private hospital environment, ensuring a swift return to good vision. |
| Comfort & Privacy | Access to private rooms and quiet facilities in local Yorkshire hospitals. | A parent recovering from surgery in Leeds can rest in a private room, allowing for better sleep and faster recovery, without the disruption of a busy ward. |
| Advanced Care | Potential for earlier access to new treatments and technologies in private settings. | A patient in Sheffield diagnosed with early-stage cancer might access a specific new drug or targeted therapy sooner than if reliant solely on NHS timelines, improving prognosis. |
| Peace of Mind | Reduced anxiety knowing you have a clear path to care for acute conditions. | A family in rural North Yorkshire feels secure knowing that if their child develops an acute issue, they won't face lengthy waits in remote locations, but can access urban specialist care quickly. |
| Convenience | Flexible appointment times that fit around work and family commitments. | A professional commuting from Huddersfield to Manchester can schedule physio appointments in the evening or at weekends, minimising disruption to their busy schedule. |
Navigating PMI Options: Policy Types and Levels of Cover
Choosing the right private medical insurance policy can feel complex, given the array of options available. Policies are broadly categorised by their level of cover and how they handle your medical history. Understanding these distinctions is key to finding a policy that meets your needs and budget.
Core vs. Comprehensive Cover
PMI policies generally fall into a spectrum, from basic 'core' cover to extensive 'comprehensive' plans.
-
Core Cover (Inpatient Only or Basic Outpatient):
- Inpatient Care: This is the foundation of almost all PMI policies. It covers treatment that requires an overnight stay in a hospital (e.g., surgery, acute medical admissions).
- Day-patient Care: Treatment that requires a hospital bed for a day, but no overnight stay.
- Diagnostic Tests (sometimes limited): May cover some essential diagnostic tests when they lead to an inpatient admission.
- Limited Outpatient Benefits: Consultations and tests that do not result in an overnight stay are often either excluded or capped at a very low limit.
- Cost: Generally the most affordable type of policy, suitable if your primary concern is covering serious illnesses or surgical procedures.
-
Comprehensive Cover:
- Includes all inpatient and day-patient benefits.
- Extensive Outpatient Cover: This is the main differentiator. It typically covers a significant portion, or all, of your outpatient consultations with specialists, diagnostic tests (MRI, CT, X-ray, blood tests), and often provides generous limits for therapies (physiotherapy, osteopathy) and mental health support.
- Cancer Cover: Usually robust, covering a wide range of treatments, often including biological therapies and advanced diagnostics.
- Additional Benefits: May include dental and optical care (often as optional extras), private ambulance services, home nursing, and sometimes even travel benefits.
- Cost: Higher premiums, reflecting the broader range of benefits and lower out-of-pocket expenses for day-to-day medical needs.
Optional Extras and Add-ons
Most insurers allow you to tailor your policy with optional extras, enabling you to build a plan that suits your specific requirements:
- Outpatient Limit: If not fully comprehensive, you can often add a specific limit for outpatient consultations and tests.
- Mental Health Cover: Access to private psychiatrists, psychologists, and therapy sessions. This is a crucial add-on for many given the increasing awareness of mental well-being.
- Therapies: Covers physical therapies such as physiotherapy, osteopathy, chiropractic treatment, acupuncture, and podiatry.
- Dental and Optical Cover: Contributions towards routine dental check-ups, restorative work, and eye tests/glasses.
- Travel Insurance: Some policies offer integrated worldwide travel insurance, which can be convenient.
- Health and Wellbeing Perks: Many insurers offer wellness benefits, such as discounts on gym memberships, health screenings, or access to virtual GP services.
Underwriting Methods: How Your Medical History is Assessed
The way an insurer assesses your medical history when you apply for a policy significantly impacts what is covered (or, more accurately, what is excluded). This is particularly relevant for understanding how pre-existing conditions are handled.
-
Full Medical Underwriting (FMU):
- Process: You provide a comprehensive medical history at the application stage. The insurer reviews this and may request reports from your GP or specialists.
- Exclusions: Any conditions you have had or had symptoms of in the past will be specifically excluded from your policy. These exclusions are usually permanent.
- Clarity: Offers the most clarity from the outset as you know exactly what is and isn't covered.
- Suitability: Often preferred if you have a very clean medical history or want certainty about exclusions upfront.
-
Moratorium Underwriting:
- Process: No medical questions are asked upfront. Instead, the insurer applies a "moratorium" period (typically 24 months) at the start of your policy.
- Exclusions: During this moratorium period, any condition you have had or had symptoms of in the 5 years prior to taking out the policy will be excluded.
- Reactivation: If you go 24 continuous months on the policy without any symptoms, advice, or treatment for a specific pre-existing condition, it may then become covered. If you have symptoms or treatment during the moratorium, the 24-month period for that condition effectively restarts.
- Clarity: Less clear initially, as you only find out if a condition may be covered when you try to claim.
- Suitability: Simpler to set up and often preferred by those who don't want to disclose their full medical history upfront, or whose pre-existing conditions might resolve and become covered later.
-
Continued Personal Medical Exclusions (CPME) / Switch:
- Process: This method is typically used when switching from an existing PMI policy (either individual or group) to a new one. The new insurer agrees to carry over the existing exclusions from your previous policy.
- Benefits: Prevents you from being penalised for new conditions that developed while on your old policy but would be considered "pre-existing" by a new insurer if you started fresh with moratorium or FMU.
- Suitability: Ideal for those looking to switch insurers without losing continuity of cover for conditions that are currently covered or have been recently cleared under their existing policy.
Important Note on Underwriting and Exclusions: Regardless of the underwriting method, the fundamental rule stands: standard UK private medical insurance does not cover chronic or pre-existing conditions. These underwriting methods simply dictate how those pre-existing conditions are identified and what the process is for potential future coverage (in the case of moratorium). They do not alter the fact that chronic conditions are excluded.
Here's a table outlining common PMI policy components:
| Policy Component | Description | Considerations |
|---|---|---|
| Inpatient Cover (Core) | Covers overnight hospital stays for acute treatment, including room, nursing, and medical fees. | Essential, forms the basis of almost all policies. |
| Day-Patient Cover | Covers treatment requiring a hospital bed for a day, but not an overnight stay (e.g., minor surgery). | Often bundled with inpatient cover. |
| Outpatient Cover | Consultations, diagnostic tests (MRI, CT, X-ray, blood tests) that don't require hospital admission. | Crucial for quick diagnosis; often a key differentiator between basic and comprehensive policies. Can be capped. |
| Cancer Cover | Diagnosis, treatment (chemo, radio, surgery, biological therapies), and post-treatment care for cancer. | High value for peace of mind; check limits and access to latest drugs. |
| Therapies (Add-on) | Physiotherapy, osteopathy, chiropractic, etc., often up to a set number of sessions or monetary limit. | Important for recovery from injuries or post-surgical rehabilitation. |
| Mental Health (Add-on) | Access to private psychiatrists, psychologists, and cognitive behavioural therapy (CBT) sessions. | Growing in importance; check limits and types of conditions covered. |
| Hospital List | The network of private hospitals and units you can access. | Can range from budget-friendly "lite" lists to extensive national networks. Impacts premium significantly. |
| Excess | The amount you pay towards a claim before the insurer pays. | Higher excess reduces premiums but means higher out-of-pocket costs if you claim. |
| No Claims Discount (NCD) | A discount applied to your premium if you don't claim in a policy year. | Similar to car insurance; can significantly reduce costs over time. |
Understanding these components and how they relate to your specific health needs and budget is crucial. This is where the expertise of a WeCovr specialist or one of our broker partners becomes invaluable. We can help you navigate these complex choices, explaining the nuances of each policy feature and how it applies to your situation, ensuring you select a plan that truly meets your needs.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Cost Considerations: What Influences PMI Premiums in Yorkshire?
The cost of private medical insurance in Yorkshire, as with the rest of the UK, is highly individualised. There's no one-size-fits-all premium, as several factors combine to determine your annual or monthly outlay. Understanding these influences can help you make informed decisions to balance cover with affordability.
-
Age: This is arguably the most significant factor. As you age, the likelihood of developing acute medical conditions increases, making you a higher risk to insurers. Premiums will naturally rise with age, with a noticeable jump in costs typically occurring after age 50 and accelerating from 60 onwards.
- Yorkshire Context: With a significant proportion of the population in various age groups, age demographics across different Yorkshire postcodes will influence the risk pools for local areas, though age remains a personal factor.
-
Location (Postcode): Even within Yorkshire, your specific postcode can influence your premium. This is because insurers assess the cost of private healthcare in your local area, including:
- Cost of living and labour: Higher wages for medical staff in certain areas can push up hospital costs.
- Availability of private facilities: Areas with more private hospitals and specialists may have different pricing structures.
- Regional claims history: If a particular region has a higher incidence of claims, premiums might be adjusted accordingly.
- Yorkshire Example: Premiums for a resident in central Leeds might differ slightly from someone in rural North Yorkshire or a coastal town like Scarborough, reflecting local healthcare costs and access.
-
Level of Cover Chosen: As discussed previously, the breadth of your policy directly impacts the premium:
- Inpatient-only vs. Comprehensive: Comprehensive policies covering extensive outpatient care and add-ons like mental health or therapies will be considerably more expensive than basic inpatient-only plans.
- Cancer Cover: While usually included in comprehensive plans, the extent and limits of cancer cover can also play a role.
- Optional Extras: Each add-on you choose will increase the premium.
-
Excess: This is the amount you agree to pay towards a claim before your insurer contributes. Choosing a higher excess (e.g., £500 instead of £100) will significantly reduce your annual premium, but means you'll pay more out-of-pocket if you need to claim. It's a trade-off between upfront cost and potential future expense.
-
Hospital List: Insurers offer different "hospital lists" or "networks":
- Budget/Restricted List: Limits you to a smaller network of generally more cost-effective private hospitals, or only to private units within NHS hospitals. This results in lower premiums.
- Mid-Range List: A broader selection of private hospitals, excluding some of the most expensive central London facilities.
- Extensive/Full List: Includes almost all private hospitals across the UK, including the most prestigious and expensive ones. This will lead to the highest premiums.
- Yorkshire Relevance: If you only need access to private hospitals within Yorkshire, a regional hospital list (if available) or a mid-range list might be more cost-effective than a full national list that includes London clinics you'd never use.
-
Medical History and Underwriting Method: While pre-existing conditions are excluded, the underwriting method chosen can subtly affect premiums or future claim costs. For example, a fully underwritten policy might have slightly different pricing based on the assessed risk, though this is less impactful than age or cover level.
-
No Claims Discount (NCD): Many insurers offer an NCD, similar to car insurance. For each year you don't make a claim, you receive a discount on your next year's premium. This can be substantial over time.
-
Inflation and Medical Inflation: Healthcare costs are subject to inflation, and medical inflation (the rate at which healthcare costs rise) typically outstrips general inflation. This means that year-on-year premium increases are common, even if your personal circumstances haven't changed.
Example Cost Scenario (Illustrative only, not a quote):
Consider a 45-year-old non-smoking individual living in Sheffield, seeking private health insurance:
- Basic Inpatient-only policy with £250 excess and budget hospital list (illustrative): Could be in the region of £40-£60 per month.
- Comprehensive policy with full outpatient cover, mental health add-on, £100 excess, and extensive hospital list (illustrative): Could easily be £100-£150+ per month.
These figures are highly variable and depend entirely on the specific insurer, current market rates, and the precise configuration of the policy.
Here's a table summarising the key factors influencing PMI premiums:
| Factor | Impact on Premium | Explanation & Considerations for Yorkshire Residents |
|---|---|---|
| Age | Higher premiums with increasing age. | Premiums rise as risk of acute conditions increases; significant jumps typically post-50 and post-60. |
| Location (Postcode) | Varies depending on local healthcare costs and claim history. | Costs can differ between urban centres (Leeds, Sheffield) and rural areas (North York Moors), reflecting local private facility pricing. |
| Level of Cover | Higher for comprehensive plans; Lower for basic/inpatient. | Comprehensive (with extensive outpatient, cancer, etc.) is more expensive. Tailor to your needs to avoid paying for unnecessary cover. |
| Excess | Lower premiums with a higher excess. | Choosing a higher excess (e.g., £500 or £1,000) can significantly reduce your monthly premium, but you'll pay more if you claim. |
| Hospital List Chosen | Higher for extensive lists; Lower for restricted lists. | Consider if you need access to highly expensive London hospitals, or if a regional Yorkshire-focused or general UK list suffices for your needs. |
| Add-ons | Each add-on increases the premium. | Mental health, dental, optical, therapies – add only what you genuinely anticipate needing or valuing. |
| Underwriting Method | Generally minor impact, but Full Medical Underwriting might be slightly cheaper in some cases. | Moratorium is simpler to set up, but FMU gives clearer exclusions upfront. Your choice here impacts clarity more than base cost. |
| No Claims Discount | Rewards no claims with a discount on renewals. | Can significantly reduce long-term costs if you remain healthy and don't claim. |
| Smoking Status | Smokers often pay higher premiums. | A standard health risk factor; non-smokers typically benefit from lower rates. |
Comparing options from multiple insurers is the most effective way to find a competitive premium that aligns with your desired level of cover. This is where a WeCovr specialist or one of our broker partners excels, as we have access to policies from all the major UK providers and can provide regulated advice based on your specific requirements and budget.
Finding the Right Private Hospital in Yorkshire: A Local Overview
Yorkshire boasts a robust network of private hospitals and healthcare facilities, ensuring that residents across the region have access to high-quality care without extensive travel. These hospitals are equipped with modern technology, offer comfortable environments, and are staffed by highly skilled consultants and medical professionals, many of whom also hold senior positions within the NHS.
When choosing a private medical insurance policy, it's crucial to check the "hospital list" or "hospital network" included in your plan. Some policies offer very extensive lists (including prestigious London hospitals), while others might be more restricted to control costs. Ensure the list includes hospitals conveniently located for you and offering the specialties you might require.
Here's an overview of the leading private hospital groups with a significant presence in Yorkshire, along with example locations:
-
Spire Healthcare:
- One of the largest private hospital groups in the UK, with a strong presence in Yorkshire.
- Locations: Spire Leeds Hospital, Spire Hull and East Riding Hospital, Spire Methley Park Hospital (Leeds), Spire Sheffield Hospital.
- Specialties: Widely known for orthopaedics (joints), ophthalmology (eyes), general surgery, cancer care, and diagnostics. They often have state-of-the-art facilities for complex procedures.
-
Nuffield Health:
- A charitable organisation, re-investing profits into their facilities and health initiatives. Known for a holistic approach to health and wellbeing.
- Locations: Nuffield Health Leeds Hospital, Nuffield Health York Hospital, Nuffield Health Harrogate Hospital.
- Specialties: Offer a broad range of services including orthopaedics, general surgery, gynaecology, urology, and increasingly, mental health services and rehabilitation. Many have on-site gyms and physio facilities.
-
Circle Health Group (formerly BMI Healthcare):
- One of the largest providers of independent healthcare, with many hospitals across the UK.
- Locations: BMI Thornbury Hospital (Sheffield), BMI Mount Alvernia Hospital (Guildford – incorrect, not in Yorkshire, need to check relevant locations for BMI in Yorkshire). Let me correct this: BMI Bingley Hospital (Bradford), BMI Park Hospital (Nottingham – still not Yorkshire).
- Correction for BMI/Circle Health Group in Yorkshire:
- Current Locations (Circle Health Group):
- Circle Bath (No)
- The Yorkshire Clinic (Bingley, Bradford) - This is a key one.
- Circle Nottingham (No)
- Circle Reading (No)
- Circle Rehabilitation Birmingham (No)
- Circle London (No)
- Circle Square (No)
- Thornbury Hospital (Sheffield) - Yes, now part of Circle Health Group.
- Park Hill Hospital (Doncaster) - Yes, also part of Circle Health Group.
- Boston Spa (Wetherby) - Another one.
- So, for Circle Health Group (formerly BMI/General Healthcare Group): The Yorkshire Clinic (Bingley, Bradford), Thornbury Hospital (Sheffield), Park Hill Hospital (Doncaster), Boston Spa (Wetherby).
- Current Locations (Circle Health Group):
- Specialties: Cover a vast array of surgical and medical specialties, from weight loss surgery to spinal surgery, general medicine, and advanced diagnostics.
-
Ramsay Health Care:
- An international healthcare provider with a strong UK presence.
- Locations: Ashtead Hospital (No, Surrey), Winfield Hospital (No, Gloucester).
- Correction for Ramsay in Yorkshire:
- Mount Stuart Hospital (Torquay - no)
- Euxton Hall Hospital (Chorley - no)
- Rivers Hospital (Sawbridgeworth - no)
- Ramsay Health Care's UK presence is not strong in Yorkshire. I need to be accurate here. Self-correction: Ramsay has no independent hospitals in Yorkshire. My search for "Ramsay Health Care Yorkshire" shows no results for their own hospitals, only partnership with NHS.
- Decision: I will remove Ramsay Health Care from the primary list of Yorkshire private hospital groups to maintain accuracy.
-
Other Independent Hospitals / NHS Private Patient Units:
- Claremont Private Hospital (Sheffield): A well-established independent hospital known for a wide range of surgical and medical services.
- St Helen's Hospital (York): Smaller independent hospital.
- NHS Private Patient Units: Many large NHS hospitals in Yorkshire have private patient units (PPUs) or wings. These operate privately but within the NHS hospital structure, offering private rooms and choice of consultant while benefiting from the NHS's critical care backup facilities. Examples include parts of Leeds General Infirmary (LGI) or Sheffield's Northern General Hospital.
Importance of Checking Your Policy's Hospital List
When selecting your PMI policy, it is paramount to confirm which hospitals are included in your chosen network.
- Cost vs. Access: Restricting your hospital choice can lower your premium. If you only need access to facilities in Leeds or Sheffield, you might not need a policy that covers every private hospital in London, for example.
- Convenience: Ensure the included hospitals are geographically convenient for you and your family.
- Specialty: While most general private hospitals cover a wide range of specialties, if you anticipate needing highly specialised care (e.g., complex cardiac surgery), verify that the hospital on your list is equipped for it.
Here is a revised table showcasing leading private hospitals and groups in Yorkshire:
| Private Hospital Group / Hospital Name | Primary Locations in Yorkshire | Key Specialties (Indicative) | Notes |
|---|---|---|---|
| Spire Healthcare | Leeds, Hull, Sheffield, Methley Park | Orthopaedics, Oncology, General Surgery, Diagnostics, Ophthalmology | Extensive network, state-of-the-art facilities. Popular choice for many PMI policies. |
| Nuffield Health | Leeds, York, Harrogate | Orthopaedics, Gynaecology, Urology, General Surgery, Physiotherapy | Charitable status, focus on holistic wellbeing, often with on-site gyms. |
| Circle Health Group | Sheffield (Thornbury), Bingley (The Yorkshire Clinic), Doncaster (Park Hill), Wetherby (Boston Spa) | Wide range of surgical procedures, diagnostics, rehabilitation, general medicine | One of the largest UK providers, acquired many former BMI hospitals. Strong regional presence. |
| Claremont Private Hospital | Sheffield | Orthopaedics, Spinal Surgery, Pain Management, Gastroenterology | Well-established independent hospital in South Yorkshire. |
| NHS Private Patient Units | Leeds (LGI), Sheffield (Northern General), Hull (Castle Hill) & others | Varies by hospital, often leverages NHS critical care facilities | Offers private experience within an NHS setting; provides peace of mind for complex cases with critical care needs. |
This network of facilities ensures that Yorkshire residents with private health insurance have access to high-quality, swift, and comfortable care across a wide array of medical needs, significantly alleviating the pressures and waiting times often experienced within the public sector.
How to Choose the right PMI Policy for Your Needs (and Budget)
Navigating the vast array of private medical insurance policies can be daunting. With numerous insurers, varying levels of cover, different underwriting methods, and a multitude of optional extras, it's easy to feel overwhelmed. However, by adopting a structured approach and seeking expert guidance, you can confidently choose a policy that genuinely meets your needs and budget.
-
Assess Your Needs:
- Why do you want PMI? Is it primarily to avoid long waiting lists for surgery? Or do you also want quick access to diagnostics and specialist consultations for less serious concerns?
- What's your priority? Speed of access, choice of consultant, comfort and privacy, or extensive cancer cover?
- Consider your health: While pre-existing and chronic conditions are typically excluded, consider your general health trends. Do you anticipate needing physiotherapy or mental health support? (Remember, these are usually add-ons).
- Family needs: If covering a family, consider the needs of all members. Do you need maternity cover (often excluded or limited)? Paediatric care?
-
Define Your Budget:
- Be realistic about what you can comfortably afford each month or year. Remember that premiums will likely increase with age.
- Consider how much excess you're willing to pay. A higher excess will lower your premium, but you'll pay more out of pocket if you claim.
-
Choose Your Level of Cover:
- Inpatient Only: The most basic and lower-cost. Good if your main concern is major surgery or acute hospital admission.
- Comprehensive: Covers inpatient, day-patient, and extensive outpatient care (consultations, diagnostics). More expensive but offers greater peace of mind and convenience for almost all acute medical needs.
- Modular Options: Many insurers allow you to build your policy with core cover and then add specific modules like mental health, therapies, or dental/optical.
-
Select Your Hospital List:
- Do you need access to specific prestigious hospitals, or are you happy with a more general list that covers facilities conveniently located in Yorkshire?
- Opting for a more restricted or regional hospital list can significantly reduce your premium.
-
Understand Underwriting Methods:
- Moratorium: Simpler to set up, but you'll only know if a pre-existing condition may be covered after a 2-year symptom-free period.
- Full Medical Underwriting: Requires upfront disclosure of your medical history, but gives you clear exclusions from day one.
- Discuss the pros and cons of each with an expert to see which suits your medical history and preference for clarity.
-
Compare Quotes from Multiple Insurers:
- Don't just go with the first quote you get. Prices and policy features vary significantly between providers.
- Look beyond just the premium; compare what's included, what's excluded, and the benefit limits.
-
Read the Fine Print:
- Pay close attention to the policy wording, especially around exclusions (e.g., specific conditions, overseas treatment), limits on benefits (e.g., number of therapy sessions), and the claims process.
- Reiterate: Always remember that standard policies do not cover chronic or pre-existing conditions. Make sure you understand exactly what your chosen policy does not cover.
The Indispensable Role of a Regulated Broker
This is where a specialist at WeCovr or one of our broker partners becomes an invaluable resource. Navigating these complexities on your own can be time-consuming and lead to mistakes. WeCovr's expertise can streamline this process by:
- Regulated Advice: We work for you, not the insurers. We can provide unbiased recommendations based purely on your needs and budget.
- Market Access: We have access to policies from all the leading UK private medical insurance providers, including Bupa, AXA Health, Vitality, Aviva, WPA, and more. This allows us to compare a wide range of options quickly and efficiently.
- Expert Knowledge: We understand the nuances of different policy wordings, underwriting methods, and common pitfalls. We can explain complex terms in plain English.
- Tailored Solutions: Instead of generic quotes, we can help you build a bespoke policy by selecting the right core cover, add-ons, excess, and hospital list to match your specific requirements as a Yorkshire resident.
- Claims Support (often): While not directly processing claims, many brokers offer guidance and support throughout the claims process, helping to liaise with your insurer if needed.
- Annual Reviews: We can help you review your policy annually to ensure it still meets your needs and to check for more competitive options as your circumstances or the market changes.
By leveraging the expertise of WeCovr, you can save time, avoid confusion, and gain confidence that you have secured the most appropriate and cost-effective private medical insurance policy for you and your family in Yorkshire. We make it easy to compare and choose, ensuring you get the right cover without the hassle.
Making a Claim on Your Private Health Insurance
While the process can vary slightly between insurers, the general steps for making a claim on your private medical insurance are relatively consistent and designed to be straightforward once you understand them. The key is usually to involve your insurer before you incur significant costs.
-
Step 1: Consult Your GP Your journey typically begins with your NHS GP. If you develop a new (acute) symptom or condition, your GP will assess you. If they deem that you need to see a specialist or require diagnostic tests, they will provide a referral. This referral is crucial, as most private medical insurers require a GP referral before authorising private treatment.
-
Step 2: Contact Your Insurer for Pre-authorisation
- Once you have your GP referral, contact your private medical insurer before booking any appointments or tests. This is known as pre-authorisation and is a critical step.
- You will need to provide them with details of your condition, your GP's referral, and the type of specialist or diagnostic test recommended.
- The insurer will review your policy terms and confirm whether the proposed treatment may be covered. They will issue an authorisation number. This step ensures that your treatment will be paid for under your policy, avoiding any nasty surprises later.
- Critical Reminder: This is where the pre-existing and chronic condition exclusions come into play. If your condition is deemed pre-existing or chronic (based on your underwriting method and policy terms), the insurer will decline to authorise cover for it.
-
Step 3: Book Your Appointment/Treatment
- Once you have authorisation, you can book your appointment with the specialist or facility. Your insurer might provide a list of approved consultants and hospitals. If you have an "Open Referral" policy, you'll have more flexibility in choosing a consultant.
- Inform the private hospital or clinic that you have private medical insurance and provide them with your policy number and the authorisation number.
-
Step 4: Receive Treatment
- Attend your consultation, undergo diagnostic tests, or receive your treatment/surgery.
- In most cases, the hospital or consultant will bill your insurer directly. You will only be responsible for paying your policy excess (if applicable) and any costs for treatments or services not covered by your policy.
-
Step 5: Pay Your Excess (if applicable)
- Your insurer will deduct your excess amount from the total claim. You will usually pay this directly to the hospital or consultant. For example, if your excess is £250 and your treatment costs £1,000, you pay £250, and the insurer pays £750.
What to Do if a Claim is Denied
While a smooth claims process is common, occasionally a claim might be denied. This can be frustrating, but understanding the common reasons can help:
- Pre-existing Condition: This is the most frequent reason. If the insurer determines the condition for which you are claiming existed or had symptoms before you took out the policy (and is therefore excluded under your underwriting terms), the claim will be denied.
- Chronic Condition: As explained, ongoing management of chronic conditions is not covered. If your claim relates to the long-term management of a chronic illness, it will be denied.
- Lack of Pre-authorisation: If you proceeded with treatment without obtaining pre-authorisation from your insurer, they may decline to pay, or only pay a reduced amount.
- Exceeded Policy Limits: Your policy may have annual or per-condition limits for certain benefits (e.g., outpatient consultations, therapy sessions). If you've exceeded these, subsequent claims will be denied.
- Treatment Not Covered: Certain treatments or services might be explicitly excluded from your policy (e.g., cosmetic surgery, fertility treatment, or experimental treatments).
- Incomplete Information: Failing to provide necessary medical reports or referral letters can delay or cause a denial.
If your claim is denied:
- Understand the Reason: Ask your insurer for a clear explanation of why the claim was denied, referencing your policy terms.
- Review Your Policy: Cross-reference the reason with your policy documents.
- Appeal: If you believe the denial is incorrect, you have the right to appeal the decision. Provide any additional supporting documentation.
- Seek Broker Support: If you used a WeCovr specialist or one of our broker partners, contact us. We can review the situation, liaise with the insurer on your behalf, and help you understand your options or navigate the appeals process.
Making a claim on your private health insurance in Yorkshire is generally efficient, particularly if you follow the pre-authorisation steps. This streamlined process is a key benefit, allowing you to focus on your recovery rather than administrative hurdles.
Corporate and Group Private Health Insurance in Yorkshire
Beyond individual policies, a significant portion of private medical insurance in Yorkshire is provided through corporate or group schemes. Many employers, from small businesses to large corporations, offer private health insurance as a valuable employee benefit. This type of cover comes with distinct advantages for both the employer and the employee.
Benefits for Employers in Yorkshire
- Employee Attraction and Retention: In a competitive job market, offering PMI is a highly desirable perk that can help attract top talent and boost loyalty, especially in regions with a strong professional sector like Leeds and Sheffield.
- Reduced Absenteeism: By providing quick access to diagnosis and treatment, employees can often return to work sooner after illness or injury, reducing long-term sickness absence and its associated costs for the business.
- Improved Productivity: Healthy employees are more productive. By supporting employee well-being, employers can foster a more engaged and efficient workforce.
- Enhanced Morale: Demonstrating care for employee health and welfare can significantly boost morale and create a positive working environment.
- Tax Efficiencies: For employers, the cost of group PMI is typically treated as a tax-deductible business expense.
Benefits for Employees in Yorkshire
- Often More Comprehensive Cover: Group schemes often provide a higher level of cover than an individual could afford, with extensive outpatient limits, mental health support, and robust cancer care.
- Simplified Underwriting: For larger groups, medical history is often overlooked or simplified, meaning pre-existing conditions that might be excluded on an individual policy could be covered (though chronic conditions typically remain excluded). This is known as "Medical History Disregarded" (MHD) underwriting, common for groups of 10-15+ employees, where individual medical questions are not asked. For smaller groups, a simpler form of moratorium or individual underwriting may apply.
- Cost-Effective: Employees usually get access to private medical insurance at a much lower cost than they would if purchasing an equivalent individual policy, as the risk is spread across the group.
- Convenience: The policy is managed by the employer, reducing administrative burden for the employee.
- Access for Family Members: Many schemes allow employees to add family members (spouse/partner and children) to the policy, often at WeCovr car insurance rates.
Tax Implications for Employees
It's important for employees to be aware that private medical insurance provided by an employer is generally considered a "Benefit in Kind" (BiK) by HM Revenue & Customs (HMRC). This means the value of the premium paid by the employer on your behalf is taxable income, and you will typically pay income tax on this benefit. It will appear on your P11D form at the end of the tax year.
Setting Up a Group Scheme in Yorkshire
For businesses in Yorkshire considering offering private medical insurance, working with a WeCovr specialist or one of our broker partners is highly recommended. We can:
- Assess Business Needs: Understand the size of your workforce, budget, and specific goals.
- Compare Group Policies: Source and compare suitable group schemes from all major UK insurers, leveraging our access to corporate rates and terms.
- Explain Underwriting Options: Advise on the most appropriate underwriting method for your group size and demographics (e.g., Medical History Disregarded vs. Moratorium).
- Manage Implementation: Assist with the setup, employee communication, and ongoing management of the policy.
- Provide Ongoing Support: Ensure the scheme remains competitive and meets the evolving needs of your business and employees.
Group private medical insurance represents a significant investment in employee well-being and a strategic move for businesses looking to enhance their value proposition in the competitive Yorkshire employment landscape. It ensures that your workforce has swift access to quality healthcare, keeping them healthy, happy, and productive.
The Future of Private Health Insurance in Yorkshire
The landscape of healthcare in the UK is constantly evolving, and private health insurance is no exception. Several key trends are shaping the future of PMI, particularly in regions like Yorkshire, where a strong demand for efficient healthcare solutions persists.
-
Continued Demand Driven by NHS Pressures: As the NHS continues to grapple with increasing demand, staff shortages, and financial constraints, the waiting lists are likely to remain a significant challenge. This sustained pressure will inevitably continue to drive more individuals and businesses in Yorkshire towards private health insurance as a necessary complement or alternative. The public's perception of the NHS's ability to provide timely care for non-emergency conditions is a major factor here.
-
Integration of Digital Health and Telemedicine: The pandemic accelerated the adoption of digital health solutions, and this trend is set to deepen within PMI.
- Virtual GP Services: Many policies now include 24/7 access to online GPs, offering consultations via video or phone, reducing the need for in-person visits and providing immediate advice. This is particularly beneficial for those in more rural parts of Yorkshire.
- Remote Monitoring: Technology for remote monitoring of chronic conditions is advancing rapidly. While chronic conditions are not generally covered, insurers may explore ways to support acute exacerbations or pre-emptive care using digital tools.
- Online Platforms: Easy access to policy documents, claims submission, and health information via insurer apps and online portals.
-
Focus on Preventative Care and Wellness Benefits: Insurers are increasingly shifting from purely reactive care (treating illness) to proactive prevention and wellness. This aims to keep policyholders healthier, reducing the number and severity of claims in the long run.
- Health Assessments: Offering free or discounted health screenings and check-ups.
- Wellness Programs: Incentives for healthy living, such as discounts on gym memberships, wearable tech, and healthy food options. Vitality is a pioneer in this area, linking premiums to activity levels.
- Mental Well-being Support: Growing emphasis on mental health, with policies offering access to therapy and counselling services, often integrated with digital tools.
-
Personalisation and Modular Policies: The trend towards highly customisable policies will continue. Instead of rigid plans, insurers will offer more modular options, allowing individuals to select specific benefits (e.g., only cancer cover, specific therapies, or just diagnostic access) to build a plan that precisely fits their needs and budget. This flexibility makes PMI more accessible to a wider demographic in Yorkshire.
-
Impact of Medical Inflation and Innovation: Advancements in medical technology, new drugs, and innovative treatments are constantly emerging, but they often come at a significant cost. This "medical inflation" typically outpaces general inflation, meaning premiums will likely continue to rise year-on-year. Insurers will need to balance offering access to cutting-edge treatments with maintaining affordability.
-
Regionalisation and Localised Networks: While national networks are important, there may be a growing emphasis on regionalised hospital lists and partnerships. For Yorkshire, this could mean more bespoke policy options that focus specifically on the excellent network of private hospitals within the region, potentially offering more competitive premiums for local residents who don't require national access.
The future of private health insurance in Yorkshire is one of increasing relevance, driven by the need for timely access to care. It will also be characterised by technological integration, a stronger emphasis on holistic well-being, and greater customisation, making it an even more integral part of many Yorkshire residents' healthcare planning.
Conclusion: Securing Your Health Future in Yorkshire
For residents across Yorkshire, the decision to invest in private medical insurance is increasingly becoming a pragmatic one, driven by the very real challenges facing the cherished National Health Service. While the NHS will always remain the bedrock of UK healthcare, the pressures it faces mean that for acute, non-emergency conditions, waiting times can be long and uncertain. This delay can cause significant anxiety, pain, and a detrimental impact on your quality of life.
Private medical insurance offers a powerful antidote to these concerns. It provides:
- Swift Access: Bypassing lengthy NHS waiting lists for diagnosis, specialist consultations, and essential treatments.
- Enhanced Choice: The ability to choose your consultant and private hospital within Yorkshire, empowering you with greater control over your care.
- Superior Comfort and Privacy: Access to private rooms and a more serene environment conducive to recovery.
- Peace of Mind: The invaluable reassurance that if an acute health issue arises, you have a clear, rapid pathway to high-quality treatment.
It is crucial to reiterate that standard UK private medical insurance policies are designed for acute conditions that arise after the policy begins. They do not cover chronic or pre-existing conditions. Understanding this fundamental distinction is paramount to selecting a strong fit for your needs and managing your expectations.
The Yorkshire region is fortunate to host an impressive network of leading private hospitals and clinics, meaning premier care is often close to home, whether you're in a bustling city or a tranquil rural area.
Navigating the complexities of policy types, underwriting methods, and cost factors can be challenging. This is precisely where expert, regulated advice becomes invaluable. WeCovr, sometimes working with broker partners, stands ready to assist you. We understand the nuances of the market and have access to comprehensive policies from all major UK insurers. A WeCovr specialist or trusted broker partner can help you compare options, understand the fine print, and tailor a private medical insurance policy that perfectly aligns with your specific health needs and financial circumstances as a Yorkshire resident.
Don't let health concerns wait. Take control of your healthcare journey and secure the timely, quality care you deserve. Explore your options for private medical insurance in Yorkshire today.
Get a quote through WeCovr, and a specialist from WeCovr or one of its broker partners will help you compare policies from a range of UK insurers.
Sources
- NHS England: Waiting times and referral-to-treatment statistics.
- Office for National Statistics (ONS): Health, mortality, and workforce data.
- NICE: Clinical guidance and technology appraisals.
- Care Quality Commission (CQC): Provider quality and inspection reports.
- UK Health Security Agency (UKHSA): Public health surveillance reports.
- Association of British Insurers (ABI): Health and protection market publications.
Important Information and Risks
No advice: This article is for general information only. It is not financial, legal, insurance, or tax advice, and it is not a personal recommendation. WeCovr does not assess your individual circumstances or recommend a specific product through this article.
Policy exclusions and underwriting: Insurance policies, including life insurance, private medical insurance, critical illness cover, and income protection, are subject to insurer underwriting, eligibility, acceptance criteria, terms, conditions, limits, and exclusions. Pre-existing medical conditions may be excluded, restricted, or accepted on special terms unless an insurer confirms otherwise in writing.
Tax treatment: References to tax treatment, HMRC rules, or business reliefs are based on current UK legislation and guidance, which can change. Tax treatment depends on your personal or business circumstances and may differ from examples in this article.
Before you buy: Always read the Insurance Product Information Document (IPID), policy summary, and full policy terms before buying, renewing, changing, or keeping cover. If you are unsure whether a policy is suitable for you, speak to an insurance adviser.
Compare private health insurance quotes from leading UK insurers
Answer a few quick questions and a specialist from WeCovr or one of its broker partners will help you compare cover from insurers such as Bupa, AXA, Aviva and Vitality. No obligation.
Takes about 2-3 minutes
Compare cover from leading UK insurers
No obligation to buy
Get a quote
Get a private health insurance quote
Answer a few questions, then a specialist helps you compare cover and prices.
Tell us who needs cover
Just you, a partner, your family or your staff.
Compare your options
A specialist compares cover and prices from leading UK insurers.
Decide in your own time
There is no obligation to buy.
What you get
A specialist from WeCovr or one of its broker partners
Options compared across leading UK insurers
No obligation to buy